How to Actually Use a Bail Bonds Practice Test Without Wasting Your Money
You grab a practice test, answer the questions, see how many you got right, and close the browser. That is most people using one. It rarely works because answering questions correctly is not the same thing as learning the material. I have sat across from agents who scored 80 percent on every practice exam they could find and still failed their state's licensing test because the exam writers deliberately triangulate around the distractors. A practice test is a diagnostic tool, not a study plan. Its only job is to show you exactly what you do not know before you spend hours reading a textbook. If you treat it as a confidence booster you are doing it wrong. If you treat it as a map of your weak spots you will finish studying in about half the time most agents take. The structure you should follow is simple and not glamorous.
- Take the first practice test cold. No notes, no book. Time yourself. Write down every answer you guessed on, even the ones you got right.
- Grade it. Record the score but do not obsess over it yet.
- Go through every question you missed and every question you guessed on. Read the explanation if one exists. If it does not, look it up in your state's bail bonds statute or your pre-licensing manual.
- Build a single document with the missed topics and your one-sentence rule for each. Five topics usually covers eighty percent of your gaps.
- Study those five topics. Then take a second practice test under timed conditions.
- Repeat until your second score is twenty points higher than your first and your guess rate has dropped below three questions per test.
That second score gap matters more than any raw number. When my guess rate falls below three, I know I am no longer pattern-matching the answer choices. I am actually applying the statute. Here is a part most prep materials do not emphasize. Practice tests vary wildly in quality. A test written by someone who has never filed a forfeiture in their jurisdiction will get procedural details wrong and you will memorize the wrong procedure. Before you invest more than an hour in any test, open a few questions at random and check them against your state's official bail code. If the explanations contradict the statute, discard the test immediately. I learned that the hard way with an older prep package I bought years ago. It treated a notice of appeal in a forfeiture as a thirty-day filing window in every state. In my state it is twenty days from the entry of the judgment, not from the date on the paper. I almost wrote that wrong on my exam. I caught it because I kept a copy of the current statute open while I worked the practice questions and noticed the mismatch after question seventeen. I flagged the error, wrote the correct rule in my own notes, and moved on. That single correction probably saved my license.
The Calculations You Will Lose Points On
The math section is where most candidates bleed points, and it is almost entirely predictable. Premiums, refunds, collateral valuation, and forfeiture calculations cycle in the same patterns. State law controls the percentage, but the arithmetic is uniform. Learn these rules without exception for your jurisdiction:
Get the Full Details
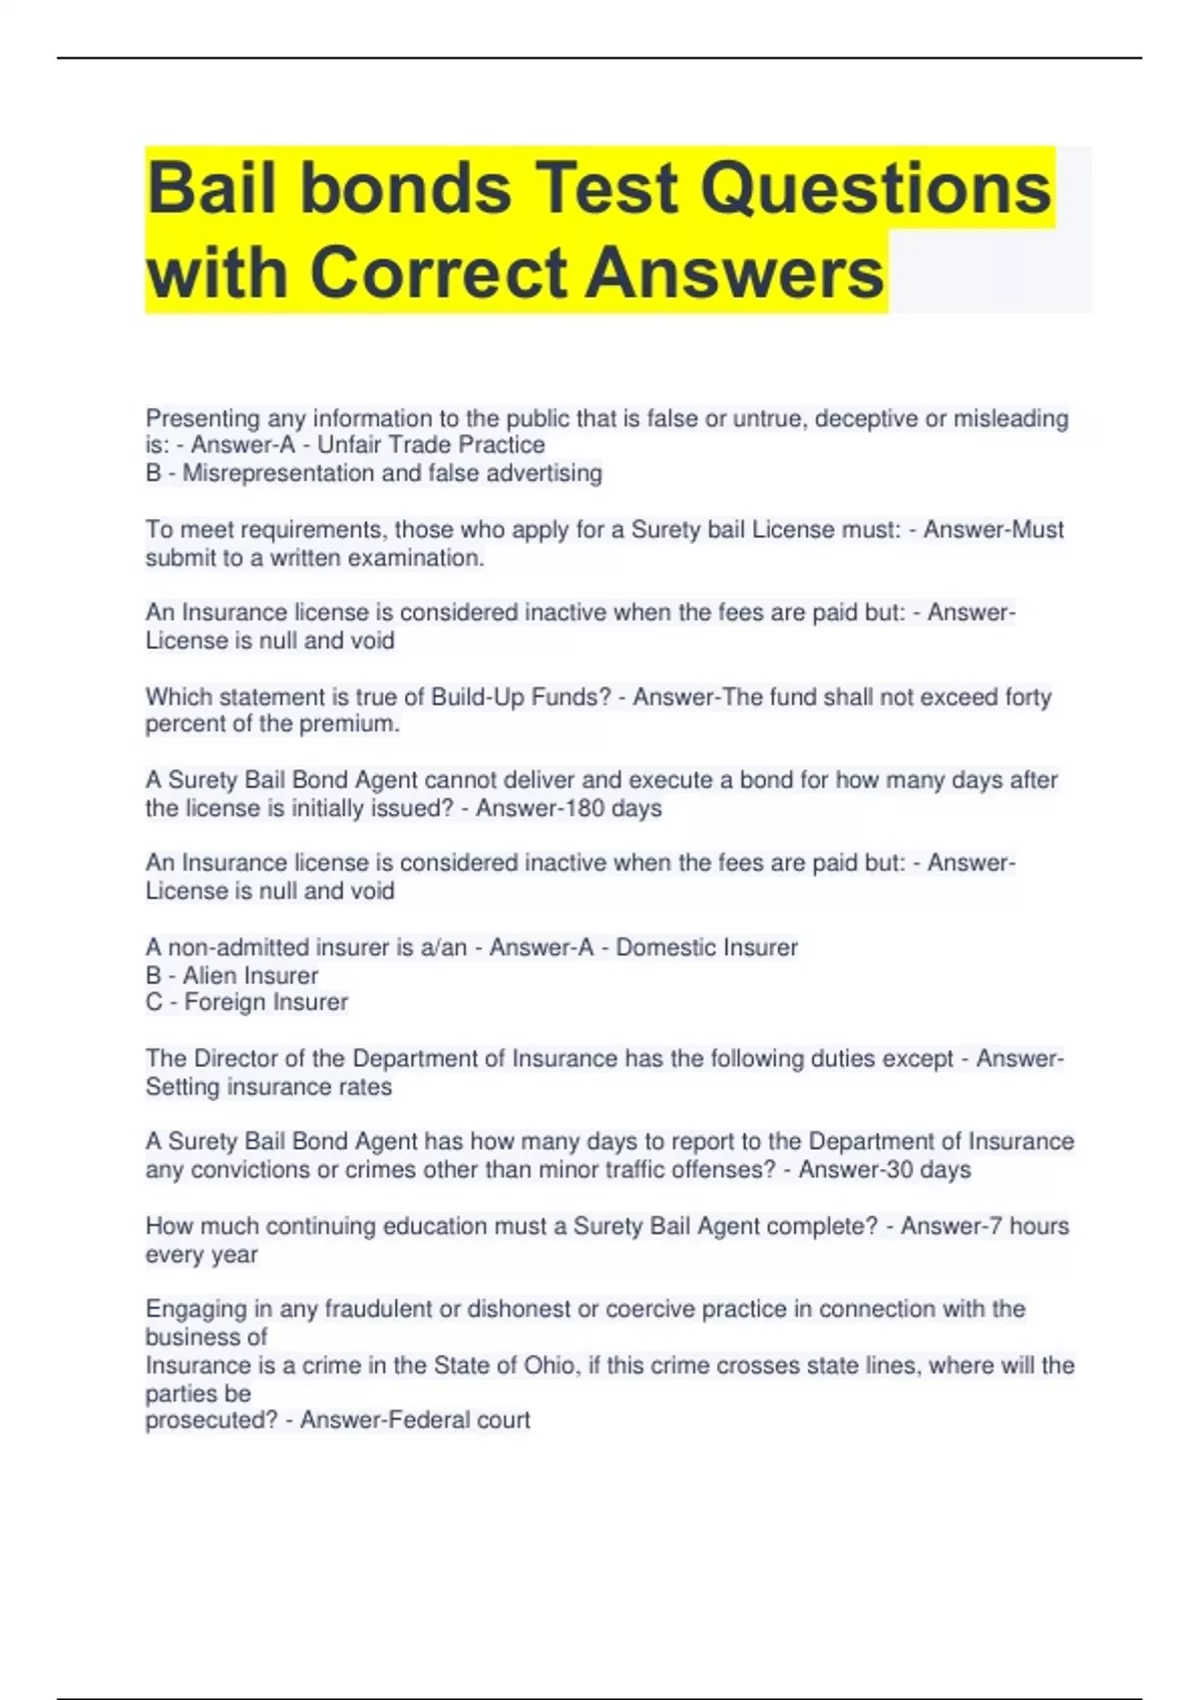
- Premium is usually a flat percentage of the face amount, not of the collateral value. If the question says a $10,000 bond at 10 percent premium with a car pledged as collateral worth $15,000, the premium is $1,000, not $1,500. The car's value is irrelevant to the premium calculation.
- Refund calculations apply to the premium, not the face value. Partial periods use a pro-rata method unless your state statute says otherwise. Some states cap refunds at a minimum earned premium even if the exposure period was very short.
- Collateral valuation for indemnity purposes is liquidation value, not retail value. Questions that offer retail appraisals as the correct answer are testing whether you know the difference.
- Forfeiture exposes the indemnitor to the full face amount minus any payments already made on the premium or as directed by the court. It does not automatically mean you lose the entire collateral if payments were made, but the exposure still starts at face value.
When I review my own practice tests now, I skip the scenario questions on the first pass and do the calculations first. Getting the math right locks in points quickly. The wordy questions are where time disappears. Exam writers use three tactics to make correct answers look wrong. First, they include a true statement that does not answer the question. The prompt will ask for the primary duty of the agent when a defendant skips court. Four of the five answers will contain true facts. Only one addresses the primary duty. The others might describe secondary duties, unrelated obligations, or statements that are technically accurate but off-topic.
Second, they use absolute language in the wrong answers. Words like always, never, and must appear in distractors far more often than in correct answers, especially on ethics questions. Your state's code of conduct will have exceptions. Any answer that removes those exceptions is probably wrong. Third, they swap two similar-looking numbers or dates. A ten-day deadline becomes a fifteen-day deadline in one answer and a twenty-day deadline in another. The difference is small enough that skimming misses it. Write the key number from the prompt on your scratch paper before you read the choices. It takes three seconds and it prevents three or four wrong answers per test.
When a Practice Test Fails You
A practice test cannot replace three things. It cannot teach you your state's specific statutory citations. It cannot replace hands-on experience with collateral paperwork. And it cannot replicate the actual exam's timing pressure if you have never practiced under real conditions. If you take a practice test on your phone between appointments, you are not simulating exam conditions. Do at least one full timed session on paper with a timer running. The physical act of filling bubbles or writing answers under time changes how your brain retrieves information. Most agents who only practice digitally underperform on the real exam by roughly ten percent. That gap is almost entirely about pacing, not knowledge. Another failure mode is using practice tests from other states. The question structures are similar, but the legal distinctions are not. If you study Florida material for the California exam, you will memorize the wrong renewal deadlines and the wrong requirements. Check the state identifier on the cover or the product description before you start. A test that says general or national is useful for concept review but unreliable for jurisdiction-specific memorization.
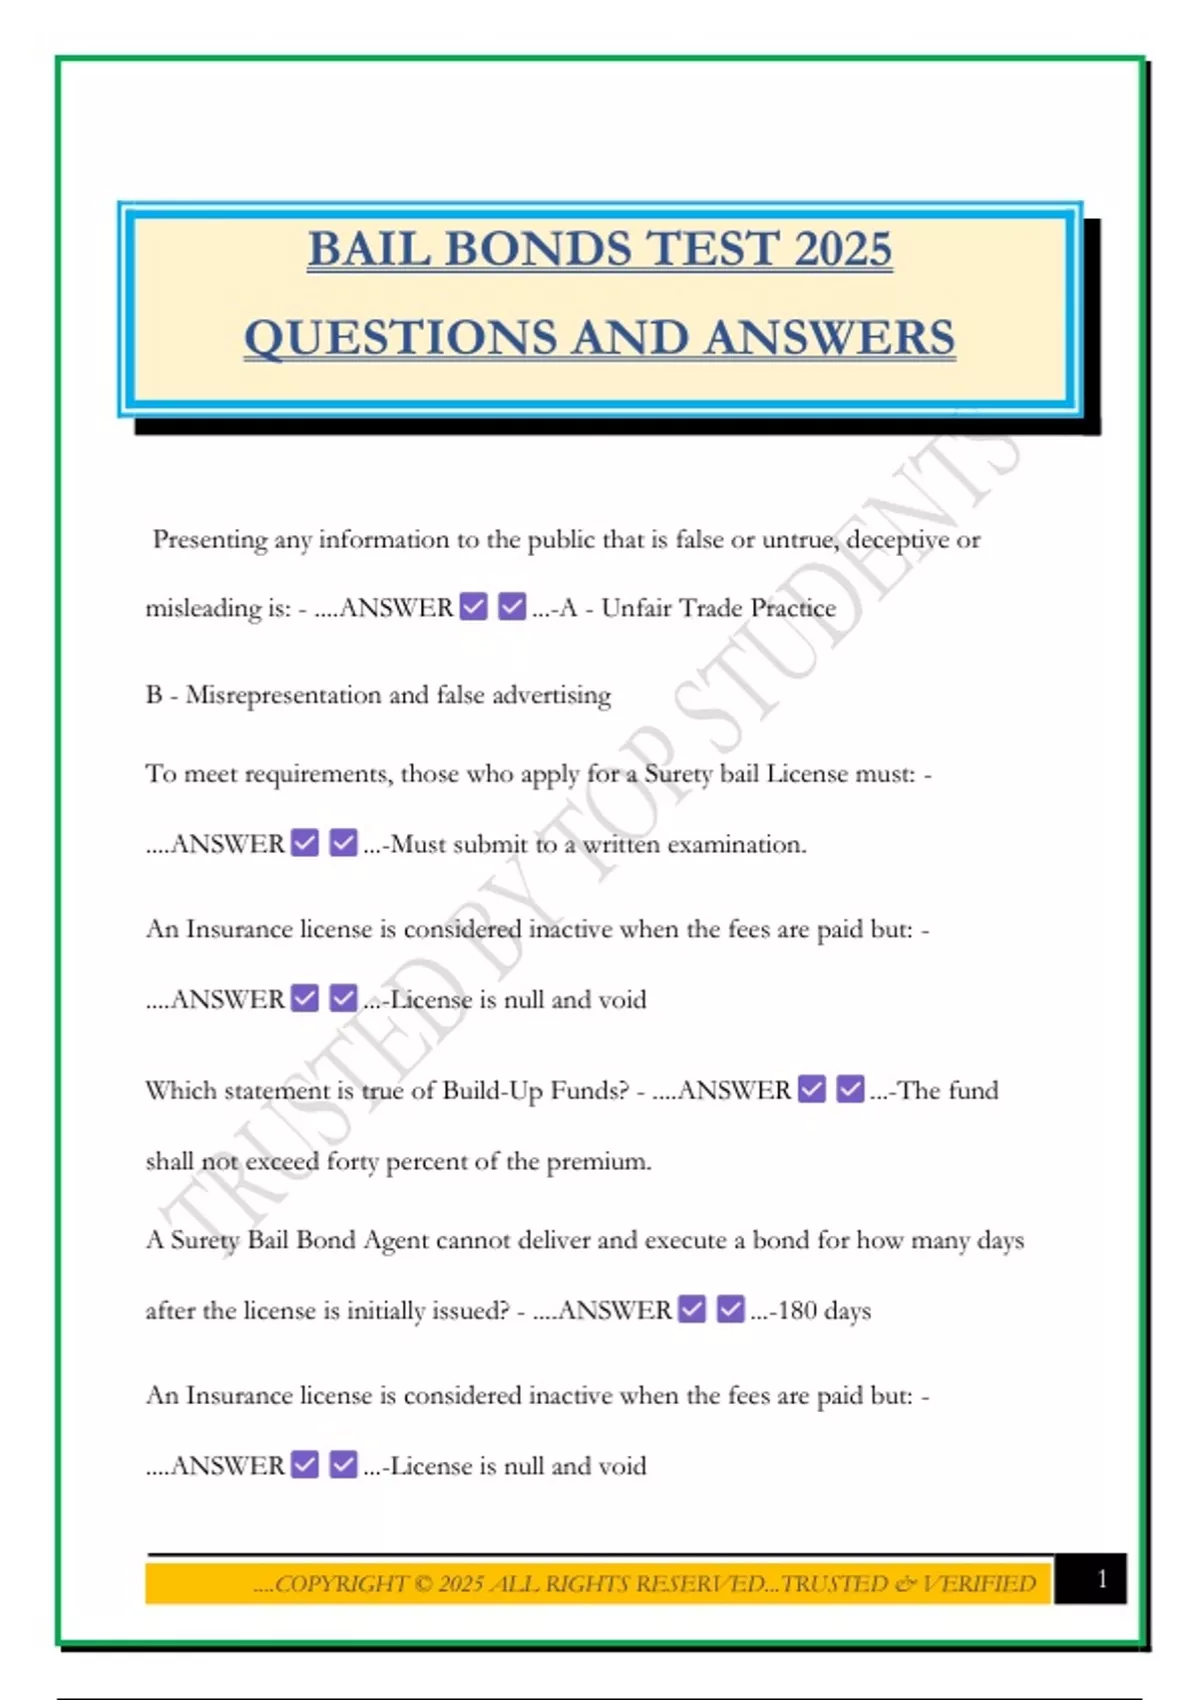
If your goal is fast results and you score below sixty percent on your first cold practice test, stop taking new tests for a week. You are reinforcing bad habits. Spend that week studying the statute and doing the calculations by hand. Then return. The score usually jumps eight to twelve points after a focused statute review. There is also a practical workaround I use when a practice test has no explanations. I copy the question and the four wrong answers into a notes app, then I search the state statute for each key term from the question. Matching the exact statutory language to the answer choices teaches you more than seeing the right answer highlighted in red. It trains your brain to recognize how the statute will phrase things on the actual exam.
Where to Find a Decent Practice Test
Most legitimate sources are free or inexpensive. Your state's department of insurance or licensing board often publishes sample questions or a study guide with a question bank. Those are the most accurate because they are written by the people who commission the exam. Use those first. Commercial test prep packages from established bail bond schools are usually adequate if you verify they match your state. Avoid anything that claims a ninety percent pass rate. That is a sales tactic, not evidence. Passing rates on these exams are typically seventy to eighty percent for first-time test-takers who studied. A vendor promising near-certainty is selling you something else. If you want a direct, free option, search for the official sample questions from your state's licensing authority and any study guide they publish. I keep a folder on my computer with the current sample sets for California, Texas, Illinois, and Florida because the structure is always similar and the free samples are closer to the real thing than most paid tests. They are not perfect, but they are the baseline you should start from before buying anything.
The real test is whether you can explain each wrong answer out loud and say exactly why it is wrong. If you can do that for every question on a practice set, you are ready. If you can only identify the right answer, you are not ready yet.