Understanding the actual mechanics behind balance sheet management
Most people treat the balance sheet like it's just a report card for the bank. It's not. It's a living, breathing machine that either makes money or loses money depending on how you manage the gap between assets and liabilities. I've seen banks with perfectly fine loan portfolios hemorrhage cash because someone on the ALCO (Asset Liability Committee) desk didn't understand what was happening with their deposit betas during rate shifts. That's where the real work lives. At its core, this is about managing the mismatch between when money comes in and when it goes out, plus the risk that interest rates will move against you. You have deposits on one side that can flee the bank, and loans on the other side that might pay fixed rates for years. When the Fed hikes rates, your cost of funds jumps almost immediately but your loan yields take quarters to catch up. That spread compression is where margin dies. The standard toolkit includes gap analysis, duration matching, and net interest income simulation. But the textbooks leave out the stuff that actually matters on a Tuesday afternoon when something breaks.
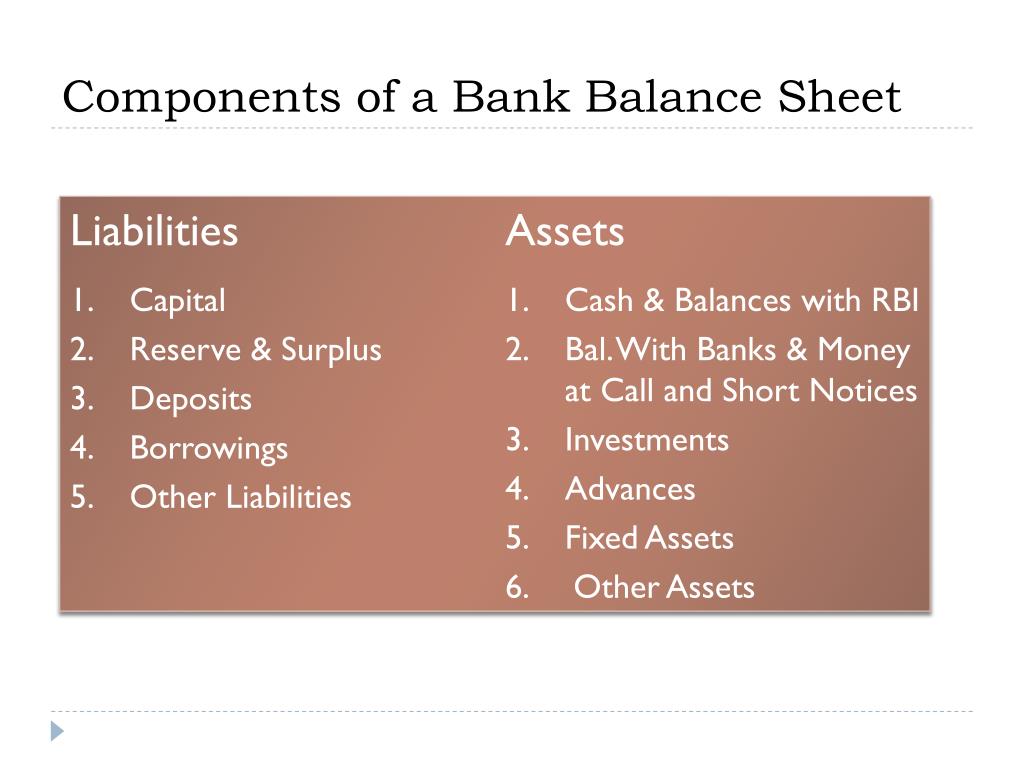
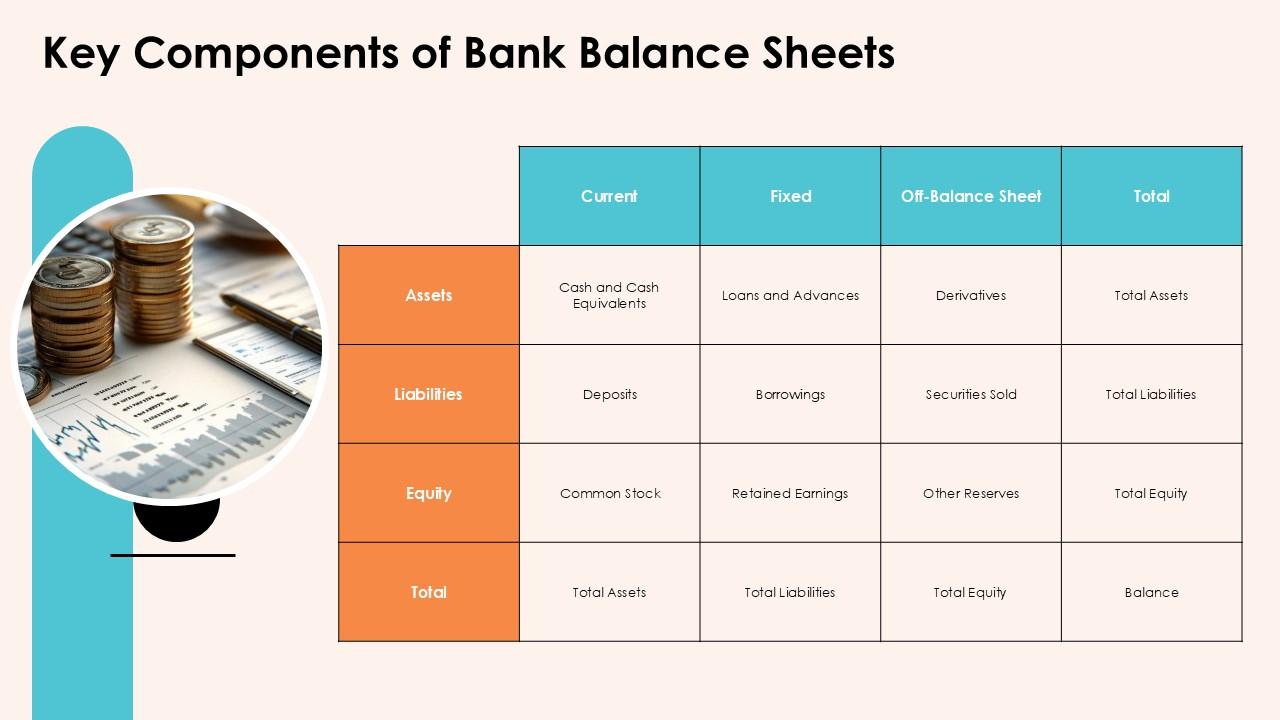
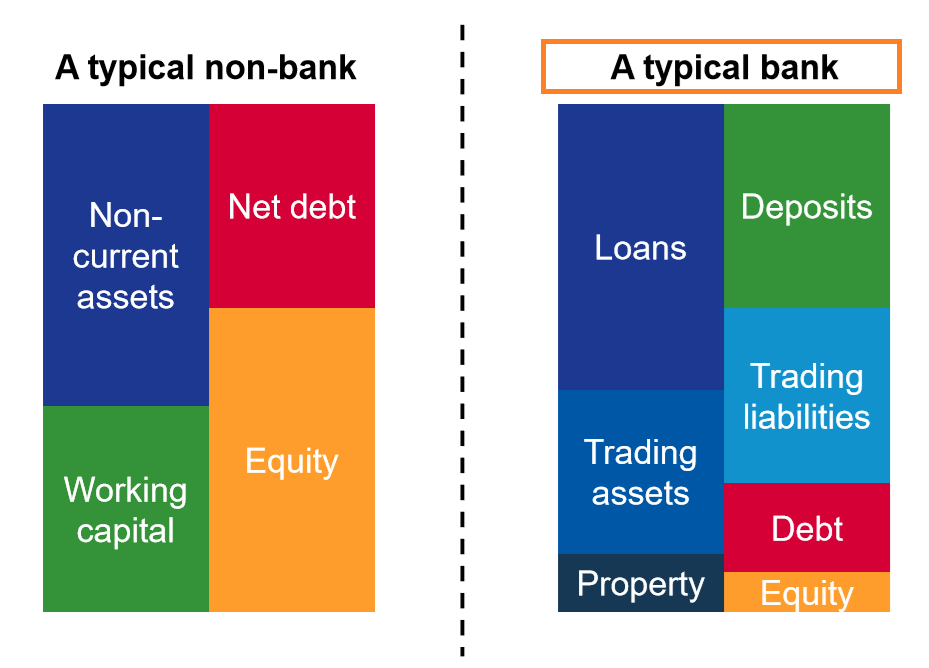
I remember this one time, around 2022, we had a situation where our commercial deposit base started rolling off faster than our models predicted. The Fed had been hiking for months, money market funds were offering 4%, and our relationship managers were getting calls from corporate treasurers demanding better terms. Our standard alpha-beta deposit model assumed a 60% stickiness on non-maturity deposits, but that assumption went out the window within about three weeks. We ended up running an ad-hoc sweep using our transaction account analysis (TAA) data, looking at actual historical withdrawal patterns by customer segment, and recalibrating the beta estimates weekly instead of quarterly. It took about four hours to build out the revised model, but it saved us from over-paying on liability costs that would have dragged NII down by roughly 8 to 12 basis points over the following quarter. Here's the thing most people miss: balance sheet management isn't just about interest rate risk. It's also about liquidity coverage, capital allocation, and the hidden correlation between credit losses and funding costs. When a bank's credit quality deteriorates, its cost of wholesale funding often spikes simultaneously. That double squeeze can kill a balance sheet faster than anything else. The realistic workflow looks something like this. You start by pulling your balance sheet components into a structured format, breaking them into buckets by maturity, repricing frequency, and behavioral assumptions. Then you run a series of rate shock scenarios across your projected balance sheet. Most institutions use a basic static gap model as a starting point, which calculates the difference between rate-sensitive assets and rate-sensitive liabilities at various time horizons. That gives you a quick read on exposure but it's fairly crude.
From there you layer in dynamic simulation. This means projecting how the balance sheet will actually evolve under different rate environments, accounting for new loan originations, deposit attrition, amortization schedules, and behavioral shifts. The output is a range of potential net interest income outcomes. You then decide what to do about it. The decision-making part happens at ALCO, usually biweekly or monthly. You look at the simulation results, assess the current market environment, and determine whether you need to adjust the mix of assets and liabilities. That could mean accelerating or decelerating loan growth, pricing deposits differently, adding or reducing securities holdings, or using derivatives like interest rate swaps to hedge specific exposures. The goal is keeping net interest margin within target while staying within risk appetite limits set by the board. Let me tell you about a few pitfalls that aren't in any certification material.
Get the Full Details
First, the biggest source of error I've seen in balance sheet projections is bad deposit behavior modeling. Banks routinely rely on regulatory proxies for stable deposit assumptions, which work fine for compliance but are terrible for strategic decision-making. The difference between using the regulatory 10-year treasury swap rate as a proxy and actually modeling your own deposit beta curve can result in NII forecasts that are off by 15 to 25 percent over a two-year horizon. That's not a rounding error. That's a strategic planning failure. Second, people tend to focus heavily on the trading account but neglect the banking book hedge effectiveness. If you're using swaps to hedge your portfolio, you need to track not just the fair value but also the cash flow impact and any basis risk. I've watched hedge ratios get completely off because someone forgot that the swap curves and the deposit/loan repricing curves don't move in perfect lockstep. The 3-month LIBOR to SOFR transition made this significantly worse for a lot of institutions. Third, there's the cross-sell effect that nobody builds into their models. When you price a certificate of deposit competitively to retain a relationship, that customer often moves checking and savings balances too. The deposit beta model should account for the overall relationship value, not just the individual product. Some smaller banks actually track customer-level economics across all products, which takes more work upfront but pays off during rate cycles.
On the tools side, most mid-size banks run this in Excel with various spreadsheets and lookup tables. It's painful and error-prone. Larger institutions use dedicated platforms like Black Knight, Moody's Analytics, or FI Solutions. The tradeoff is clear: spreadsheets cost almost nothing in licensing but require manual effort and have version control issues that cause audit findings. Platforms cost six figures annually but automate much of the data pipeline and scenario testing. For a bank with under $5 billion in assets, I'd suggest starting with a well-structured spreadsheet that uses clean data sources and automated import routines, then moving to a platform once the processes are mature enough to justify the investment. The transition itself is usually a 3 to 6 month project involving data mapping, validation, and parallel runs. There's also a growing space around real-time monitoring tools that give you near-live visibility into your gap position. These are particularly useful for regional banks with active trading desks or those that frequently adjust their securities portfolio. The cost ranges from $50,000 to $200,000 annually depending on functionality, but they can reduce the lag between a market event and your response from days to hours. If you're starting from scratch and need a practical entry point, I'd recommend building a simplified gap analysis model first. Pull your balance sheet, categorize each line item by repricing date or maturity, calculate the cumulative gap at each bucket, and run a few flat rate change scenarios. That alone will give you a baseline understanding of your exposure. Then layer in the behavioral adjustments and dynamic projections as your comfort level grows.
One more thing that nobody emphasizes enough: communication with the board and senior management. The best balance sheet strategy in the world doesn't matter if you can't explain to the board why you're taking a particular hedge position or why NII might decline under a steep curve scenario. I've seen ALCO presentations where the presenters buried the key risk drivers under too much detail. The board members aren't there to learn actuarial science. They need to know the direction of travel, the magnitude of risk, and what actions are being taken. Keep it focused on the decisions that need to be made. The regulatory side adds another layer of complexity. Basel III introduced the Net Stable Funding Ratio (NSFR) and Liquidity Coverage Ratio (LCR), which constrain how you can fund certain assets. These ratios interact with your interest rate risk management in ways that aren't immediately obvious. For example, holding more high-quality liquid assets improves your LCR but may lower your yield. The optimal balance depends on your specific asset composition and funding profile. Running these metrics alongside your IRB (Internal Rate Buffer) analysis is essential. Looking ahead, the environment is likely to keep challenging the traditional assumptions. If we stay in a higher-for-longer rate environment, deposit competition will intensify and the cost of core funding will remain elevated. That compresses margins for banks that can't price deposit relationships effectively. If rates do eventually come down, the flip side problem emerges where reinvestment risk becomes the dominant concern. The banks that manage both directions well are the ones that invest in robust modeling infrastructure and maintain disciplined ALCO governance.