
The Reality of Reconciling Your Own Account
You get the statement, you open your spreadsheet, and suddenly you're three dollars short. This happens more often than people admit. It's not dramatic—it's just arithmetic catching up with reality. A Balancing A Checkbook Worksheet is really just a structured way to find where that gap came from without going insane. It's a reconciliation ledger. You take your bank statement balance, adjust for items the bank doesn't know about yet, then compare that to what you think you should have based on your own records. The two numbers need to match. When they don't, the worksheet becomes the place you track every adjustment until you find the mismatch. Most people try to do this in their head or with random sticky notes. That works fine for one or two months. Then you miss a transaction, or the bank posts something unexpected, and you're back to square one. A proper worksheet locks everything down so you can look back at it later.
The Method I Actually Use
Here's the sequence I've stuck with for years. It's not complicated but it needs to be consistent: Step 1 — Write down the ending balance from your bank statement. This is the starting point, not your checkbook balance. People mix this up constantly. Step 2 — Add any deposits in transit. These are deposits you made that haven't appeared on the statement yet. If you dropped money in the ATM the night before the statement closed, it won't show up until the next cycle.
Step 3 — Subtract any outstanding checks. These are checks you wrote that the person hasn't cashed yet. A vendor might hold onto a check for weeks. That money is still in your account technically, but the bank statement doesn't reflect it. Step 4 — Adjust for bank errors if you find any. These are rare but they happen. A teller entering the wrong amount, a deposit posted to the wrong account. When you spot one, note it clearly with the date and a brief description. Step 5 — Adjust for items the bank recorded that you haven't. Service charges, interest earned, direct deposits you forgot about. These go on the bank side because they're already reflected in the statement.
Get the Full Details
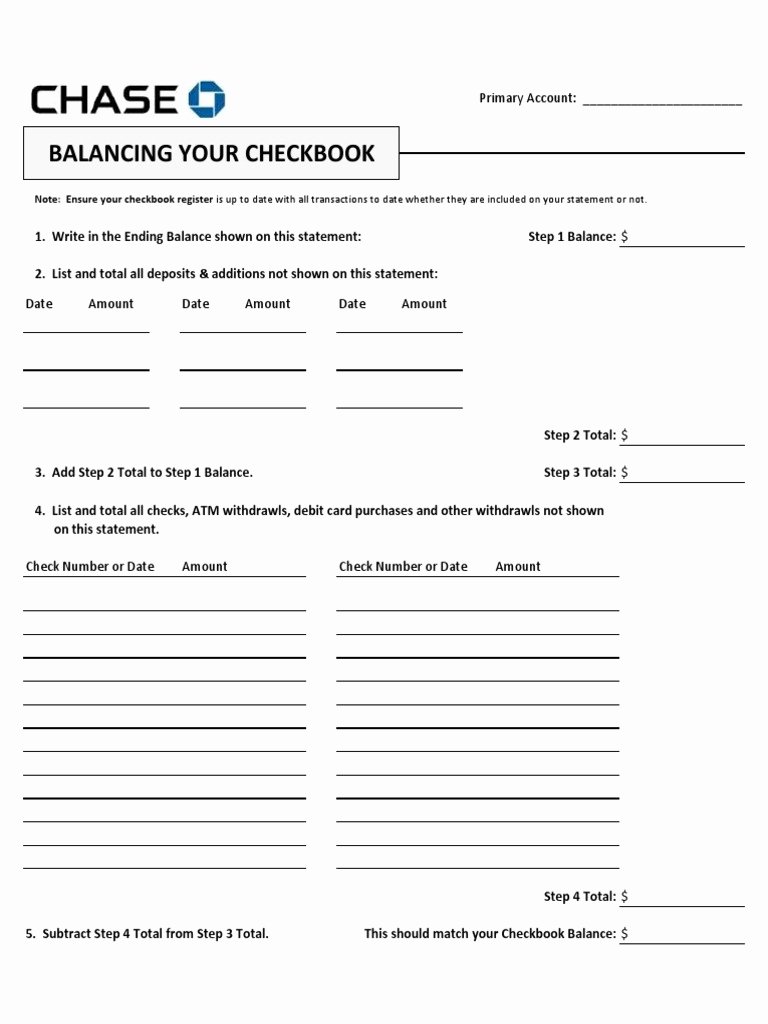
Step 6 — Write down your checkbook balance. This is what your own records say you should have. Step 7 — Adjust your checkbook balance for things you missed or recorded wrong. A forgotten recurring payment. A duplicate entry. An incorrect amount. Step 8 — Compare the two adjusted balances. If they match, you're done. If they don't, the difference tells you where to look.
I've done this for over a decade across dozens of accounts. The process itself takes maybe ten to fifteen minutes once you're familiar with it. The hard part isn't the math—it's finding the mistake when the numbers don't line up.
Where People Get Stuck (And What I Found)
The biggest issue I run into is the $0.01 or $0.07 discrepancy. These seem meaningless but they point to something specific. A $0.01 difference usually means a rounding issue or a fee you didn't account for. A $0.07 difference often means you missed a transaction by exactly seven dollars, or you recorded a $7.00 fee as $7.07 or vice versa. Here's an example that cost me an entire evening once. I was reconciling a business account and kept coming up short by $43.50. I went through every single transaction three times. I pulled the bank statement, I pulled my register, I printed both out and highlighted them in different colors. Nothing matched the gap. The breakthrough came when I stopped looking for the missing transaction and started dividing $43.50 by common numbers. $43.50 divided by 2 is $21.75. I scanned for $21.75 and found it—a recurring subscription payment I'd recorded twice. Once as $21.75 and again as $21.75 on the same day. The worksheet would have caught this immediately if I'd been tracking duplicates systematically instead of assuming every entry was unique.
That changed how I work forever. Now I flag duplicate dates and similar amounts before I even start the balance calculation.
Counter-Intuitive Things Beginners Miss
People assume that if their checkbook says they have money, they have money. They don't account for pending transactions that haven't cleared yet. A debit card purchase from Tuesday might not post until Thursday. The money leaves your account on the bank's timeline, not yours. This is the number one source of errors in personal reconciliation. Another thing nobody warns you about: automated payments. A direct deposit from your employer might show up on the statement before your payroll system updates your records. Or a utility autopay might pull the funds on the 28th of the month instead of the 1st because the bank shifted it. These timing differences create gaps that look like errors but aren't. Track the posting date, not just the transaction date.
How to Build the Worksheet
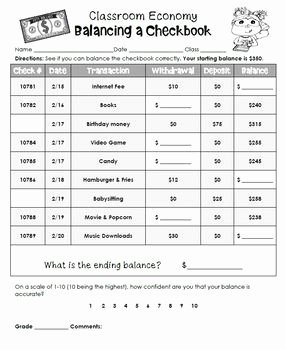
You don't need fancy software. A simple spreadsheet with these columns works fine: Date | Description | Check/Debit Amount | Credit/Deposit Amount | Running Balance Set up two sections. The top section is your bank statement with adjustments. The bottom section is your checkbook register with adjustments. Both should arrive at the same adjusted balance.
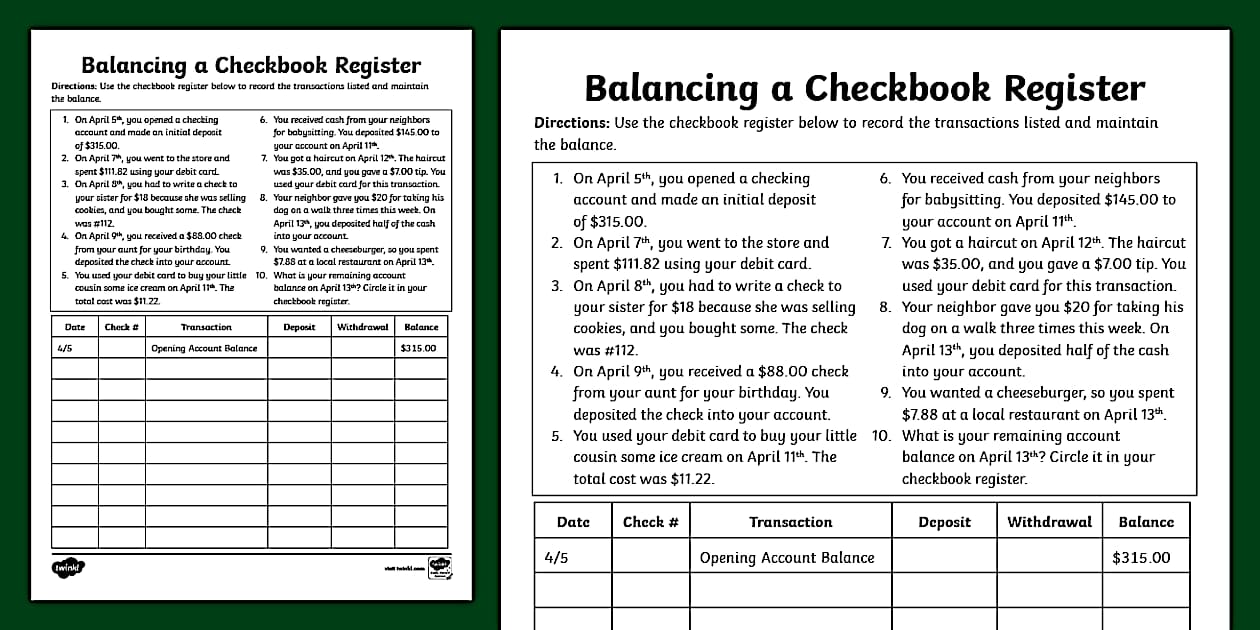
If you want something more complete, search for a Balancing A Checkbook Worksheet template online. There are free versions that include all the standard adjustment categories. The Microsoft Excel gallery has one that's been around for years. Google Sheets has a similar version. Any of those will save you the setup time.
The Limitations Nobody Talks About
This method assumes your records are mostly accurate. If you've been careless about recording transactions for months, the worksheet becomes a detective job rather than a reconciliation tool. You'll spend more time hunting for old errors than actually balancing anything. In that case, start fresh with a clean spreadsheet and only carry forward the current balance. Don't try to fix a year of messy entries while also reconciling the current month. Another limitation: the worksheet doesn't help with fraud. If someone ran a fake check through your account, the numbers will still balance because the fraud is already embedded in the statement. You won't catch that through reconciliation. You catch that by reviewing statements carefully, line by line, regardless of whether they match. For high-volume accounts with hundreds of transactions per month, a manual worksheet becomes impractical. I'd recommend dedicated reconciliation software in that case. Tools like QuickBooks or even Xero handle this automatically and flag mismatches without making you do the arithmetic yourself. The manual method is fine for personal accounts or small business accounts with under fifty transactions a month.
Quick Reference: Common Adjustment Categories
Deposits in transit: Money you deposited that hasn't appeared on the statement yet. Outstanding checks: Checks you wrote that haven't been cashed or deposited. Bank service charges: Monthly fees, wire fees, overdraft fees. Always appears on the statement before you record it.

Interest earned: Usually small, sometimes overlooked entirely. NSF fees: If a check bounced, the fee shows up on the statement. Make sure you record both the original check reversal and the fee. Errors by the bank: Rare but documented. If you find one, note it and contact the bank in writing. Don't just adjust and move on.
Errors by you: More common than bank errors. Wrong amount entered, transaction recorded twice, a check number skipped. These are the ones that keep you up at night. When the two adjusted balances finally match, don't just close the spreadsheet. Write the date and the reconciled balance at the bottom as a checkpoint. Next month, you'll reference this number. If the next statement doesn't pick up where you left off, you'll know immediately that something got lost in the transition. That's the part most guides skip. The handoff between months matters more than the reconciliation itself.

