Why Nobody Tells You That Reconciliation Is Mostly Pattern Recognition
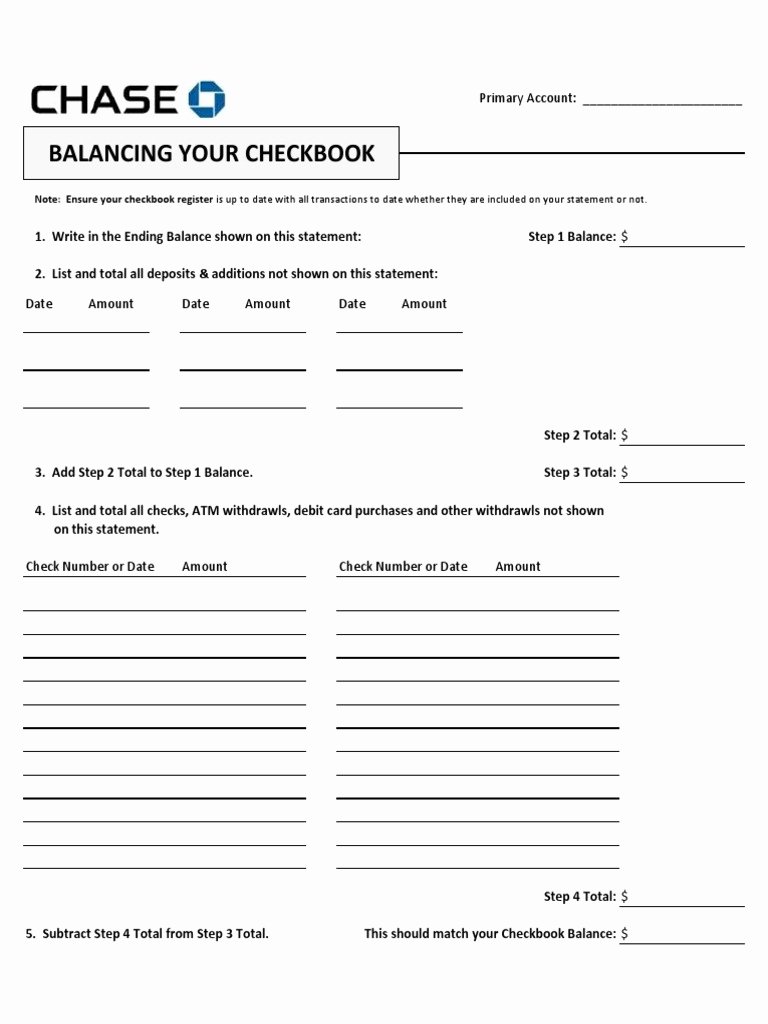
You open your bank statement, you open your check register or your spreadsheet, and you look for where the numbers diverge. That is the entire exercise. The worksheet itself is just a structured place to record what you find. I used to do this by hand on paper for years before switching to a spreadsheet, and honestly, the tool matters less than the discipline of how you approach it. Set up three columns. On the left side, list every transaction from your own records — deposits, withdrawals, checks written, automatic payments, anything that moved money. In the middle column, list the matching transactions from your bank statement. The right column is for notes about discrepancies. You work in chronological order by date, not by dollar amount, because matching by date catches most problems immediately. Here is the practical workflow. Print or pull up your bank statement for the full month. Open your personal ledger — whether that is a spreadsheet, an app export, or a physical notebook. Start at the top. Tick off each line item as you find its match. If a transaction from your records does not appear on the bank statement, mark it as outstanding. If the bank shows something you did not record, mark it as unrecorded and investigate. When both lists are fully reconciled, the ending balance on your worksheet should equal the bank statement balance minus outstanding deposits plus outstanding checks. If it does not, you have a difference to hunt down.
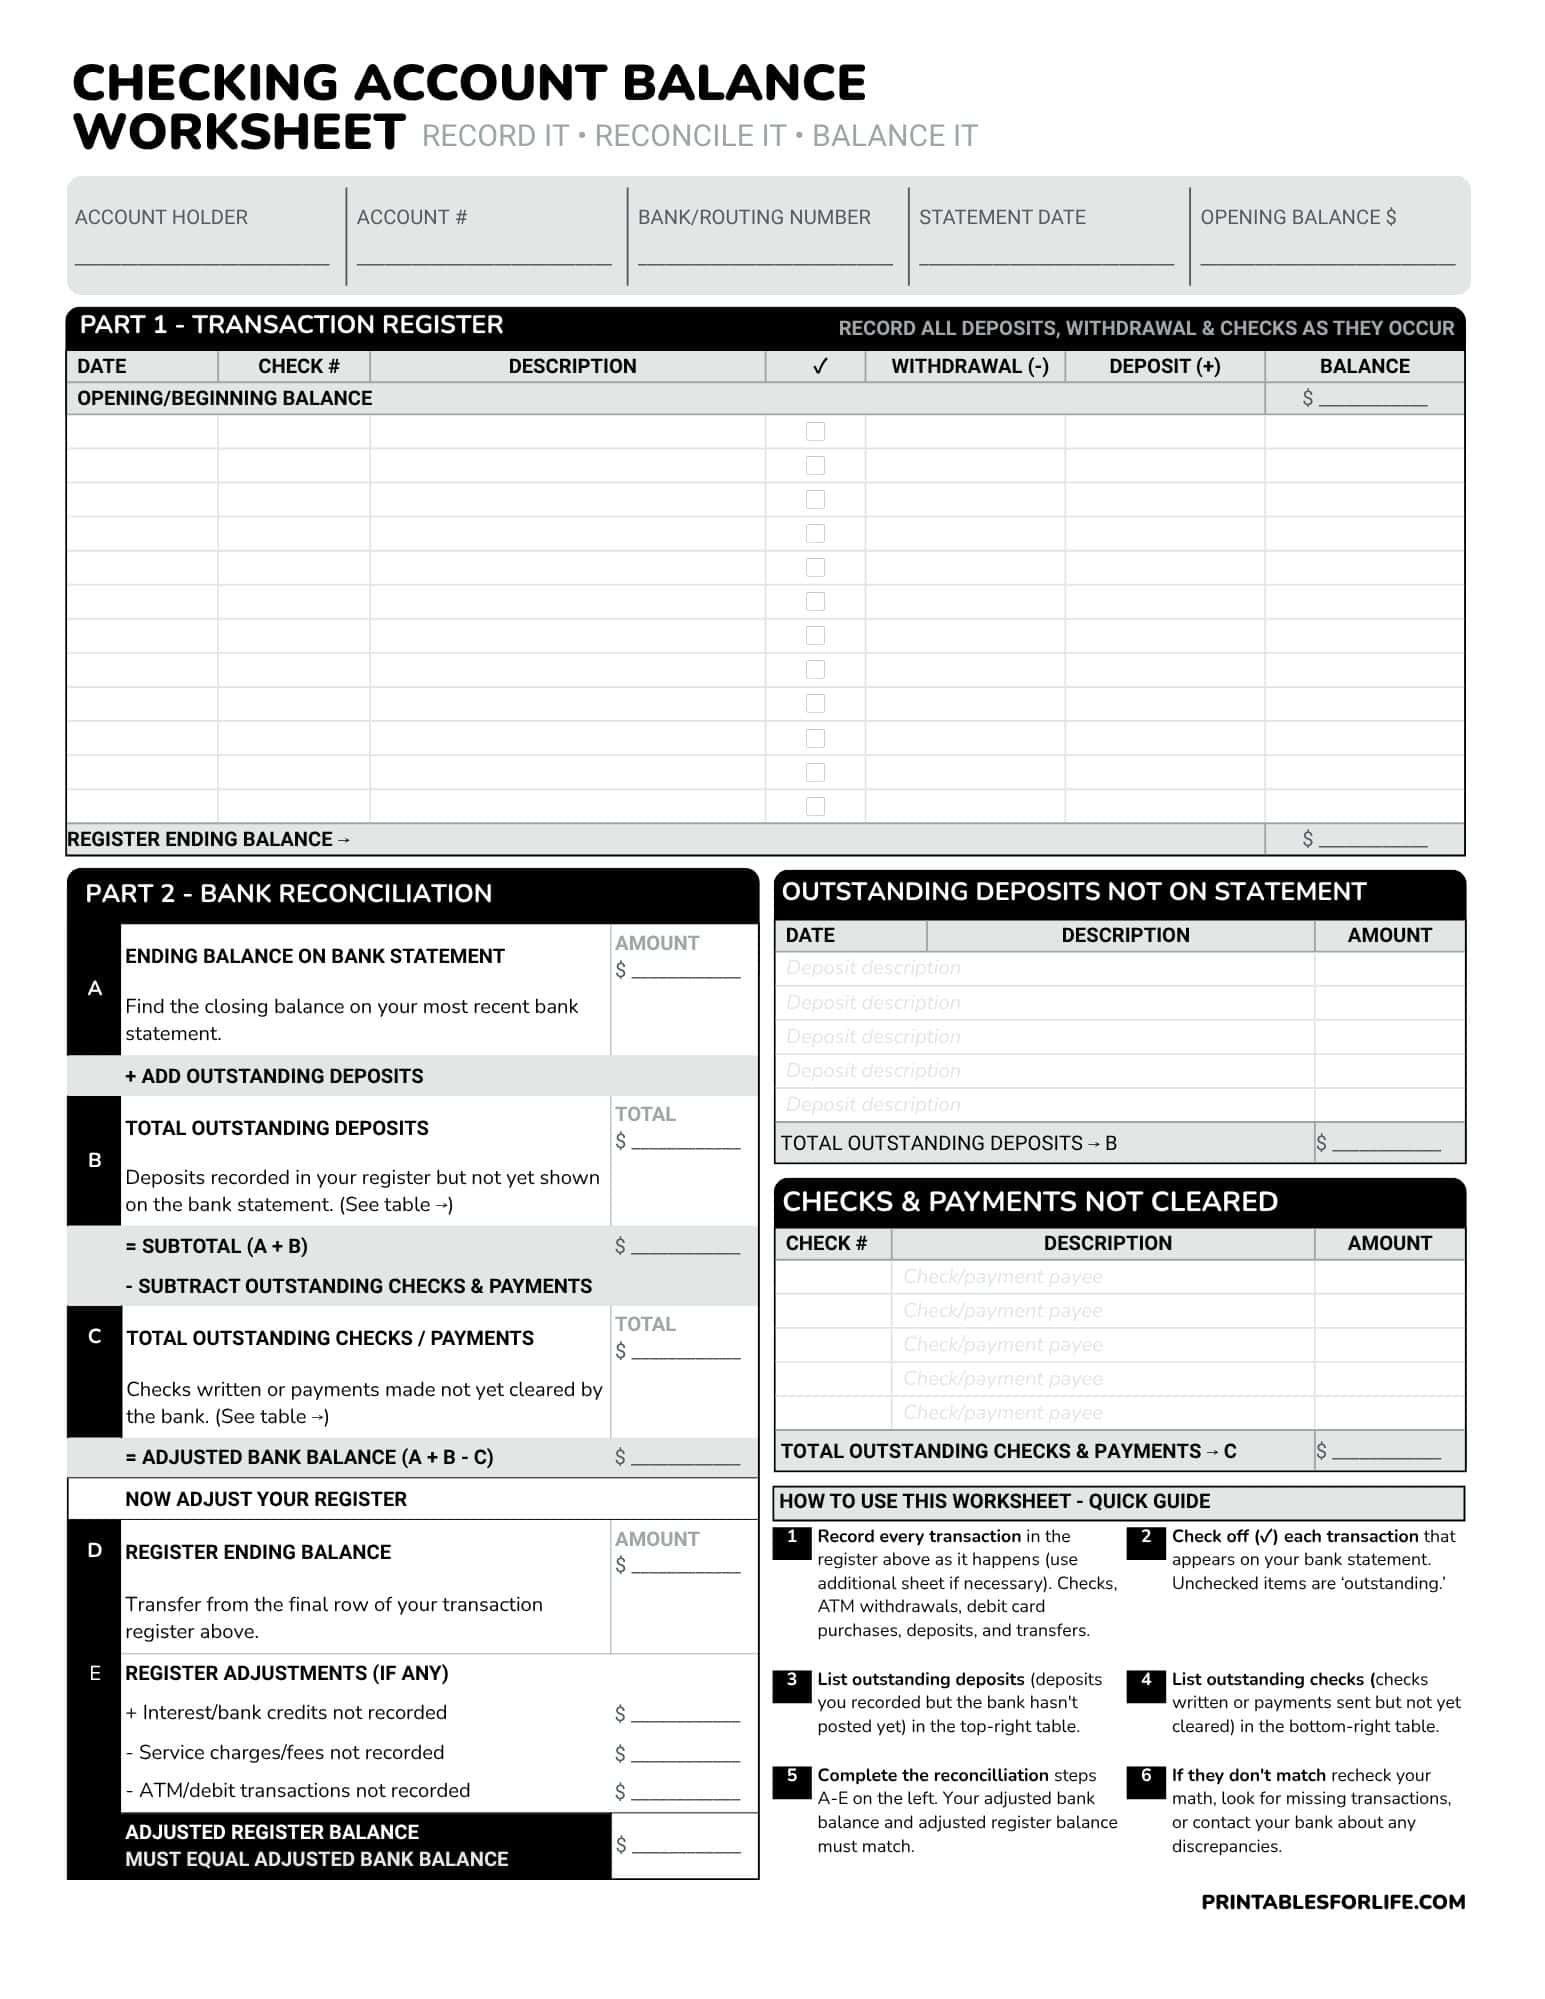
The difference usually comes down to one of three things. A transposition error, where you typed $54.30 instead of $45.30. A missing transaction, usually a bank fee or interest payment you did not enter. Or a duplicate entry, which happens more often than you would expect when you are manually entering data at the end of the month. I ran into a specific problem a few years ago that took me two full evenings to resolve. I was reconciling a checking account where the discrepancy was exactly $4.50. I had gone through the entire statement three times. Nothing. The bank said their balance was correct. My records said mine were correct. The difference kept pointing at a service charge I had marked as paid but never actually entered into my ledger. The bank statement listed it as "Monthly Maintenance Fee" and I had skimmed past it because I thought I already recorded it from a previous month. The workaround was embarrassingly simple: I stopped trying to make the numbers match and instead listed every single line item from the bank statement vertically against my ledger, forcing myself to read each description aloud. That is when I caught it. Reading transactions out loud sounds ridiculous but it breaks the pattern-matching shortcut your brain takes when you scan quickly. For anyone doing this regularly, I recommend building the worksheet in a spreadsheet rather than on paper. Paper works fine for a one-time reconciliation, but once you have recurring accounts, a spreadsheet lets you carry forward outstanding items month to month without re-entering everything. A basic template needs these sections: beginning balance, deposit column, withdrawal column, bank statement balance, bank fees and interest, outstanding deposits, outstanding checks, and the final reconciled balance. Add a column for the date you reconciled it and the name of the statement you used. That audit trail saves you when the bank calls six months later saying a check you thought cleared never actually did.
The counter-intuitive part that beginners miss is that you do not need to reconcile to the exact penny every single month if your volume is low. What matters is catching systematic errors early. A $0.01 difference is almost always a rounding issue from interest calculations or foreign transaction fees. A $0.xx difference where xx is a common number like 25 or 50 is usually a transposition. A large unexplained difference is either a missing transaction or a duplicated entry. Learning to categorize the size of your discrepancy tells you where to look before you spend thirty minutes scanning line items. There is also the matter of timing differences that the worksheet alone cannot resolve. Electronic payments, direct deposits, and ATM withdrawals often show up on different dates in your records versus the bank statement. The worksheet will flag these as discrepancies even though they are legitimate. The fix is to add a date column next to each entry so you can see whether a transaction simply has not posted yet rather than being an actual error. This is especially relevant with mobile deposit checks, which can sit in "pending" status for two to three business days depending on your bank's policy. Here is a limitation I need to be straight about. A Balancing A Checking Account Worksheet only works if you are actually recording your transactions promptly. If you wait until the end of the month to enter thirty transactions from memory, the worksheet becomes a guessing game rather than a verification tool. The method assumes your personal records are already reasonably accurate. It does not fix bad habits, it only exposes them. If you typically write off $20 discrepancies as "probably just fees," you are not balancing anything. You are pretending.
Get the Full Details

For people who manage multiple accounts or have complex finances, the spreadsheet approach scales well but requires consistent naming conventions. If you label one entry as "Starbucks" and another as "coffee shop purchase" for the same merchant, you will waste time searching for duplicates that are not actually duplicates. Use the exact merchant name as it appears on your bank statement. It takes longer upfront and saves twenty minutes of cross-referencing later. If your account activity is high — more than fifty transactions per month — or if you have linked savings accounts, investment withdrawals, and frequent international transactions, a dedicated reconciliation tool or accounting software like QuickBooks or even a purpose-built budgeting app will compress the process significantly. The manual worksheet is still valuable as a monthly sanity check regardless of what software you use, but expecting it to handle heavy volume efficiently is unrealistic.
What the Worksheet Actually Looks Like in Practice
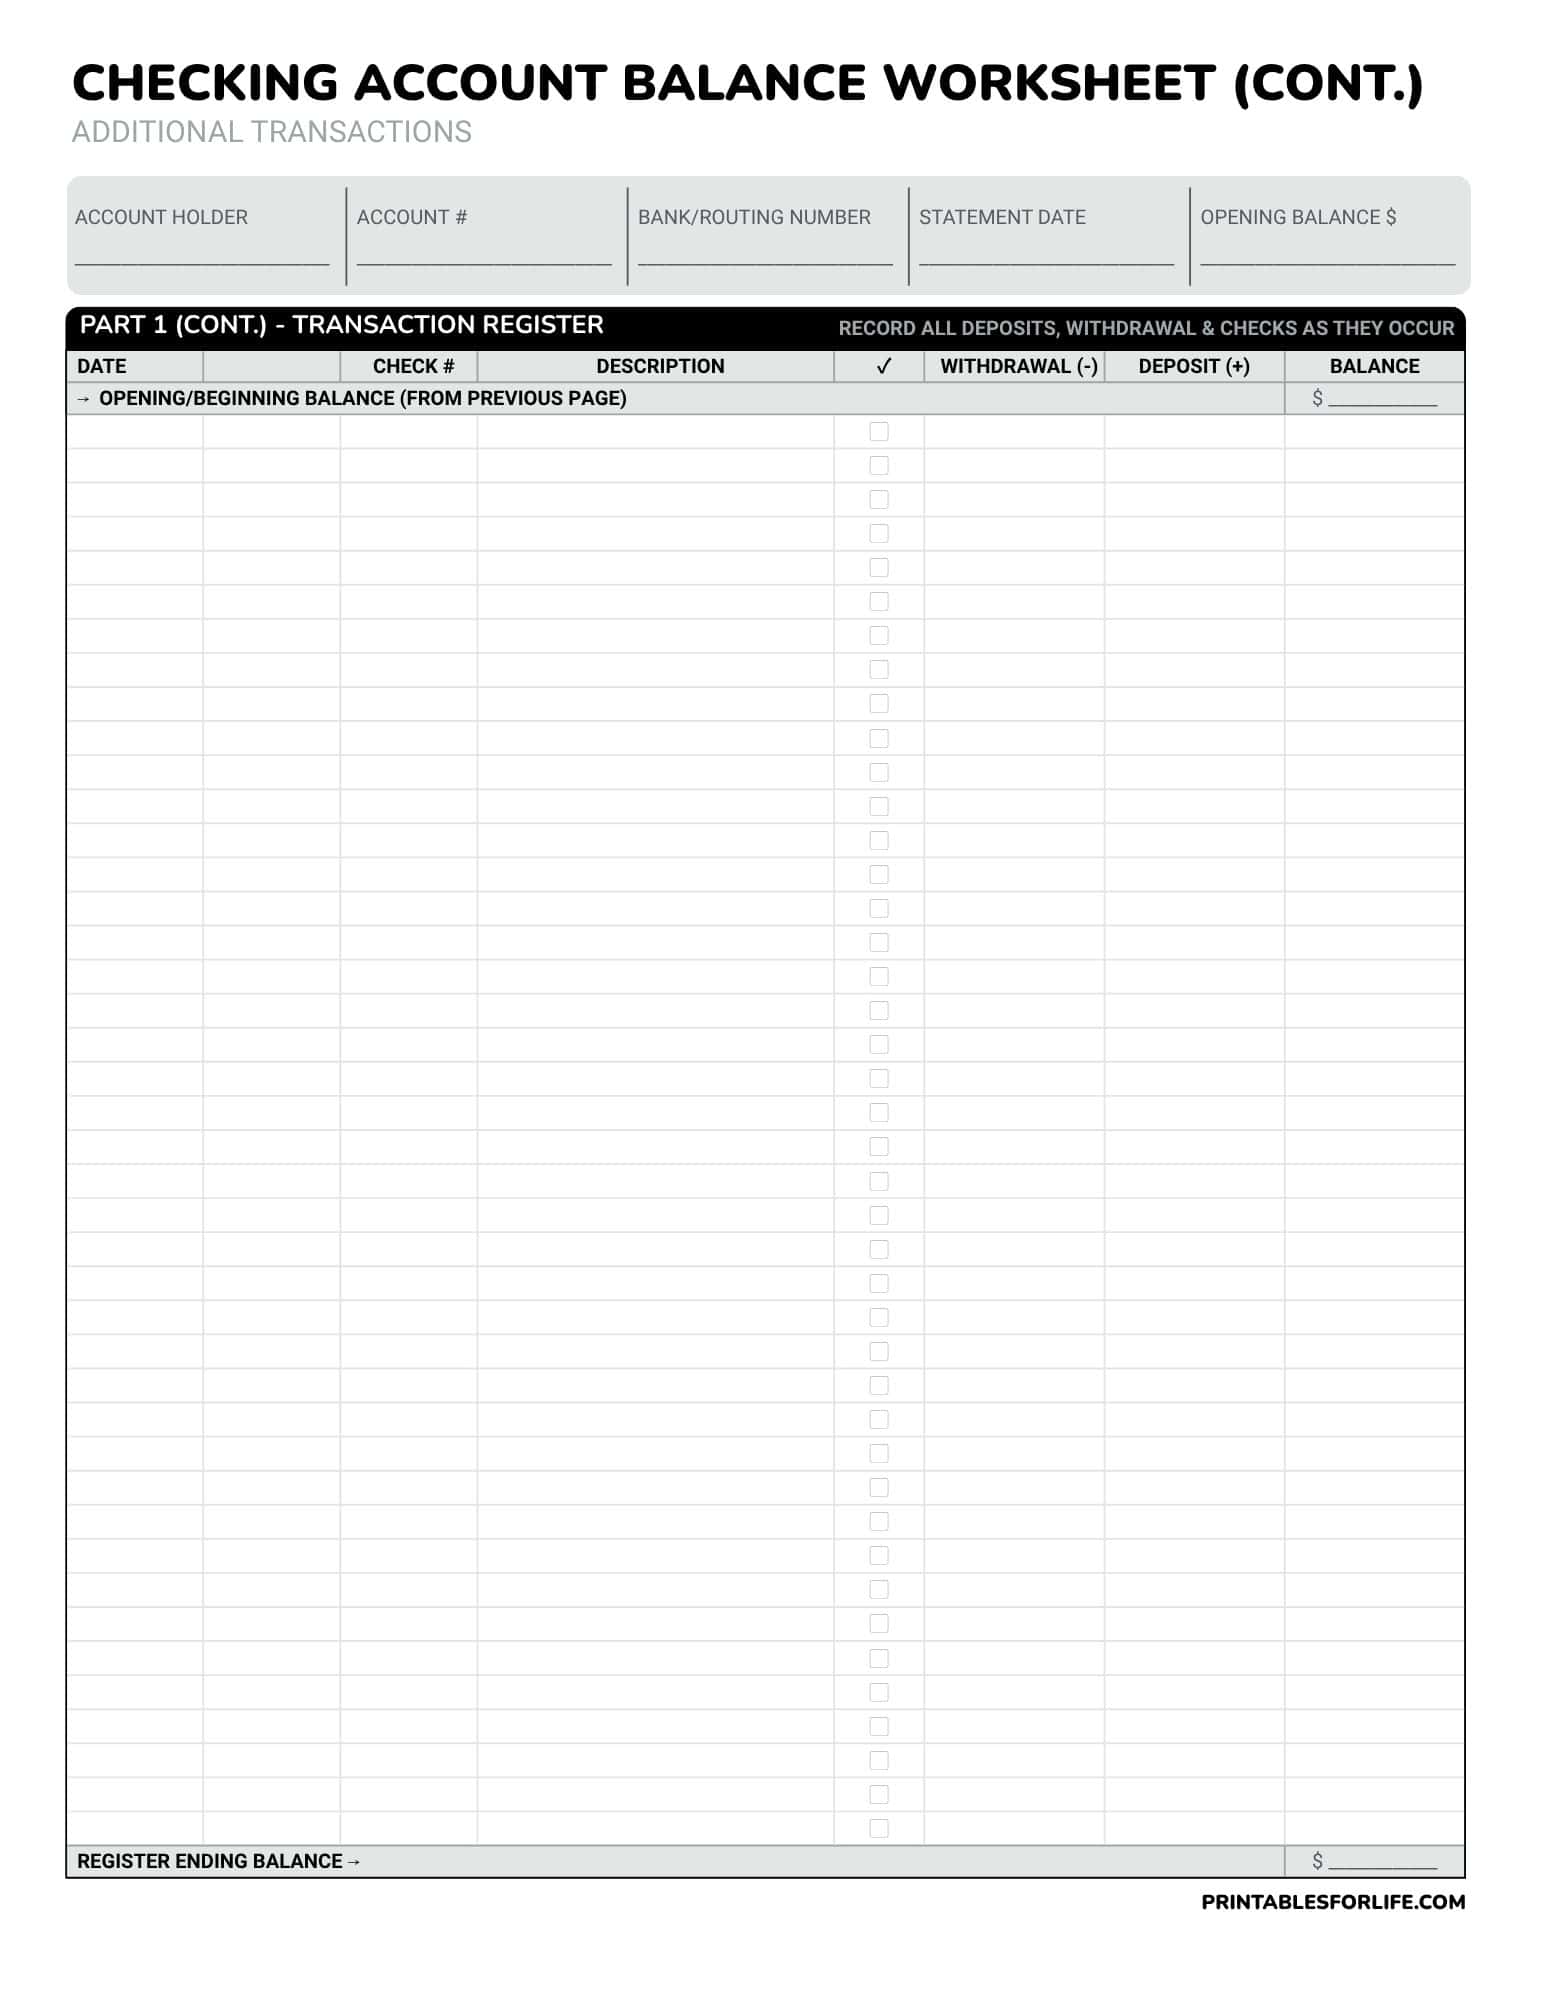
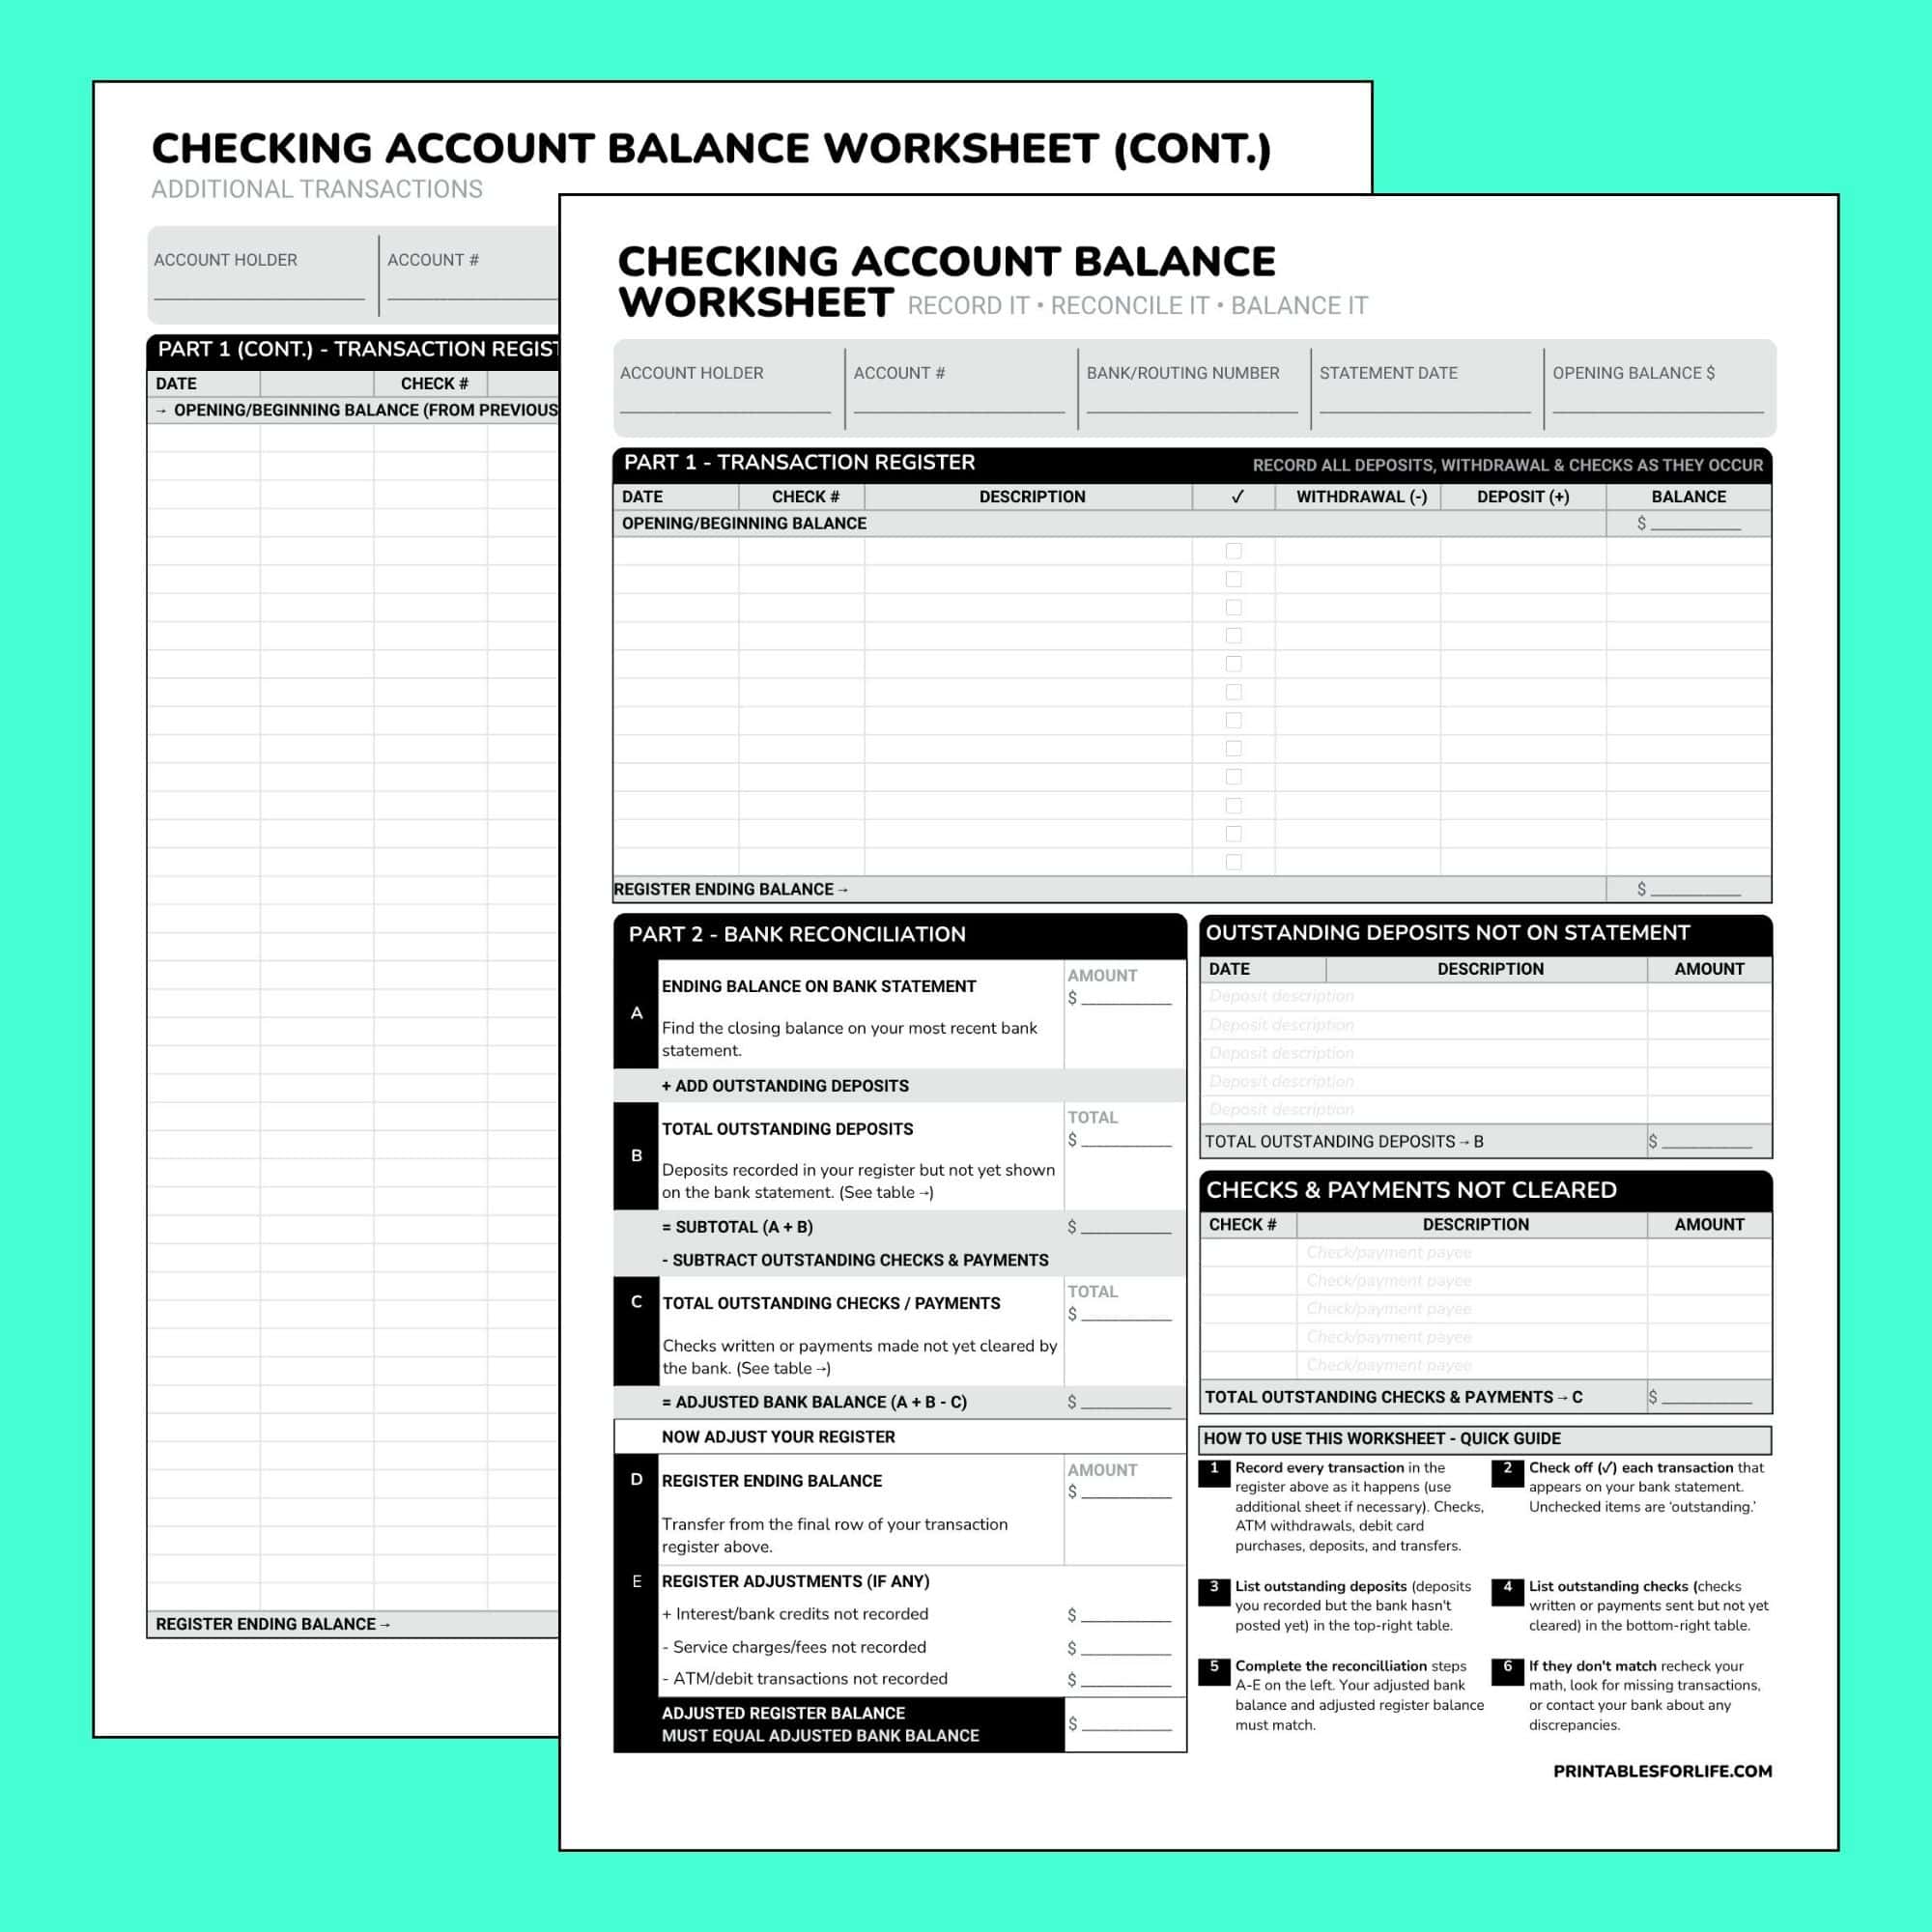
The structure is straightforward. Your beginning balance goes at the top. Below that, list all deposits with their dates and amounts. Then list all withdrawals in the same format. On the bank statement side, you do the same thing but using the official numbers from your bank. The reconciliation section adjusts both sides for outstanding items until they converge on the same number. That convergence is the point of the entire exercise. Downloadable templates exist everywhere, but the simplest version is just a blank spreadsheet with those sections labeled. Do not overcomplicate it with conditional formatting or macros in your first attempt. You need to understand the mechanics manually before automation becomes useful. I have seen people spend more time building an elaborate spreadsheet template than they would have spent reconciling by hand three times. The goal is to get to the answer, not to build a product. One last thing that is not obvious. Keep your reconciled worksheets for at least a year. Banks routinely make errors, and fraud does not respect your monthly cycle. Having a paper trail of every reconciliation you have ever done is the single most useful thing you can produce if you ever need to dispute a charge, request a fee reversal, or prove to an auditor that your records were accurate at a given point in time. I lost a statement once and had to reconstruct a full year of transactions from my own records to prove a $400 error to my bank. The worksheet was the only thing that held up under scrutiny.