What a Balloon Loan Actually Is
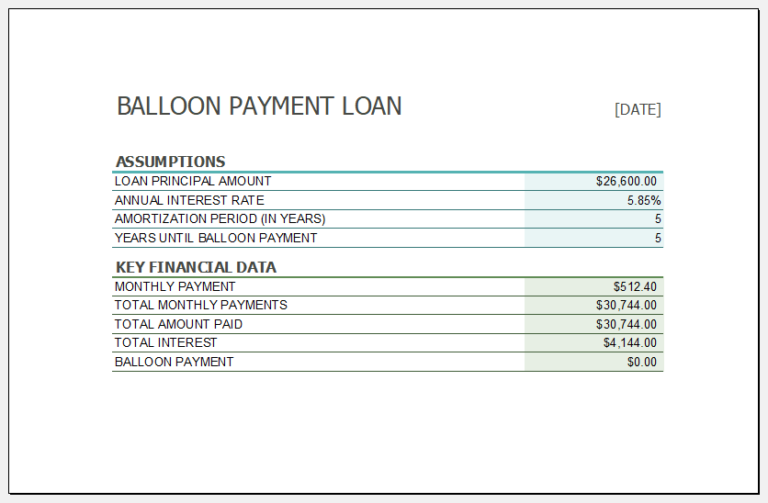
A balloon loan is a mortgage or auto loan where you make small payments for a set period, then owe one giant lump sum at the end. Most people use a Balloon Loan Calculator to figure out what that final payment will look like, because guessing with your eyes closed is how you lose your house or your truck. You need four numbers: the principal amount, the annual interest rate, the length of the balloon period, and the amortization schedule the lender is actually using. Input those into a calculator and it spits out your monthly payment and the remaining balance at the end of the term. That remaining balance is your balloon payment. I spent six years doing loan modifications and underwriting before I moved to consulting. The first time I saw someone hand me a balloon calculator output without checking the amortization assumption, I nearly threw the paper at the wall. Here is why that matters and how to not mess it up.
The Math Behind It
The monthly payment is calculated using the standard amortization formula. But the key detail most people skip is that the amortization period can be longer than the balloon term. For example, you might have a 7-year balloon on a loan amortized over 30 years. The calculator needs to know both numbers. If you only input the balloon period as the loan term, the monthly payment will be wildly inflated and the balloon figure will be meaningless. The payment gets computed as if the loan pays itself off in 7 years, which it does not. The remaining balance then becomes some impossible number because you never actually planned to amortize over the short window. I worked on a commercial real estate deal once where the borrower used a free online calculator that assumed the balloon term was the full amortization period. The monthly payment came out $840 higher than it should have been. The borrower thought he could afford it based on that inflated number. The actual payment was lower, which meant the balloon was significantly larger than he projected. He had about $180,000 more due at maturity than he planned for. We restructured the exit strategy three weeks before closing and he lost $12,000 in legal fees and a 45-day extension on the closing date. The deal survived but nobody laughed about it.
What the Calculator Output Means
Your monthly payment stays constant throughout the balloon period. It is based on the full amortization schedule, not just the balloon window. At the end of that window, the remaining principal balance is due in full. That is the balloon. Here is a concrete example. You borrow $350,000 at 6.5% annual interest. The balloon term is 5 years but the amortization is 30 years. The calculator gives you a monthly payment of roughly $2,212. After 60 payments, the remaining balance is about $318,740. That is your balloon. You either pay it, refinance it, or sell the asset. There is no magic. Another example: $200,000 at 7.25% with a 3-year balloon and 25-year amortization. Monthly payment works out to approximately $1,398. The balloon at year 3 is roughly $183,200. Smaller total interest over the life of the loan compared to a fully amortizing 25-year structure, but you still face that large payment at the end.
Get the Full Details
Where These Calculators Break Down
Most free Balloon Loan Calculator tools online make one or more of the following mistakes. They assume the balloon term equals the amortization period. They ignore compound frequency and treat everything as monthly when some loans accrue interest differently. They do not account for prepayments reducing the balance before the balloon date. They also typically ignore fees, escrow, and insurance that are part of the actual monthly obligation. I found a calculator on a real estate forum once that did not adjust for biweekly payments even when the borrower selected that frequency. The balloon came out $6,400 higher than the actual balance. The borrower had been making biweekly payments for two years without realizing the calculator was wrong. He showed up at the balloon date short by that amount and had to pull from a home equity line to cover it. The workaround is simple: verify the output by running the same inputs through a second tool or by building a quick amortization schedule in a spreadsheet.
Practical Workarounds
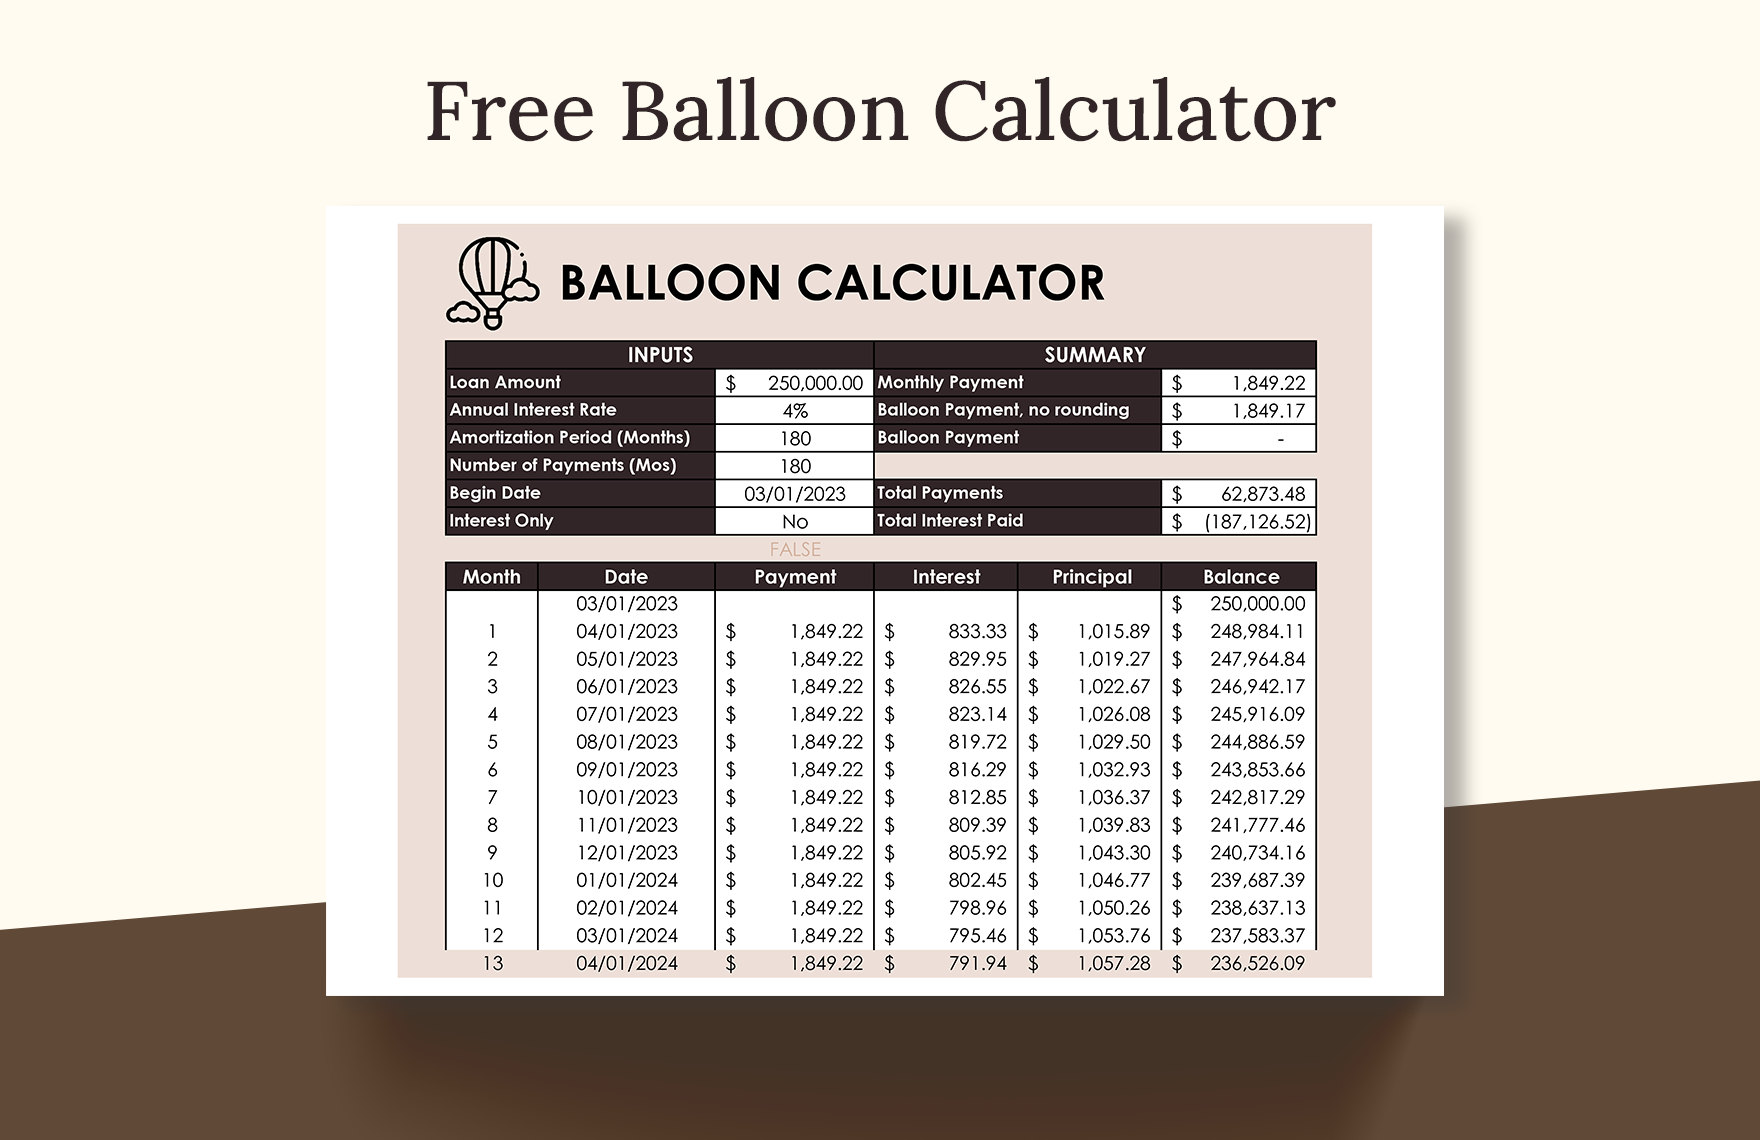
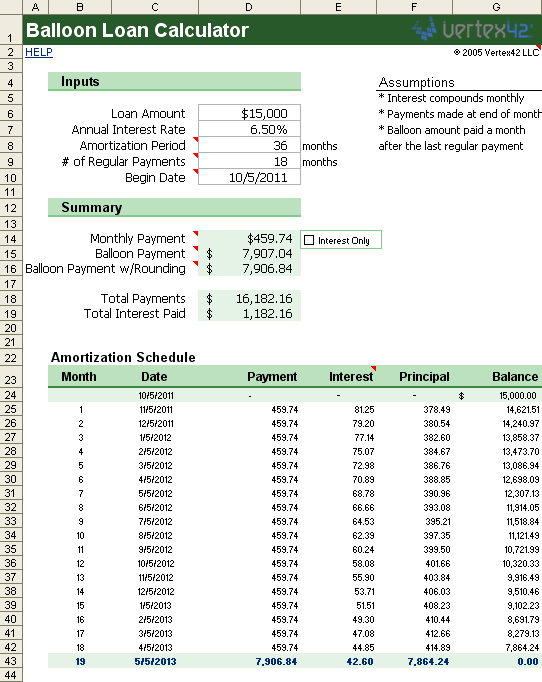
If you want precision, do not trust a single online calculator. Build a spreadsheet. Set up columns for payment number, beginning balance, monthly interest, principal portion, and ending balance. Loop it for the full amortization period. Then read the balance at the balloon date. It takes about ten minutes and you will never second-guess the result. For a downloadable option, many banking institutions and financial sites offer Excel-based balloon loan calculators. Look for ones that let you separate the balloon term from the amortization term. That distinction is the single most important setting in the entire tool. If the file forces you to pick one term, it is not built for balloon loans properly.
When a Balloon Loan Makes Sense
It makes sense when you have a clear exit strategy and confidence in your ability to execute it. A developer might take a balloon loan to build a property, sell it within three years, and pay off the balloon with the sale proceeds. The monthly payments are lower than a traditional loan because the amortization is stretched out. You save on carrying costs during the development phase. It also makes sense for businesses with predictable cash flow spikes. A seasonal business might structure payments around its peak revenue months and plan the balloon payment during its strongest quarter. The lender likes it too in some cases because it reduces their long-term exposure. But the lender is not doing you a favor. They are managing their own risk profile.
When It Is a Terrible Idea
If you do not have a defined exit strategy, do not take a balloon loan. Refinancing is not a plan. It is a hope. Markets shift. Credit tightens. Property values drop. The person who says they will refinance at the balloon date is usually the person who ends up selling at a loss or filing for bankruptcy because the refinancing never happens. I saw a portfolio investor take out five balloon loans in 2022 across three states. He calculated each payment with a basic calculator, ignored the difference between balloon term and amortization, and assumed property values would keep rising. By 2024, two of the balloons came due. The refinancing market had tightened considerably. One property had appreciated. The other two had stagnated. He sold one at a break-even price, refinanced the third, and missed payments on the fourth. The fifth he held and paid off from rental income, which worked only because the numbers happened to align that year.
Red Flags to Watch
Watch for lenders who refuse to provide a full amortization schedule before you sign. If they will not show you the payment table, they are either hiding something or they do not understand their own product. Both are bad outcomes. Also watch for prepayment penalties embedded in balloon structures. Some loans charge you a fee if you pay off the balloon early or refinance before a certain date. That fee can be 2 to 5 percent of the outstanding balance. On a $400,000 balloon, that is $8,000 to $20,000 you did not budget for.
A Word on Tax Implications
Interest deductions on balloon loans work the same as traditional loans in most jurisdictions, but the large final payment can create timing issues for cash-basis taxpayers. If you are an individual filing Schedule E or a business on cash accounting, the balloon payment hits your tax year all at once. You can deduct the interest portion, but the principal repayment is not deductible. Make sure your accountant knows the balloon date is coming so they can model the deduction correctly and avoid a surprise tax bill.
Bottom Line
A Balloon Loan Calculator is useful, but only if you feed it the right assumptions and verify the output. The monthly payment, the balloon date, the amortization schedule, and your actual exit plan are all pieces of the same puzzle. Miss one and the picture does not add up. Use a spreadsheet to double-check any online tool. Know your exit strategy before you sign anything. And do not treat refinancing as a plan unless you have already spoken to a lender about it in writing.