What You're Actually Looking At
A balloon loan is a mortgage or auto loan where the monthly payments are calculated as if the loan will be fully paid off over a long term — say 30 years — but the entire remaining balance comes due much sooner, usually after 5, 7, or 10 years. The final lump sum is the balloon. The amortization schedule for this type of loan shows you exactly how much principal you've chipped away at each month, and what that looming final payment actually looks like in dollar terms. Most online calculators get this wrong or gloss over the details.How to Build Your Own Balloon Loan Calculator Amortization Schedule
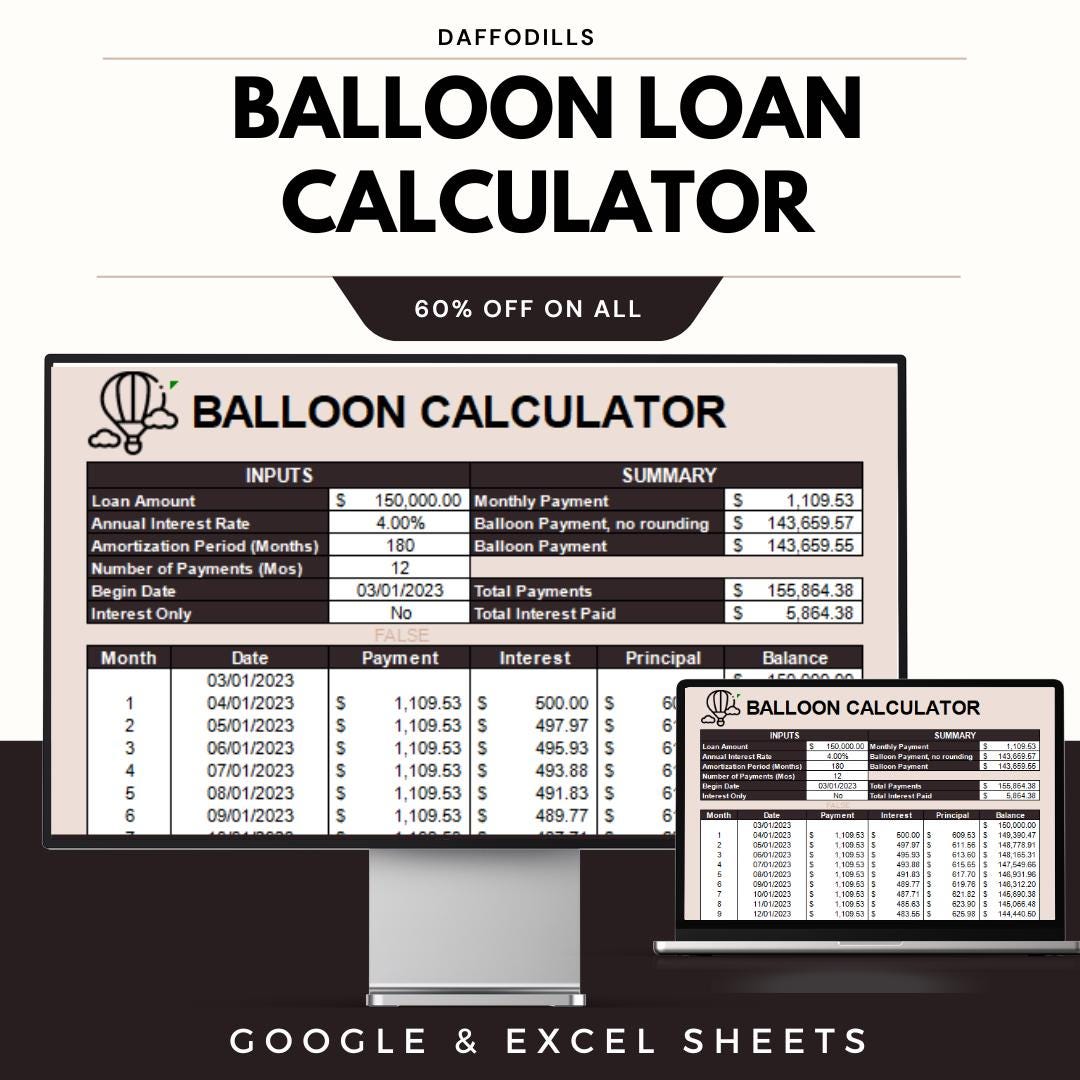
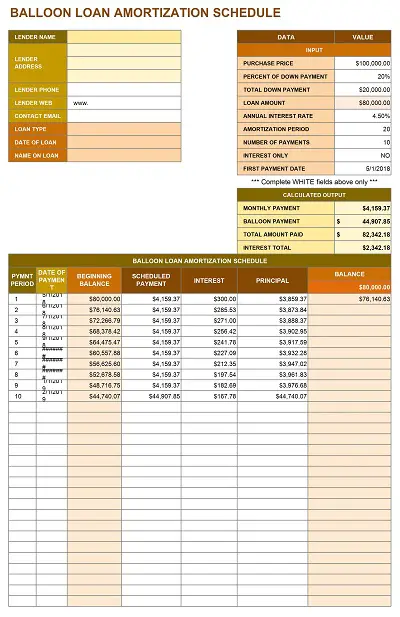
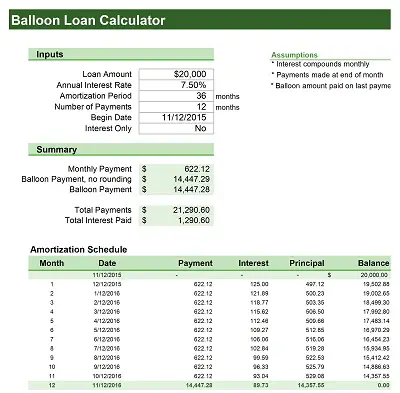
The spreadsheet approach is faster and more accurate than most web-based tools once you've set it up. Here is the practical method I use, and have used for probably six years across different brokerage environments. Start with five inputs: the original loan amount, the annual interest rate, the total amortization period in months, the balloon date in months, and whether payments are made at the beginning or end of each period. End of period is standard. Put these in cells B1 through B5. In column A, list month numbers starting at 1 and going down to the total amortization period. For each row, calculate the monthly interest rate by dividing the annual rate by 12. Then use the PMT function to find the regular monthly payment based on the full amortization period, not the balloon date. That is the part most people mess up. The payment stays the same throughout, but the balloon date determines when the remaining balance gets dumped on you. For the balance calculation, use the CUMPRINC function or build a running balance column. Start with the original loan amount. Subtract the principal portion of each payment. The principal portion equals the total payment minus the interest portion, where interest is the previous balance multiplied by the monthly rate. Keep going month by month until you hit the balloon date. The remaining balance at that point is your balloon payment. I had a situation last year where a client's balloon loan was structured with daily compounding instead of monthly compounding, which threw off every standard calculator by about two hundred dollars per month. The workaround was simple but not obvious — I switched to using the EFFECT and NOMINAL functions to convert the daily rate into an equivalent monthly rate before plugging it into the payment formula. Saved me from having to rebuild the whole schedule from scratch.A few things most people miss.
The amortization schedule does not change just because the loan balloons early. The payment amount stays identical. What changes is your equity position and the final balance you need to refinance or sell to cover. Many borrowers confuse the two and think a smaller balloon term means smaller monthly payments. It does not. The payment is locked to the full amortization period. Another counter-intuitive point: prepaying a balloon loan does not reduce the balloon payment. Since the payment was already calculated to pay off the loan over the full term, throwing extra money at the principal just lowers the remaining balance that eventually becomes the balloon. It helps, but the mechanism is different from a standard fully amortizing loan where extra payments can actually shorten the term.Where these schedules break down.
Web-based balloon loan calculators typically assume a fixed rate and fixed payment. If your loan has an adjustable rate, or if it is a negative amortization loan where the unpaid interest gets added to the principal, most online tools will give you completely wrong numbers. In those cases, you need a custom spreadsheet or a dedicated financial modeling tool. I have seen brokers hand clients schedules generated from generic calculators and the balloon payment was off by thousands because the tool ignored the rate adjustment period. Another failure mode: loans with payment escrows that are not included in the calculator output. Your actual monthly obligation includes taxes and insurance, but the amortization schedule only shows principal and interest. This creates a gap between what people expect to pay and what they actually owe each month. Always cross-reference the P&I payment against your escrow analysis before relying on the schedule for budgeting. If you want something you can download and modify, a properly built Excel file with this structure takes about twenty minutes to set up and runs in about fifteen seconds for a full 360-month amortization. Much faster than clicking through calculator after calculator and trying to reconcile the outputs. The key is getting the PMT function tied to the correct period and making sure the remaining balance formula references the right cell. Get that wrong and the whole schedule is garbage.