How Balloon Amortization Actually Works in Practice
Most people think a balloon payment is just a big lump sum at the end. It isn't. A balloon loan is structured so your monthly payments amortize over 30 years but the loan term itself is only 5 or 7 years. When that term hits, whatever principal remains is due in full. The math is straightforward but the implications are where people get burned.
I spent about three years underwriting commercial real estate loans before moving to residential. The first balloon deal I saw went poorly because the borrower's LTV jumped from 65% to 82% between origination and maturity. They'd refinanced part of the deal without adjusting the amortization schedule, which meant the remaining balance was higher than expected when the balloon came due. We had to work out a modification that extended the term by 18 months and added a small principal deferral. That kind of thing happens more often than you'd think, especially when property values shift unexpectedly or borrowers take on additional debt against the same collateral.
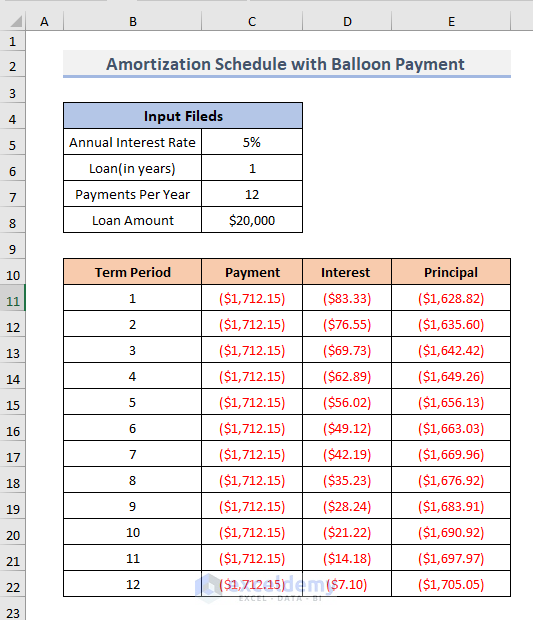
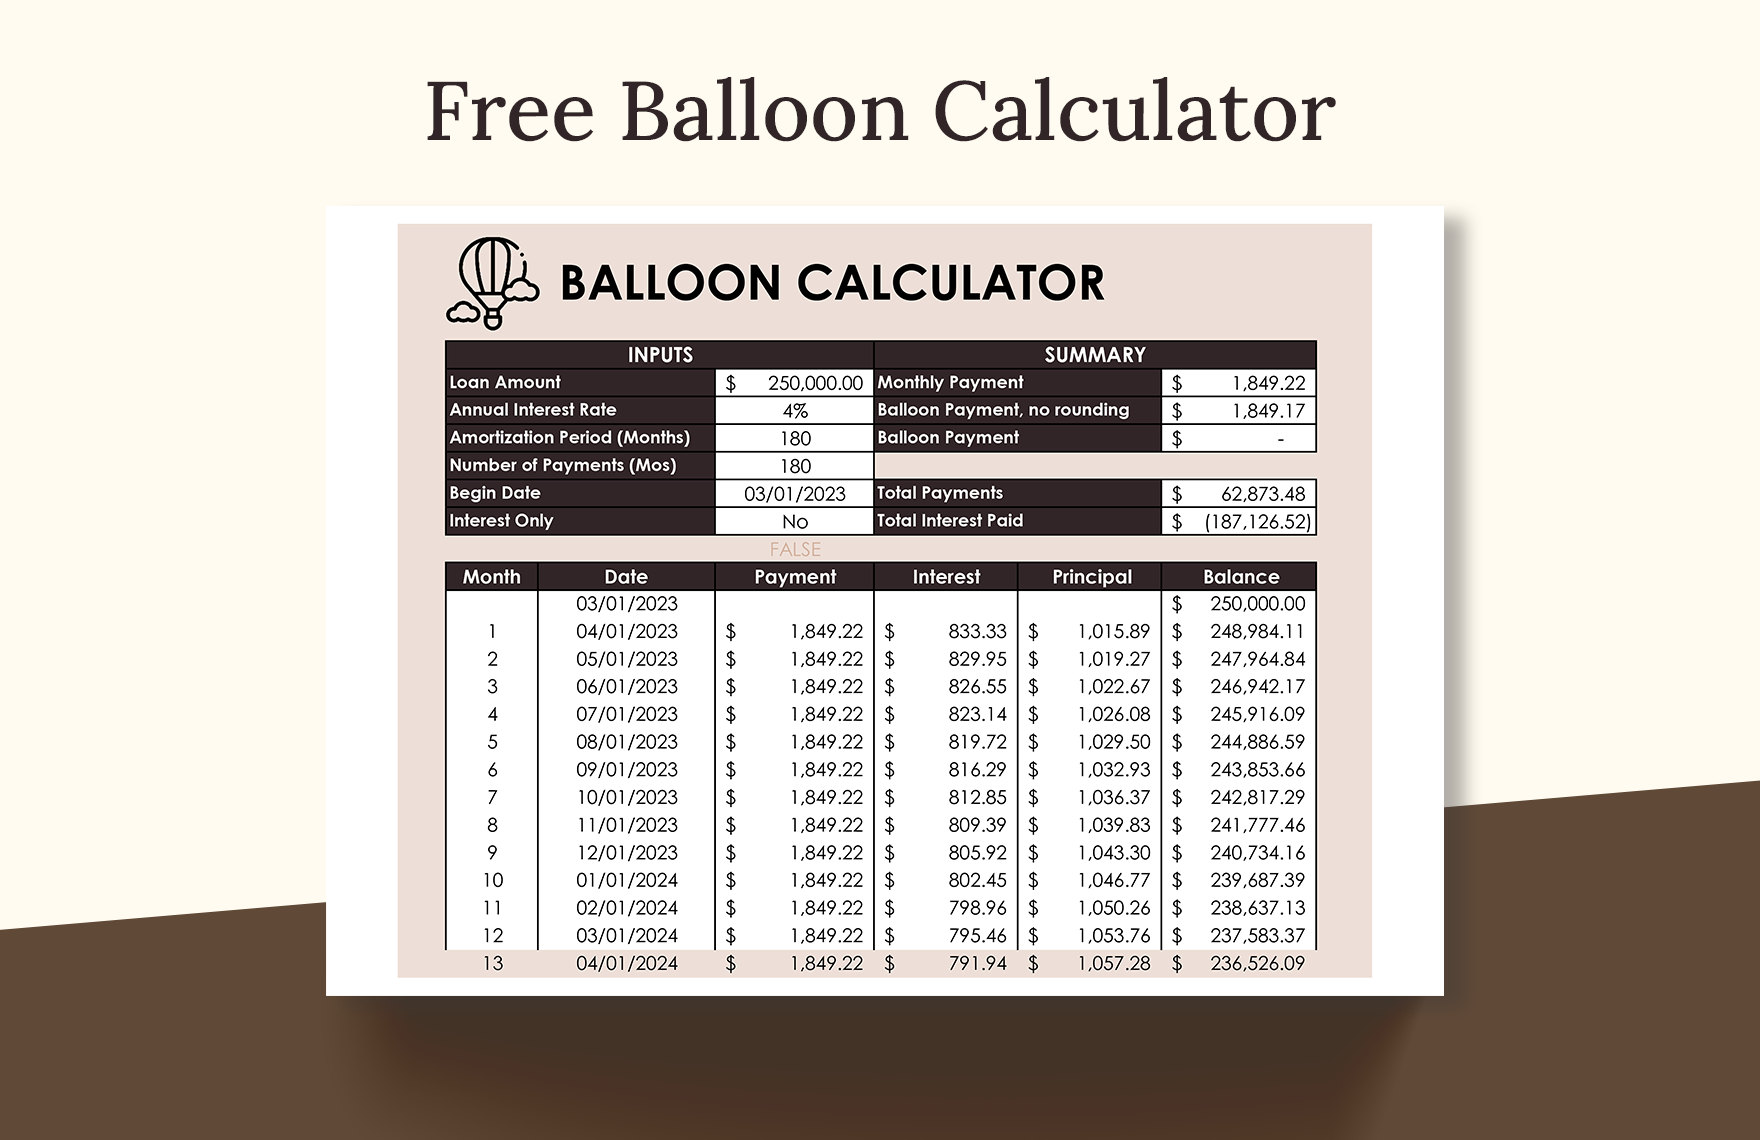
Using a Balloon Mortgage Amortization Schedule Calculator
A proper calculator for this needs to handle three inputs: the full amortization term, the balloon term, and the interest rate. Most online tools get this wrong because they assume the amortization term equals the loan term. With a balloon structure, those numbers are deliberately different.
Enter the loan amount, the stated interest rate, the total amortization period in months, and the actual term length in months. The calculator then computes your monthly payment based on the longer amortization period while tracking how much principal remains at the balloon date. For example, a $400,000 loan at 6.5% with 30-year amortization and a 7-year balloon would show a monthly payment of roughly $2,528 but a remaining balance near $348,000 when year seven arrives.
The formula behind it uses the standard annuity payment calculation: P = r(PV) / [1 - (1+r)^-n], where r is the monthly rate and n is the total number of payment periods. Then the remaining balance at any point is PV × [(1+r)^n - (1+r)^p] / [(1+r)^n - 1], where p is the number of payments already made. These aren't complicated equations but getting them right matters because a single digit error in the rate or term can shift the payoff amount by thousands.
Where People Go Wrong
The biggest mistake I see is assuming the balloon payment equals the original loan amount. It rarely does. Even with interest-only structures, some principal gets paid down during the term. With fully amortizing structures, more gets paid. You need to know exactly what balance remains at the balloon date, not what you borrowed.
Another issue is the prepayment penalty. Many balloon loans carry a yield maintenance clause or a hard prepayment penalty that makes refinancing expensive right when you need to. I had a borrower who planned to sell a property at year five to pay off a seven-year balloon. The seller's market delayed the close by four months. That pushed the payoff into the penalty window and cost them an extra $8,400 in yield maintenance fees. Nobody caught it during underwriting because everyone was focused on whether the borrower could make the monthly payments, not on the refinance mechanics.
When This Structure Makes Sense
Balloon mortgages exist for a reason. They offer lower initial rates than fully amortizing loans because the lender's exposure is shorter. For investors who plan to sell or refinance within the balloon term, that rate difference can mean significant savings during the holding period. The math is clear: a 6.5% balloon at seven years versus a 7.25% fully amortizing loan at thirty years saves roughly $420 per month on a $400,000 loan. Over seven years that's about $35,000 in interest savings before you even factor in the balloon payment itself.
But this only works if you have a realistic exit strategy. I've seen too many borrowers treat the balloon as optional. It isn't. The loan contract requires repayment at maturity regardless of whether you've refinanced, sold, or otherwise arranged payment. Lenders will report the balloon as a demand feature in some cases, which means they can technically call the loan due earlier if your credit deteriorates or the collateral value drops below the required threshold.
Calculator Limitations You Should Know
Most free calculators don't account for monthly compounding adjustments that occur in actual loan servicing. Some use simplified interest calculations that differ from the standard amortization tables used by servicers. The variance is usually small, maybe a few dollars per payment, but it adds up over a seven-year term and can affect the remaining balance calculation enough to matter when you're evaluating whether you can refinance.
I wrote my own spreadsheet tool about five years ago after getting tired of the inaccuracies in commercial mortgage calculators. It handles monthly compounding, tracks the balloon date precisely, and shows you the exact remaining balance with a breakdown of principal versus interest paid each period. It also flags when the remaining balance exceeds typical refinance thresholds based on current LTV guidelines. The tool isn't perfect. It doesn't account for escrow, insurance, or property tax variations that affect actual monthly payments. But for the core amortization math, it's accurate to within a cent on standard loan structures.
What to Look for in a Schedule
A good amortization schedule for a balloon loan shows two distinct phases. The first phase displays regular monthly payments calculated on the full amortization term. The second phase, or the balloon date, shows the remaining principal balance in bold. Some schedules also include a columns for cumulative interest paid, which helps you understand the total cost of borrowing during the term.
Pay attention to the principal reduction rate. In the early years of a loan, most of your payment goes toward interest. With a seven-year balloon on a 30-year amortization schedule, you might only pay down 15-20% of the principal before the balloon comes due. That means roughly 80% of the original loan balance remains. If you're counting on property appreciation to cover that gap, make sure your appreciation assumptions are realistic. National median home price appreciation averages about 3-4% annually over long periods. Short-term fluctuations can be much larger in either direction.
Alternatives to Consider
If the balloon structure feels risky, explore alternatives. An adjustable-rate mortgage with a five-year fix period followed by annual adjustments gives you some of the initial rate benefit without the maturity shock. A shorter fixed-rate loan, like a seven-year or ten-year conventional mortgage, eliminates the balloon entirely even though your payments will be higher. Partially amortizing loans spread the principal repayment more evenly and reduce the final lump sum.
I recommend running scenarios for each option using the same loan amount and term. Compare the total interest paid across all options, not just the monthly payment. Sometimes a slightly higher monthly payment on a fully amortizing loan saves far more over the life of the loan than the initial rate savings on a balloon structure.
Mortgage Amortization Calculator With Balloon at Kevin Davidson blog
Mortgage Amortization Calculator With Balloon at Kevin Davidson blog
Mortgage Amortization Calculator With Balloon at Kevin Davidson blog
Mortgage Amortization Calculator With Balloon at Kevin Davidson blog
Excel Interest Only Amortization Schedule with Balloon Payment Calculator