How balloon payment mortgages actually work and when they make sense
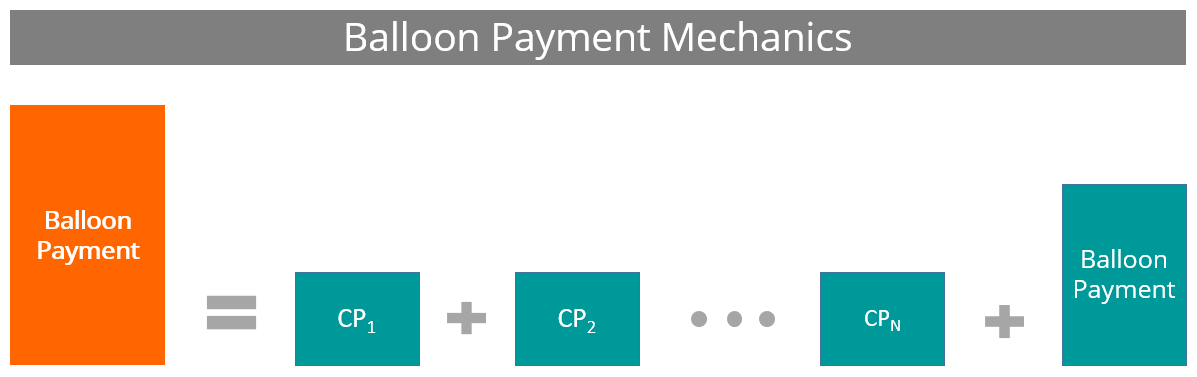
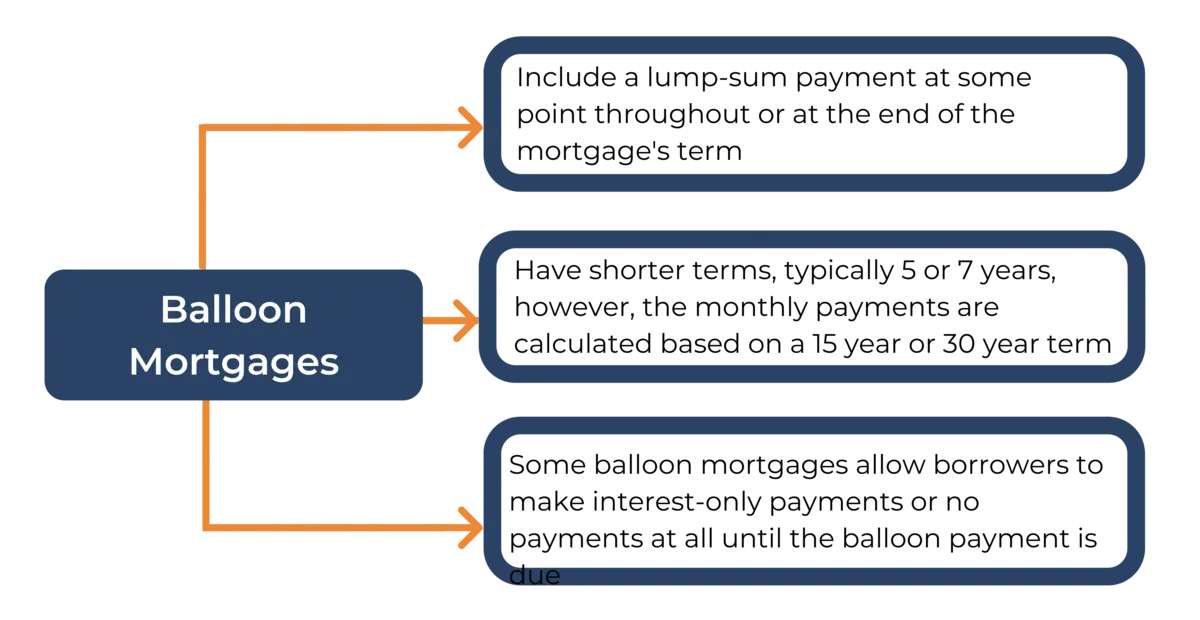
I got my first look at a balloon payment structure back in 2009 when a commercial client walked in asking to refinance a property they'd bought during the boom. They wanted lower monthly payments and were willing to sell the asset before the big payment hit. We structured it as a five-year balloon with amortization over twenty-five years. The borrower made small payments for fifty-nine months, then came back with a lump sum equal to roughly seventy-eight percent of the original principal. It worked because they had a sale contract already in place. Not every deal ends that cleanly. A balloon payment mortgage is a loan where the monthly payments are calculated as if the borrower will repay the full balance over a long period, but the remaining balance comes due all at once on a specific date — usually three to ten years out. The lender prices the loan based on that shorter balloon term, which often means a slightly higher interest rate than a standard thirty-year fixed. You're not getting a cheaper rate by choosing a balloon. In fact, most lenders add a quarter to half a percent to the spread because they want compensation for the refinancing risk they're taking on.
Understanding the Balloon Payment Mortgage structure
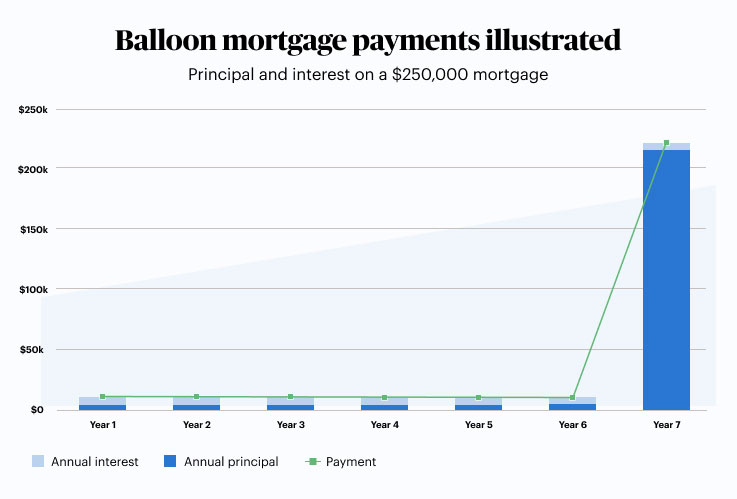
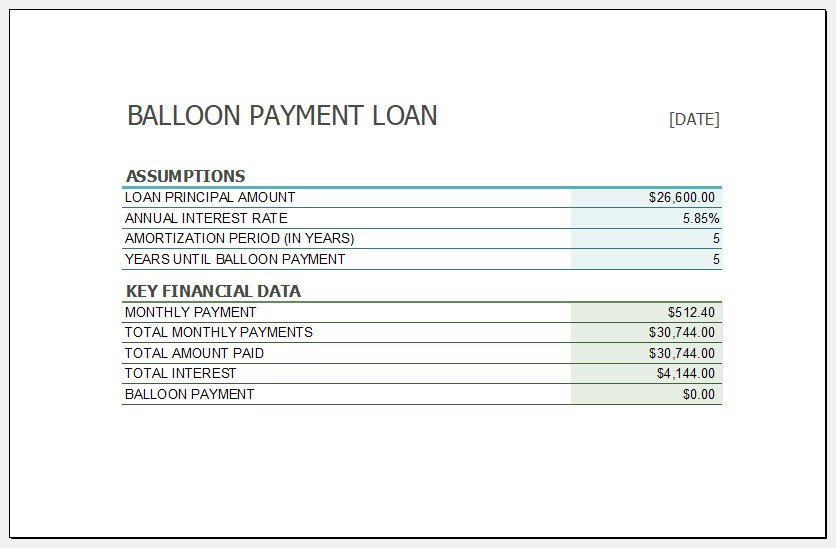
Here's what the numbers look like in practice. Say you borrow five hundred thousand dollars at six percent interest with a seven-year balloon and twenty-five-year amortization. Your monthly payment would be approximately three thousand sixty-eight dollars, which is calculated the same way as a standard fully amortizing loan. After eighty-four payments, the remaining balance comes to roughly four hundred thirty-two thousand dollars. That's the balloon payment. You either pay it in cash, refinance into a new loan, or sell the property. The key detail most people miss is that the monthly payment never includes any principal reduction toward that balloon balance, even though the amortization schedule shows some happening. The lender bills you based on twenty-five years of payments, but only pays you off after seven. The difference between what you owe and what you've paid down is what gets called due all at once. I learned this the hard way with a residential investor back in 2017. She took a balloon mortgage on a duplex in Columbus, Ohio, expecting to refinance after eighteen months once she stabilized the occupancy. The numbers looked fine on paper. Her debt service coverage ratio was solid. She had a letter of credit ready. What she didn't account for was her lender's internal policy change. Three months before her balloon came due, the lender updated its underwriting guidelines and required a minimum credit score of six hundred and eighty for any balloon refinancing. She sat at six hundred and fifty-two. She couldn't refinance with the same lender, and no other bank in the market would touch her at that moment because the local market was already softening. I ended up finding a community development corporation that offered a portfolio loan at seven point two five percent. It covered the gap for six months while she repositioned the property and boosted her credit score. She refinanced out a year later at a conventional rate. That six-month bridge cost her about fourteen thousand dollars in additional interest alone.
This is the real risk of a Balloon Payment Mortgage. The balloon date doesn't care about your circumstances. If you can't refinance or sell by that date, the loan goes into default. The lender can initiate foreclosure proceedings within ninety days in most jurisdictions, depending on state law. You're not just looking at a higher rate. You're looking at losing the asset. There's a nuance with commercial balloon mortgages that almost nobody explains. Some lenders will offer you what they call a "recastable balloon." This means the remaining balance can be amortized at the existing rate if you meet certain criteria before the balloon hits. I've seen borrowers use this feature as a safety valve, but the catch is the criteria are rarely written clearly in the original note. My client in that Columbus deal would have been fine if her original contract had included a recast option tied to occupancy metrics rather than just a clean payment history. The lender had every incentive to describe it vaguely because vague language keeps people from exercising their options. Here's another counter-intuitive point: balloon payments are sometimes easier to qualify for than conventional mortgages, not harder. Lenders evaluate the loan based on the monthly payment, which is lower because it's spread over twenty-five years. Your debt-to-income ratio looks better. But the balloon balance isn't counted as a liability in most underwriting models. This means you can qualify for a larger loan than you would on a standard mortgage, even though you're taking on significantly more risk. I've seen borrowers walk away thinking they qualified for six hundred thousand dollars when the underlying asset was worth four hundred and eighty thousand. The math checks out on paper until the balloon date arrives and the appraised value has dropped eight percent.
Get the Full Details
If you're considering a balloon mortgage, the first thing to do is calculate your exit strategy with realistic numbers, not optimistic ones. Property values don't always go up. Refinancing rates change. Your income situation might shift. I always run the numbers three ways: best case, base case, and stress case. The stress case assumes you can't refinance at all and have to sell the property within six months of the balloon date. If that scenario leaves you underwater, don't take the loan. The alternative for most people is a standard fixed-rate mortgage or an adjustable-rate mortgage with a five-year cap. These have higher monthly payments but no surprise liability waiting at the end. A five-hundred-thousand-dollar fixed loan at six percent for thirty years costs about two thousand nine hundred and seventy-eight dollars per month. Your balloon payment version cost three thousand sixty-eight per month, but you owe four hundred and thirty-two thousand dollars at year seven. The difference isn't just the payment. It's the existential risk of not having a way out. One final thing that catches people off guard. Balloon payment mortgages often come with prepayment penalties that are unusually steep. I've seen penalties structured as sixty percent of the remaining balance if you pay off early in years one and two, dropping to forty percent in year three and twenty percent in year four. If your exit strategy involves selling the property rather than refinancing, make sure you understand whether the prepayment penalty applies to a sale proceeds payoff or only to a voluntary refinance. Most standard prepayment clauses cover both, but some balloon-specific contracts carve out sales. Read the actual document, not the summary sheet the loan officer handed you.