Understanding Baloon Payment Calculator
Most people think payment calculators just crunch numbers and spit out a result. The reality is messier than that. You spend ten minutes entering loan terms only to realize the monthly figure doesn't account for the compounding schedule your bank actually uses. I learned this the hard way a few years back when I was reviewing a client's balloon payment schedule and the calculator gave me a number that was $47 off per month compared to what their amortization table showed. A balloon payment calculator is essentially a specialized amortization tool. You input the principal, the interest rate, the total loan term, and then specify how many months or years into that term the balloon payment is due. The result shows you the regular monthly payments leading up to that final large lump sum. Here is the thing nobody tells you. Most online calculators assume payments are calculated on a standard monthly compounding basis. But some lenders use daily compounding or have biweekly payment structures. When I was working on a commercial real estate deal, I found that a standard Baloon Payment Calculator gave me a monthly payment of $8,420, but the lender's actual amortization schedule showed $8,513. That $93 difference accumulated to over $2,200 extra paid by the borrower over the life of the loan before the balloon came due.
The workaround I ended up using was to take the calculator's output and then manually verify it against the actual amortization formula: divide the annual rate by 365 for daily compounding, multiply by the days in each month, and apply it to the remaining principal. It took me about 20 minutes to set up a spreadsheet that did this automatically, which saved me from making similar errors on every subsequent deal.
How to Use It Properly
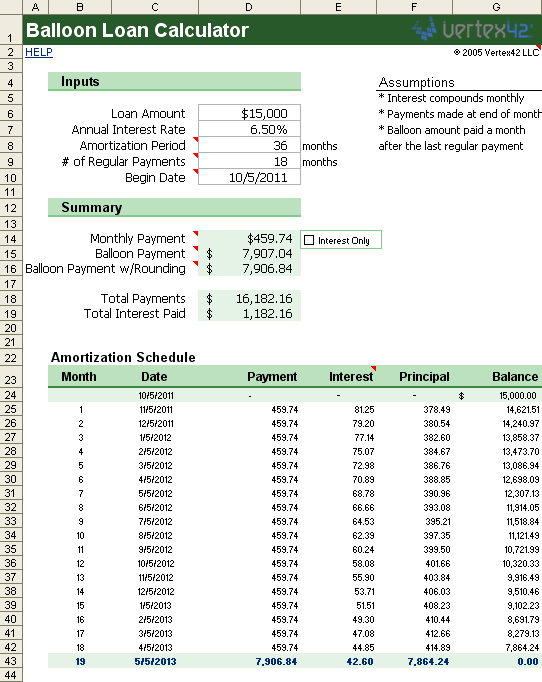
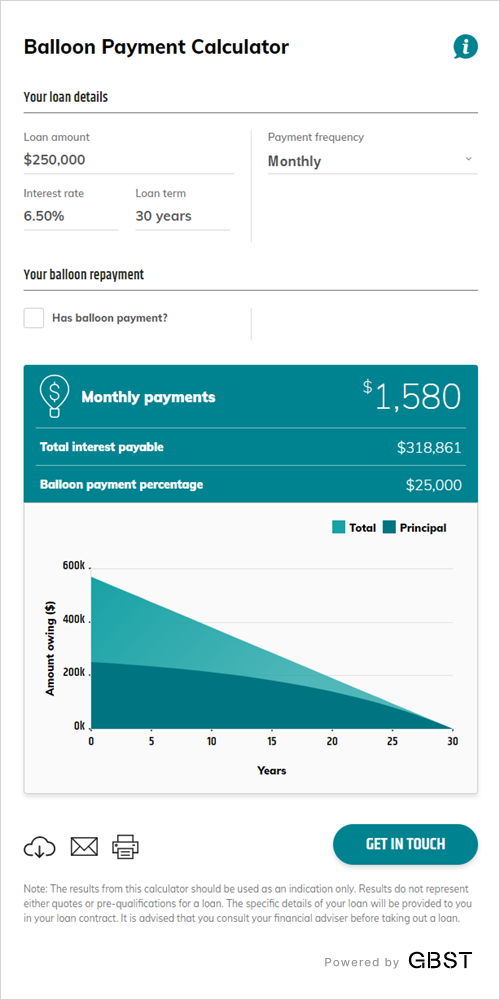
Enter your loan amount, the annual interest rate, the total term of the loan in months, and the month when the balloon payment is scheduled. The calculator will show your regular monthly payment amount and the balloon payment due at the end. But here is where people get tripped up. The balloon payment is not simply the remaining principal. In most amortization schedules, the monthly payment is calculated as if the loan will be fully paid off over the entire term. When a balloon payment is introduced, the payment amount stays the same but a large portion of principal remains unpaid at the balloon date. I once worked with someone who assumed the balloon payment was just the original loan amount minus whatever they had paid in principal during the regular payment period. Wrong. The actual balloon payment is the remaining balance after all those payments, which requires looking at the amortization schedule, not doing mental math. The calculator handles this correctly, but only if you understand what each field represents.
Get the Full Details
Common Pitfalls and When It Fails
The biggest issue I encounter is people using a Baloon Payment Calculator for loans with variable rates. These calculators assume a fixed rate throughout the entire term. If your loan has an adjustable rate that resets at year three, the calculator's output will be wrong for any periods after the reset. You would need to recalculate separately for each rate period and then combine them, which most simple calculators cannot do. Another scenario where these tools fall apart is prepayment. If you plan to make extra payments toward principal before the balloon comes due, the regular monthly payment figure the calculator gives you becomes irrelevant. The balloon payment will be lower than projected because you have reduced the principal. I usually recommend running the calculator for the base case, then building a separate schedule that accounts for any planned prepayments. There is also the issue of fees and insurance not being included. Most calculators show just the principal and interest portion. But your actual monthly outlay might include property taxes, homeowners insurance, and private mortgage insurance. A $2,500 monthly P&I payment could easily become a $3,200 total housing payment once those extras are added. Make sure you account for these separately when budgeting.
Download and Setup
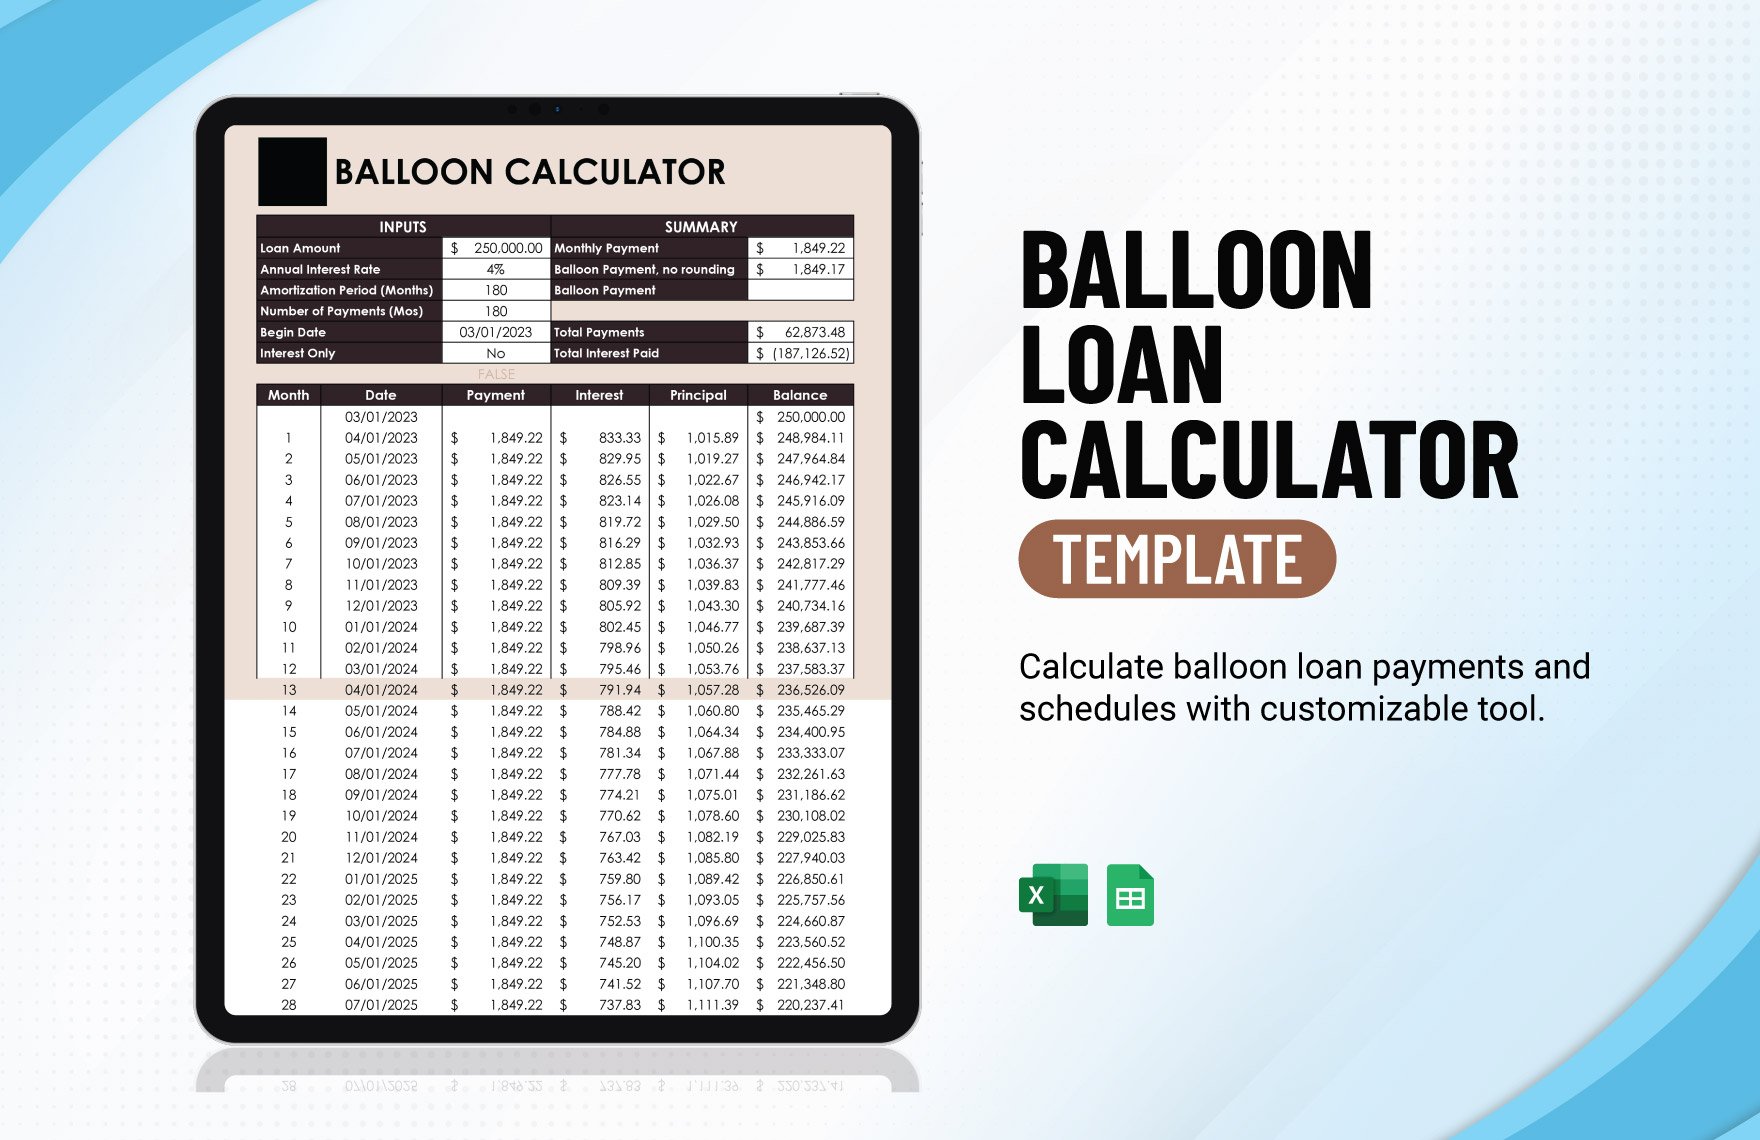
For those who want more control than a web-based tool provides, there are downloadable spreadsheets available from several financial modeling sites. The free versions usually handle standard fixed-rate balloon loans adequately. If you need something more sophisticated with variable rates, prepayment schedules, and fee calculations built in, the paid versions run anywhere from $30 to $150 depending on features. I stick with a custom Excel setup I built years ago. It takes about five minutes to enter the loan parameters and shows you the monthly payment, the cumulative principal paid at any point, the remaining balance, and the balloon payment due. The initial investment of time was worth it because I have used it on over two dozen deals since then, and it pays for itself in the first month of accuracy alone.
When to Use Alternative Methods
If your balloon loan involves points and fees amortized over the life of the loan, a standard Baloon Payment Calculator will not capture the true cost. The effective interest rate will be higher than the nominal rate you entered. In these cases, I recommend using an APR calculator instead, which factors in all the upfront costs, and then cross-referencing with the balloon payment schedule. For subprime loans with penalty rates or negative amortization, the calculator outputs are unreliable. These loan structures have rules and conditions that most standard calculators cannot model. If your situation involves any of these edge cases, I suggest consulting directly with a loan officer or using specialized commercial lending software rather than relying on a generic online tool. The key takeaway is that a balloon payment calculator is useful for straightforward fixed-rate scenarios. It gives you a reasonable estimate quickly. But if your loan has any unusual features, variable components, or you need precise numbers for financial planning, you should verify the calculator's output against the actual amortization schedule before making any decisions based on it.