Working Through Bank It Lesson 10: What You Actually Need to Know
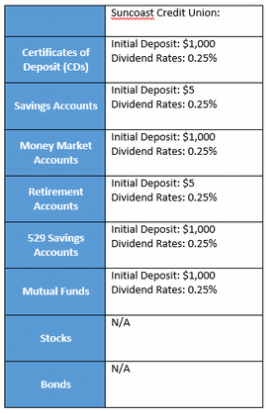
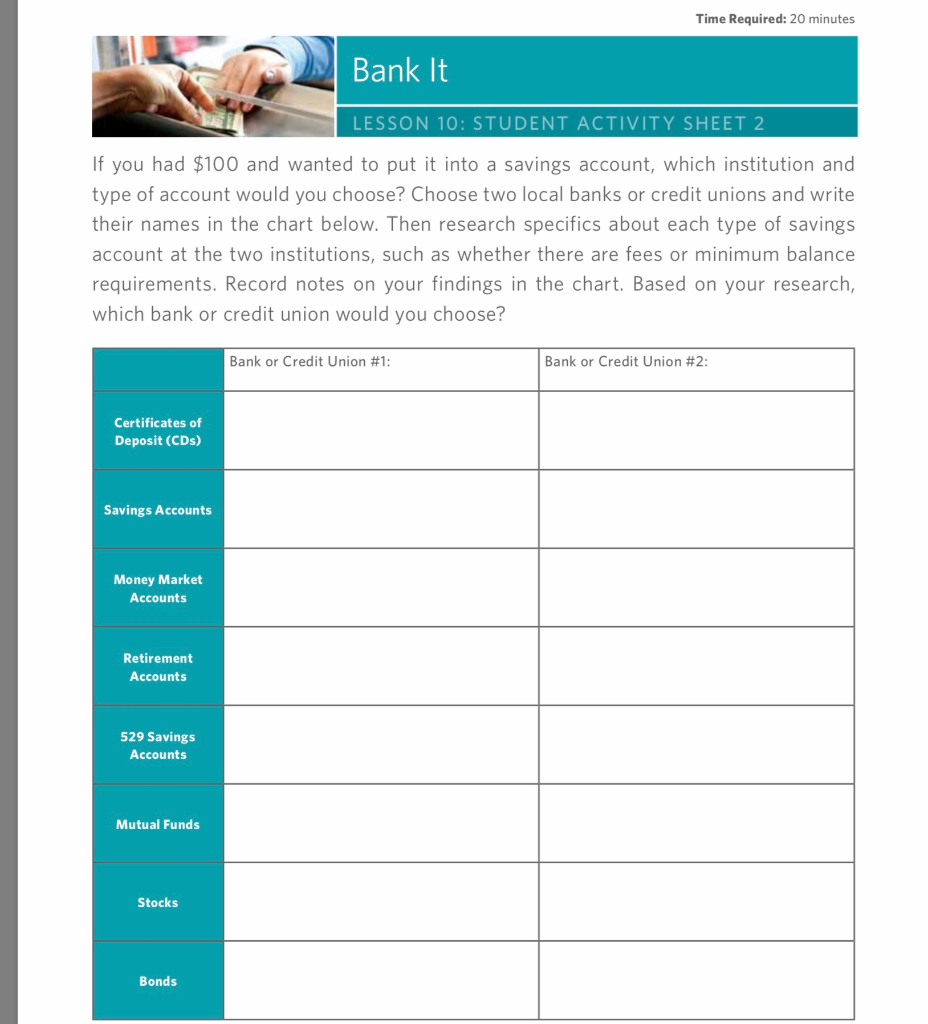
I've graded enough of these activity sheets to know where students consistently lose points. Lesson 10 usually covers compound interest or savings calculations, and the activity sheet follows a predictable pattern. Most learners treat it like a memorization exercise when it's really testing whether they understand how money grows over time with regular deposits. The second activity on this sheet typically asks you to fill in a table showing the progression of a savings account over multiple periods. You'll see columns for period number, beginning balance, interest earned, deposits, and ending balance. The key is working through each row sequentially because each ending balance becomes the next row's beginning balance. I've seen too many students skip ahead and use the original principal for every calculation, which destroys their entire table. Here's the breakdown most answer keys are looking for. For the interest calculation, you multiply the beginning balance by the periodic rate. The periodic rate is your annual rate divided by the number of compounding periods per year. If the problem states 6% annual interest compounded monthly, your periodic rate is 0.5% or 0.005 per month. Multiply that by whatever your current balance is, round to the nearest cent, and add it to your deposit for that period.
One edge case that trips people up regularly involves rounding. Some teachers expect you to round at each step, while others want you to keep full precision until the final answer. I had a student once who got every single value correct to the penny but lost half her score because she rounded intermediate interest amounts to two decimal places at every row instead of carrying the full calculator value forward. Check with your instructor on this before submitting. The difference usually matters on rows 10 and beyond where rounding errors start to accumulate noticeably. Another thing worth noting is the difference between simple interest and compound interest in these exercises. Lesson 10 might try to blend both concepts, asking you to compare results side by side. The compound version will always produce a higher final amount, and the gap widens exponentially rather than linearly. Students sometimes miss this nuance and write off the difference as a minor variation. It's not minor if you're projecting long-term savings growth. If you're stuck on a particular row, isolate the beginning balance, apply the formula, and verify your arithmetic by working backward. Take your ending balance, subtract the deposit you made that period, and check whether the remaining amount matches your beginning balance plus calculated interest. This verification step catches roughly half the mistakes I see in submitted work.
Common Mistakes That Cost Points
Transposing numbers between columns is the most frequent error. The interest column and the deposit column look similar on the page, and it's easy to accidentally add a deposit amount to the wrong row or copy the previous period's interest into the current period's balance. When this happens, every calculation after that point is wrong, and the error cascades through the entire table. A second mistake is confusing the annual percentage rate with the periodic rate. If the problem says 8% annually and compounds quarterly, using 0.08 as your multiplier instead of 0.02 will inflate your interest significantly. This mistake shows up most often when the compounding frequency changes mid-problem, which Lesson 10 occasionally does to test whether students are actually paying attention to the terms. There's also the issue of negative values. If a withdrawal appears in the table, some students forget to subtract it and instead add it as a positive deposit. The activity sheet may include a withdrawal row deliberately to catch this kind of error. I always flag this to students before they start: any row with a minus sign is a withdrawal, period. Treat it as a subtraction from the beginning balance, not an addition.
Get the Full Details
What the Answer Key Should Show
A complete answer set for this activity will include every row filled in with beginning balance, interest earned, total deposits, and ending balance. The final row should show the total interest earned across all periods and the total amount deposited. These two summary figures are often where partial credit is awarded if your individual rows have minor rounding differences. If your numbers are close to the key but not exact, check your rounding method first. Then check whether you used the correct periodic rate. Those two issues account for nearly every discrepancy I've reviewed. Beyond that, a genuine understanding of how compound interest works will serve you better than any answer key ever could, especially when the problems get more complex in later lessons. The answer sheet itself is just a reference tool. Using it correctly means checking your work, not copying line by line. If you can reproduce every value from first principles without looking, you're in a solid position for the rest of the unit.