How to actually work with your Bank Of America Transaction History
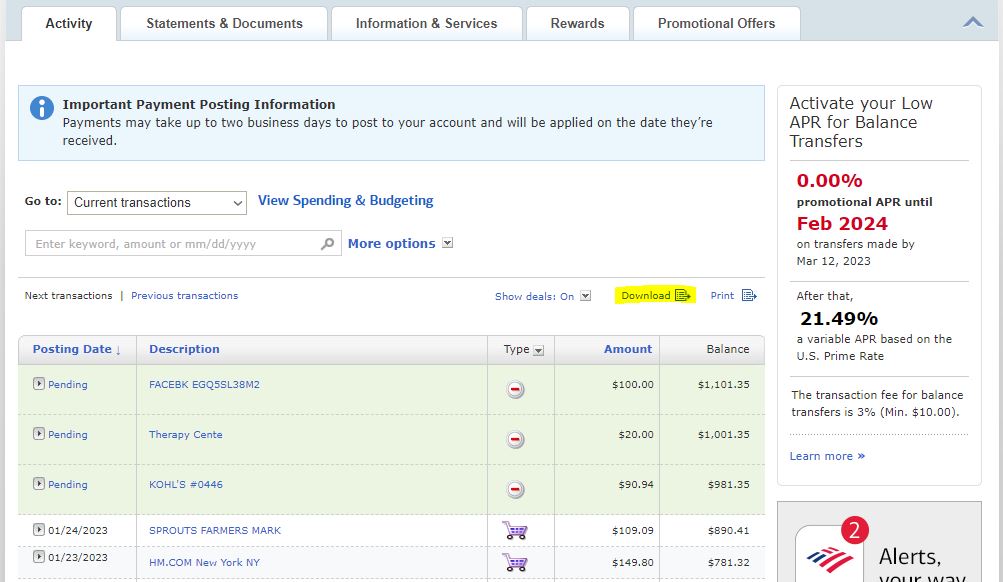
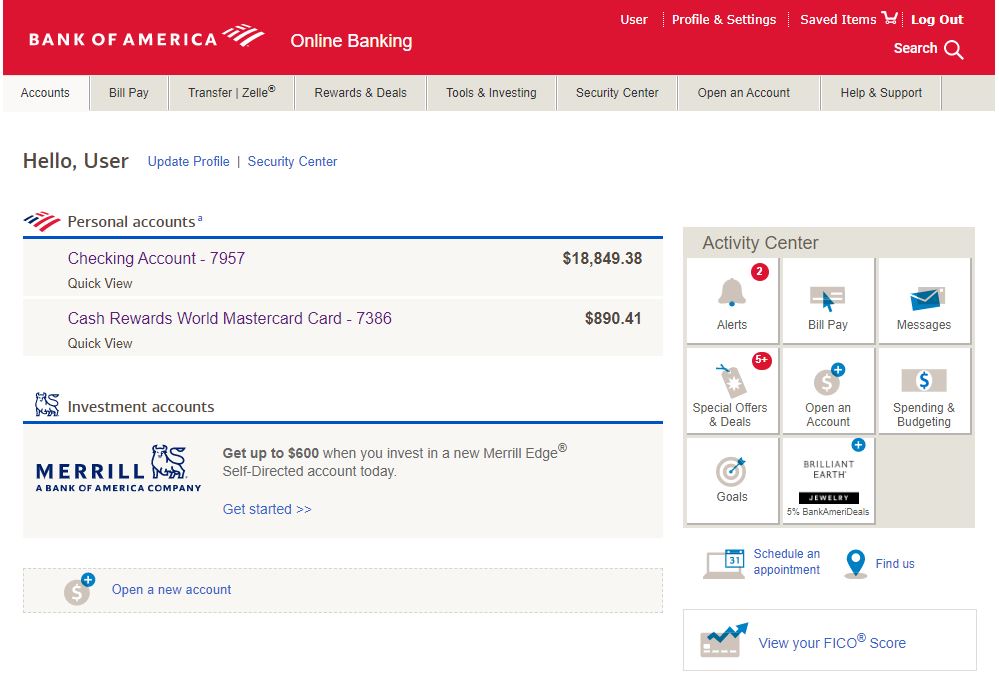
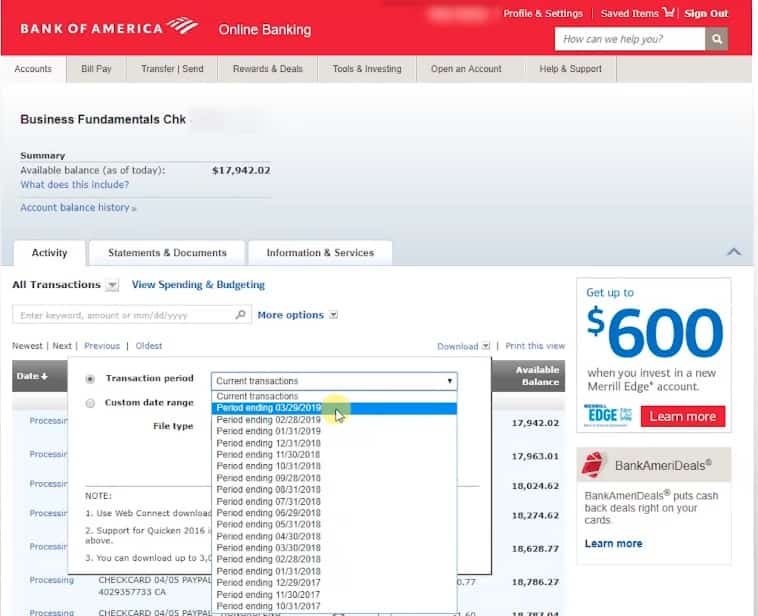
The transaction history is accessible through online banking and the mobile app, but the real problem most people run into isn't finding it — it's extracting and processing it in a usable format. I've been dealing with banking exports for years, and the Bank of America approach has some quirks that trip people up constantly. Here's how to handle it without wasting an afternoon. Log into your account at bofa.com and navigate to Accounts from the top menu. Click the account you need — checking, savings, or credit card — and you'll see a statement tab or a recent activity link on the right side. That takes you to the transaction list. You can set the date range, usually going back as far as seven years for most account types, though some older records get pushed to archived statements that require a separate click to pull. Once you're looking at the transactions, there's an export button. It's often hidden under a dropdown that says something like "More options" or "Download." The default format is CSV, which is the one you want if you're doing anything beyond casual review. You can also get QIF or OFX, but those formats eat data or mangle categories. CSV keeps everything intact and plays nicely with Excel, Google Sheets, and whatever reconciliation tool you're using.
I ran into a specific issue last year that took me about three hours to figure out. My employer does monthly payroll audits, and I needed to pull a full fiscal year of transactions to reconcile some disputed items. I selected the date range, clicked export, and downloaded the CSV. Opened it up, and roughly forty transactions were missing — specifically, ones that had been reversed or adjusted within the same calendar month. The export simply omitted reverse entries, which made my debits and credits not balance at all. I couldn't use it for the audit. The workaround was to go into the account detail view and use the "Customize Columns" option to show the transaction type field, which labels entries as Purchase, Payment, Transfer, Adjustment, Reversal, and so on. Then I exported again. This time the reversed transactions showed up with negative amounts and a reversal flag, which meant I could filter them properly in Excel and include them in my reconciliation. Without that column, they were invisible. If you're doing formal bookkeeping, always add the transaction type column before you export. It takes five seconds extra and saves you from pulling your hair out later.
What the columns actually mean
The raw CSV from Bank of America gives you a set of fields that are fairly standard but not always intuitive. You'll see a date column, which is almost always the posting date, not the transaction date. That distinction matters. A check you wrote on the 28th of the month might not post until the 2nd of the following month, and the CSV will reflect the later date. If you're reconciling against a check register or an expense report, you need to be aware of that gap. The transaction date sometimes appears in a separate column depending on the account type, but it's inconsistent across checking, savings, and credit accounts. Don't assume it's there. You'll get a description field, an amount field, and a running balance. The description field is where Bank of America stuffs their merchant names, but they're not consistent. Sometimes you'll see the actual business name, sometimes a truncated version, sometimes just a location code. One time I pulled a year of data and couldn't find a single entry with a clear merchant name for a subscription service — it was just a routing number and a code I had to look up on the provider's site. The running balance is also computed by Bank of America on their end, which means if a transaction gets reversed after the fact, the historical running balance doesn't update in the CSV. It shows the balance as it existed at the time of each export. For most personal finance tracking that's fine, but for accounting purposes you can't rely on the running balance column to verify correctness. There's also a post date and a transaction date field in some exports, but only if you requested a detailed download and have certain account types. Most people just get the basic CSV and assume they're getting the full dataset. They're not. If you need the transaction date for compliance reasons — say you're tracking when a charge actually occurred versus when it posted — you have to request the detailed format, which sometimes requires calling customer service to unlock depending on your account tier.
Get the Full Details

Common pitfalls and what to watch out for
The biggest trap is assuming the export is immutable. Bank of America updates transaction records retroactively. If a fee was charged in January and they credited it back in March after a dispute, your export from February would show the fee, and your export from April wouldn't. The running balances differ between the two files. If you're building a permanent record, download the file and immediately save a copy with a timestamped filename. Don't trust yourself to re-export later and expect the same result. Another thing nobody warns you about: international transactions. If you travel or shop on foreign sites, Bank of America posts these with a converted amount and sometimes a separate foreign transaction fee line item. The CSV may show two rows for a single purchase — one for the original charge and one for the fee. They don't always label the fee clearly. In my experience, fee rows have the word "Foreign" or a country code in the description, but not always. If you're automating expense categorization, you'll want to set up a filter that flags any description containing "Foreign" or amounts with more than two decimal places followed by a rounded secondary charge. That second charge is almost certainly the fee. Recurring payments are another headache. Bank of America lists them identically to one-time purchases in the CSV. There's no recurring flag. If you're trying to separate subscriptions from random spending for budgeting purposes, you're on your own to identify them. The pattern matching works to some degree — same merchant, same amount, regular intervals — but it's fragile. A subscription that changes price annually breaks the pattern immediately.
When the CSV approach breaks down
There are scenarios where pulling transaction history from Bank of America directly becomes impractical. If you need real-time transaction feeds for automated accounting, the CSV export is batch-based and manual. You'd need to set up a scheduled routine of logging in and downloading, which introduces latency and human error. Bank of America doesn't offer a direct API for consumer accounts. Some businesses with commercial accounts can access Plaid or similar services, but individual consumers are stuck with the manual route unless they're willing to use a third-party aggregator, which brings its own privacy and reliability concerns. If you manage multiple accounts — say a joint checking with a spouse, a savings account, and a credit card — exporting each one separately and merging them in a spreadsheet works but gets tedious fast. The manual process usually takes about twenty minutes per account per quarter if you're doing it right. That compounds quickly if you have four or five accounts. In that case, looking into a personal finance tool that can pull from Bank of America through a secure connection like Plaid or Yodlee saves significant time. The tradeoff is handing over your credentials to a third party, which some people won't accept. It's a legitimate concern, not something to dismiss. The mobile app export is more limited than the web version. You can view transactions and set date ranges, but downloading a CSV typically requires the desktop site. If you're on the road and need to pull records urgently, you'll need to log into bofa.com from a browser rather than the app. The app is fine for viewing and basic troubleshooting, but don't count on it for data extraction.
Practical tips that actually matter
When you export, always check the row count before closing the browser tab. Bank of America sometimes cuts off exports at ten thousand transactions, and if your account is active enough to exceed that in a single date range, you'll get a truncated file with no warning beyond a missing chunk of data. If you suspect this happened, split your date range into quarterly segments and verify each one individually. It adds time but prevents silent data loss. Save every export. Not because you won't need it later, but because the data changes. I learned this the hard way when a bank error caused duplicate charges on my account, and by the time I flagged it three months later, the corrected version in the system no longer showed the duplicates in a fresh export. I had my original file saved with the errors intact, which was the only proof I needed to get the dispute resolved. Without that saved file, I would have had nothing to show. If you're doing tax preparation, note that Bank of America transaction history includes interest earned and fee charges, but it doesn't categorize them for tax purposes. You'll see the dollar amounts, but you need to identify which line items are taxable interest versus non-taxable rebates or adjustments. The description field sometimes includes codes like "INT" or "DIV" that help, but not consistently. Cross-reference with your annual 1099 forms, which Bank of America sends out in January. The 1099-INT and 1099-DIV are the authoritative documents for taxes, not the raw transaction export.

The search and filter functions on the website are adequate but not great. You can filter by date, amount range, and description keywords, which covers most basic needs. But you can't filter by payee name variations — if a merchant appears as "Amazon.com" on one line and "AMZN MKTP" on another, they won't group together. The keyword search is case-insensitive but doesn't handle partial matches well either. For heavy filtering, export to CSV and use spreadsheet formulas instead. It's faster once you've done it a few times. There's also a feature called "Manage Notifications" where you can set up alerts for transactions above a certain amount or from specific merchants. This doesn't change the transaction history itself, but it can help you catch unusual activity earlier. I set a $50 threshold alert on my checking account, and it flagged a fraudulent charge within hours of it posting. That's about the most useful thing this system does beyond basic record-keeping.
The bottom line on limitations
Bank of America's transaction history system works adequately for personal use and light reconciliation. It's not built for serious accounting workflows, and that's the honest assessment. The export format is usable but incomplete by default. The data is subject to retroactive changes that break historical records if you don't save copies. There's no API, no real-time feed, and no way to automate downloads without scripting or third-party tools. For someone who checks their balance once a week and occasionally pulls a statement, these are minor inconveniences. For someone doing monthly bookkeeping or forensic analysis, they're significant obstacles. If your needs are minimal, the built-in tools are fine. If you need rigorous, reliable transaction data for business or compliance purposes, you'll be better served by connecting through a dedicated accounting platform or requesting a full data export via a formal channel. The standard CSV download is a consumer-grade product, not an enterprise-grade one, and treating it like something it isn't is how people lose track of money.