Getting the numbers to match when they obviously shouldn't
Open your bank statement. Open your ledger. The balance says $47,312.50 on the bank side and $44,891.00 in your books. That's a $2,421.50 gap. You are not going crazy. This is exactly what the Bank Reconciliation Worksheet exists to do — bridge that gap systematically instead of staring at two screens and hoping one of them is right. I used to do this entirely in my head for small accounts. Then I managed a portfolio with twelve separate checking accounts, each reconciling at different points in the month. The mental math collapsed on a Tuesday when two overdraft fees from a client hadn't posted yet and I attributed the difference to a missed deposit. It took me three business days to find it because I had no paper trail. After that, I built a structured worksheet and never looked back.
Bank Reconciliation Worksheet structure
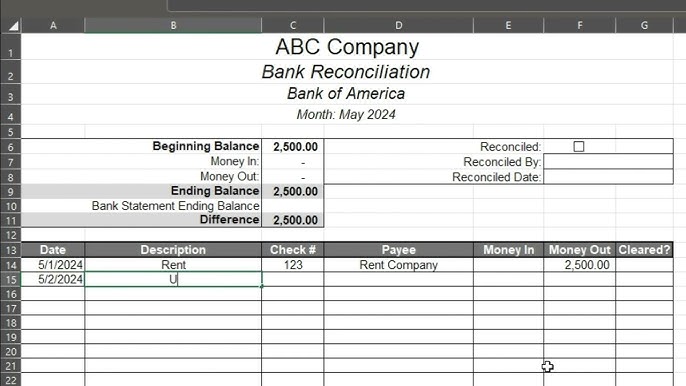
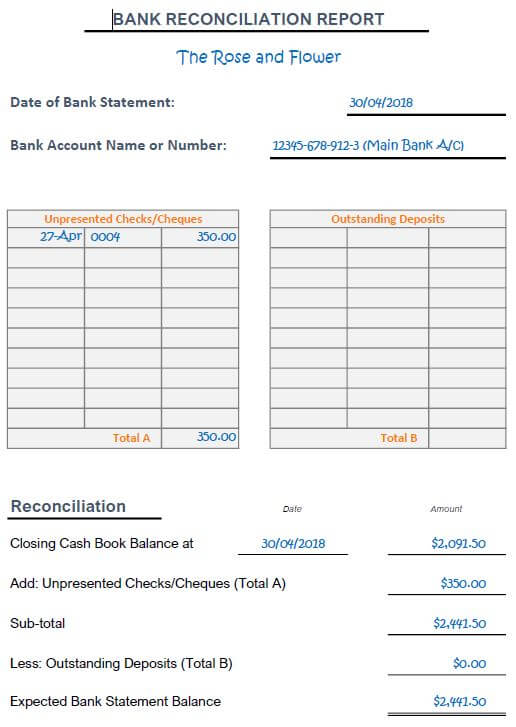
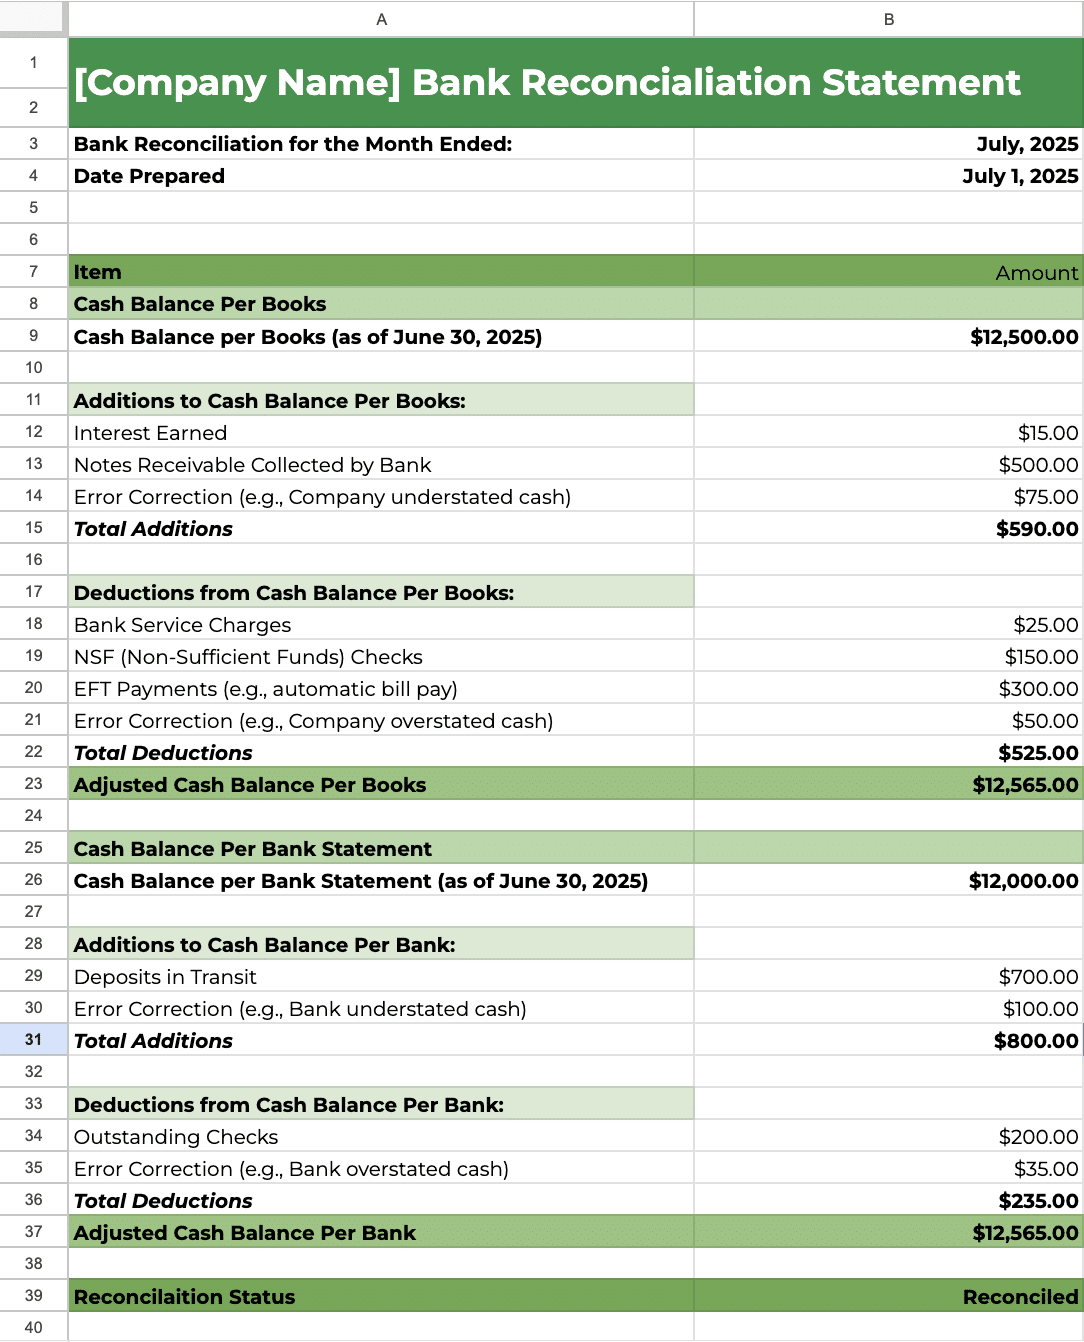
Here is the practical layout. You need two sections on the same page, side by side or stacked vertically, and you need them to arrive at the same adjusted balance. Bank side adjustments: Start with the bank statement closing balance. Add deposits in transit — money your company recorded but the bank hasn't processed yet. Subtract outstanding checks — payments you've written and recorded but the recipient hasn't cashed. Add any bank errors you've identified. Subtract any bank errors in the opposite direction. The result is your adjusted bank balance.
Book side adjustments: Start with your general ledger cash balance. Add interest earned, direct deposits, or collections the bank processed but you haven't recorded. Subtract service charges, NSF checks, wire fees, and any other deductions the bank made that your books don't reflect yet. Adjust for any book errors you've found. The result should match your adjusted bank balance exactly. If they don't match, you have an unreconciled item somewhere. Go back through each line. Don't skip anything because something "looks small." I once spent four hours tracing a $37.50 difference that turned out to be a single check recorded as $3.75 in the ledger. Digit transposition. Common. Painful if you're not looking for it.
Get the Full Details
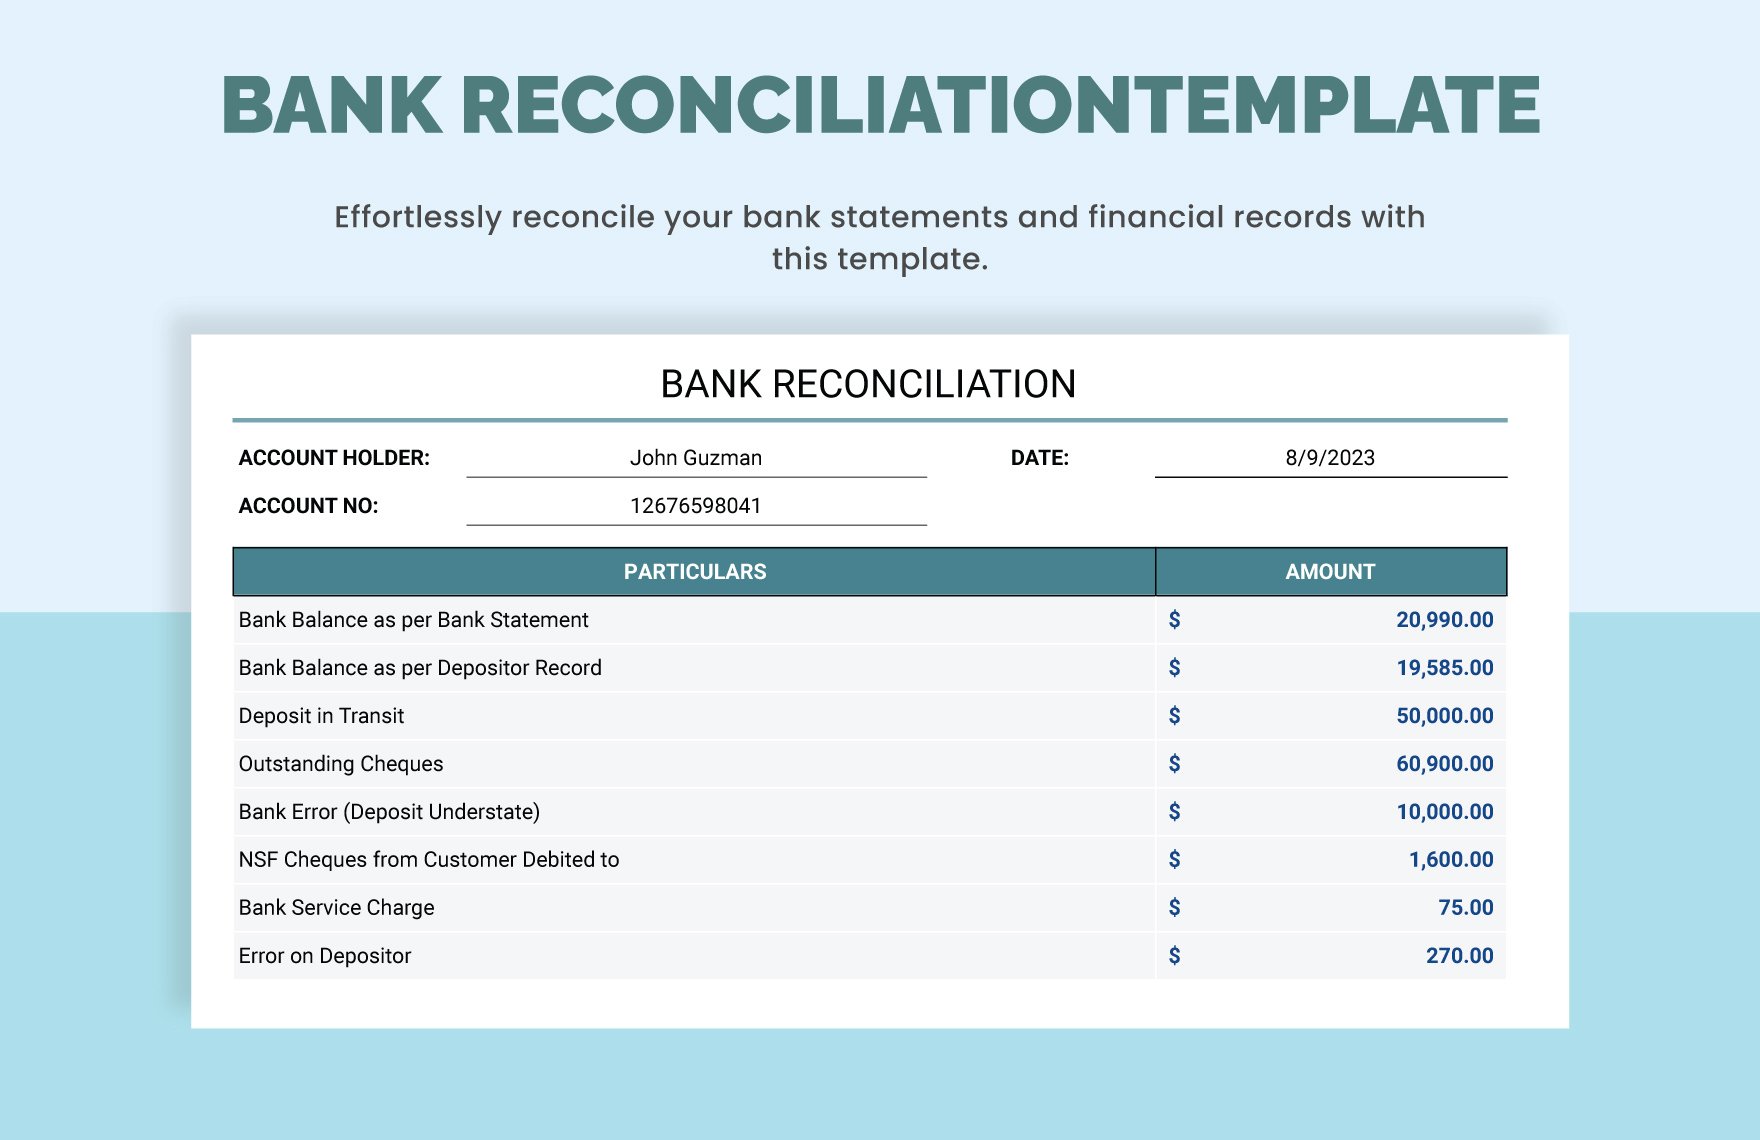
The format itself doesn't matter much — spreadsheet, document, accounting software report — but every legitimate reconciliation needs these components: the starting balances from both sides, each adjustment itemized with a date and reference number, the adjusted balances, and a clear indication of whether they match. Without reference numbers, you can't audit it later. Without date stamps, you can't tell if something was sitting unreconciled for six months. I keep mine in a Google Sheet with color coding — green for matched items, yellow for pending items over 30 days, red for anything unresolved past 60 days. At month-end, I export a PDF and file it alongside the bank statement. This took me from spending roughly 90 minutes per reconciliation to about 12 minutes once the template was stable. Early on it was closer to 45 minutes while I was still building the habit. There are edge cases that will trip you up no matter how clean your system is. One that bites people repeatedly is the timing difference on recurring automatic payments. Your vendor sets up an ACH withdrawal on the 15th, your software records it on the 15th, but the bank processes it on the 16th because it hit after their cutoff time. Next month you'll see the same pattern again unless you build a buffer rule into your tracking. I learned this the hard way when a $12,400 payroll ACH kept appearing as an outstanding item for two full cycles before I realized the bank was processing it one business day after my recording date.
Another thing people miss: intercompany transfers. If Company A sends money to Company B and both companies are reconciling separately, the money exists in both ledgers at the same time during the transfer window. It shows as an outstanding item on both sides until it clears. Track these with a dedicated transfer memo field so you can match them across entities without confusion. The biggest limitation of any worksheet approach is that it only works with data you actually have visibility into. If your bank doesn't provide real-time feeds and you're working from monthly PDF statements, your reconciliation is inherently backward-looking. You're matching history, not current state. For high-volume accounts with hundreds of transactions per month, this creates a compression problem — by the time you receive the statement, you're already weeks behind and the window to catch errors before they compound is narrow. In those cases, a periodic bank feed integration that pulls daily transaction data is worth the setup cost, even if the final formal reconciliation still happens monthly. Another blind spot: merchant processing holds. If you run card payments through a processor like Stripe or Square, the settlement batch might show as a single deposit on your bank statement while your books contain forty-seven individual transactions. The worksheet handles this by treating the batch total as one reconciling line, but only if your chart of accounts is set up to route card sales through a clearing account rather than straight to revenue. Get that wrong and you'll spend your reconciliation time trying to force-fit individual transactions against a lump sum that will never match line by line.
Foreign currency accounts add another layer. The bank statement balance is in the foreign currency, but your books might be maintaining both a local-currency record and a USD-equivalent record. Reconcile against the local currency balance first, then verify the exchange rate adjustment matches what your accounting system calculated. Skipping the local-currency step is how people miss rate discrepancies that compound over time. There is no automated fix for human entry errors in your own ledger. The worksheet catches them by revealing mismatches, but it won't tell you which specific transaction is wrong. You hunt those down by working backwards from the difference amount — if the gap is $847, look for a single transaction of $847, or combinations that sum to it. Check for reversed debits and credits, duplicated entries, and transactions posted to the wrong account. The difference amount itself often tells you what kind of error you're dealing with. A difference divisible by 9 usually means a digit transposition. A difference that matches a specific invoice amount means that invoice was either double-recorded or omitted entirely. The worksheet is a tool, not a process. The process is what matters — doing it consistently, documenting every adjustment, and never leaving items unreconciled past two cycle dates without a documented reason. Everything else is just formatting.