Building a Bank Statement That Actually Works
Most bank statement templates you'll find online are garbage. They either pull too much unnecessary detail or miss the fields that actually matter for reconciliation. I spent three years dealing with bank statements from different institutions before I figured out what makes one useful versus what makes it a pain to work with. The core issue is that every bank formats their statements differently, but your template needs to normalize them into something consistent. Here's how I approach it.
What to Put in Your Bank Statement Template
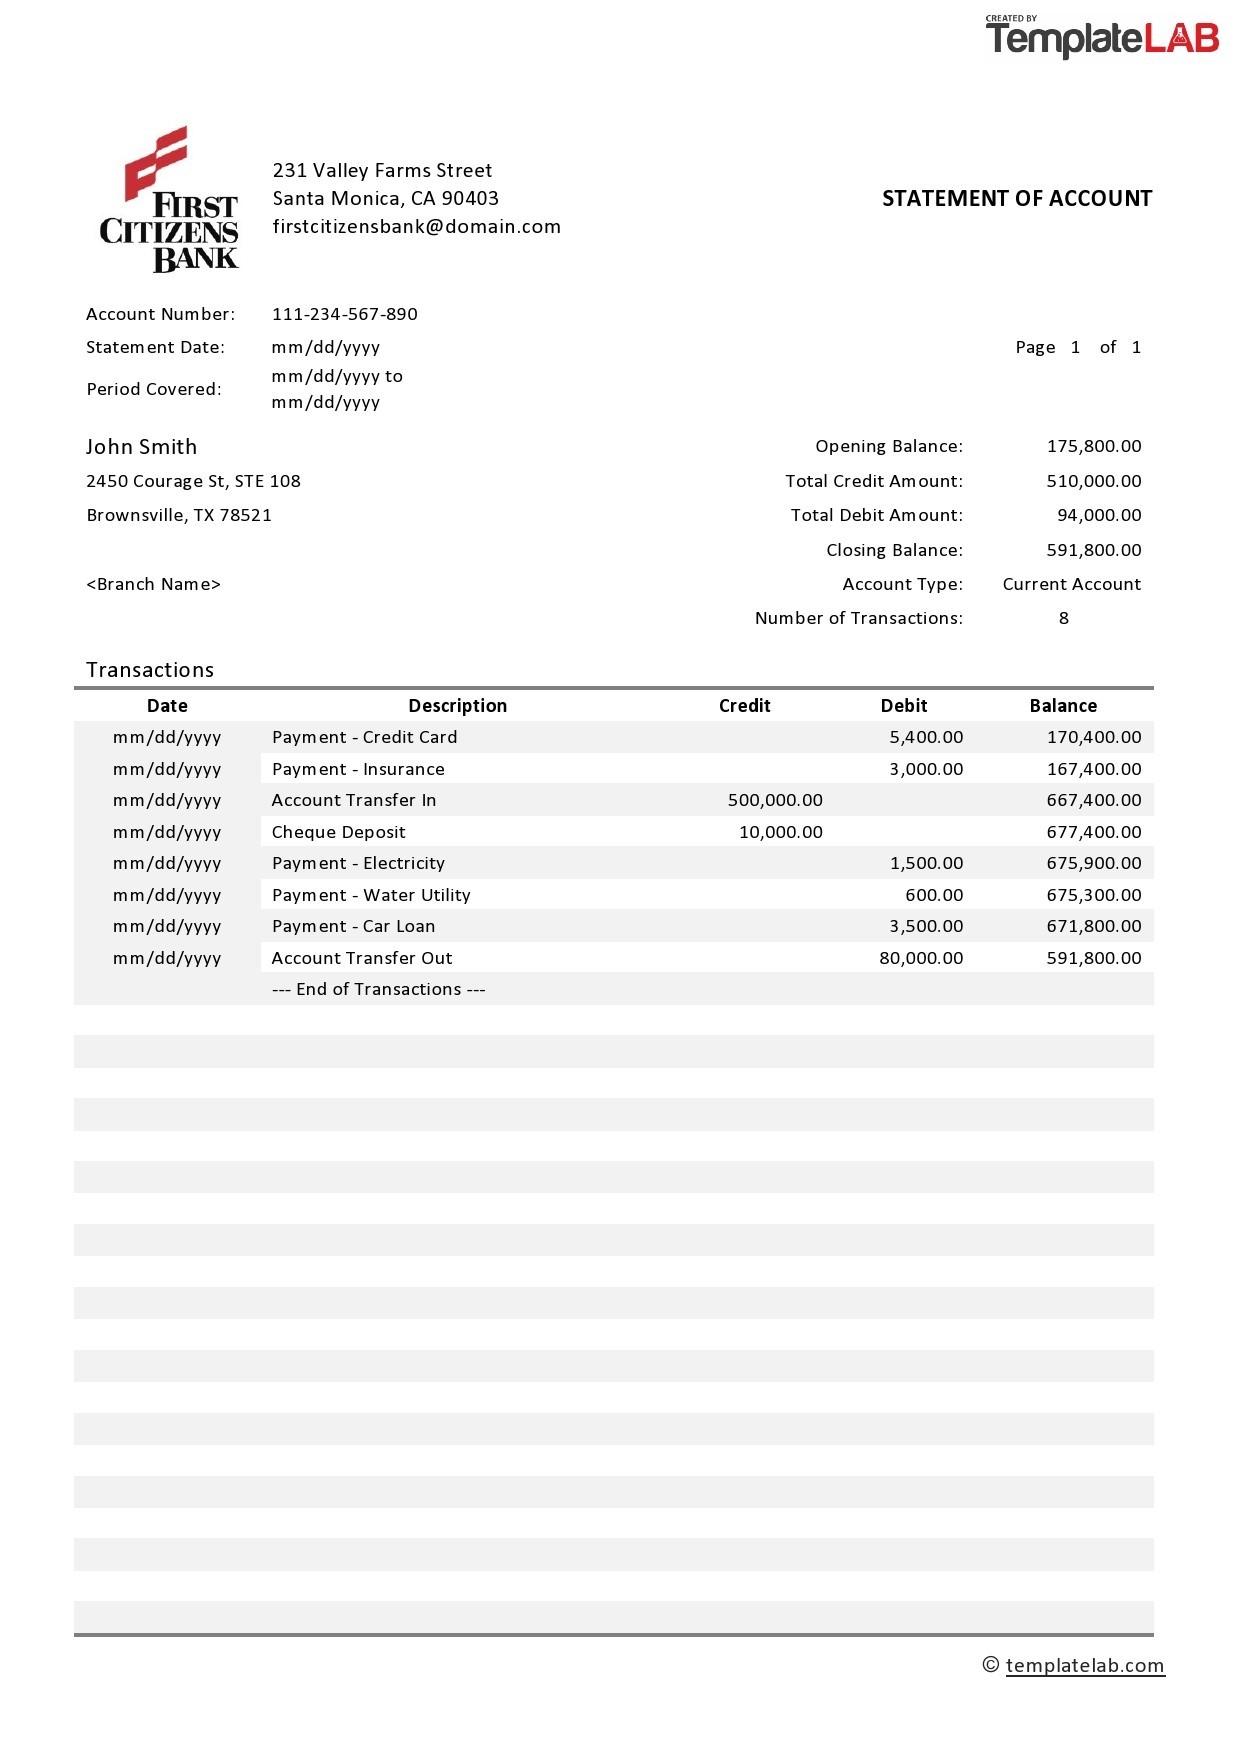
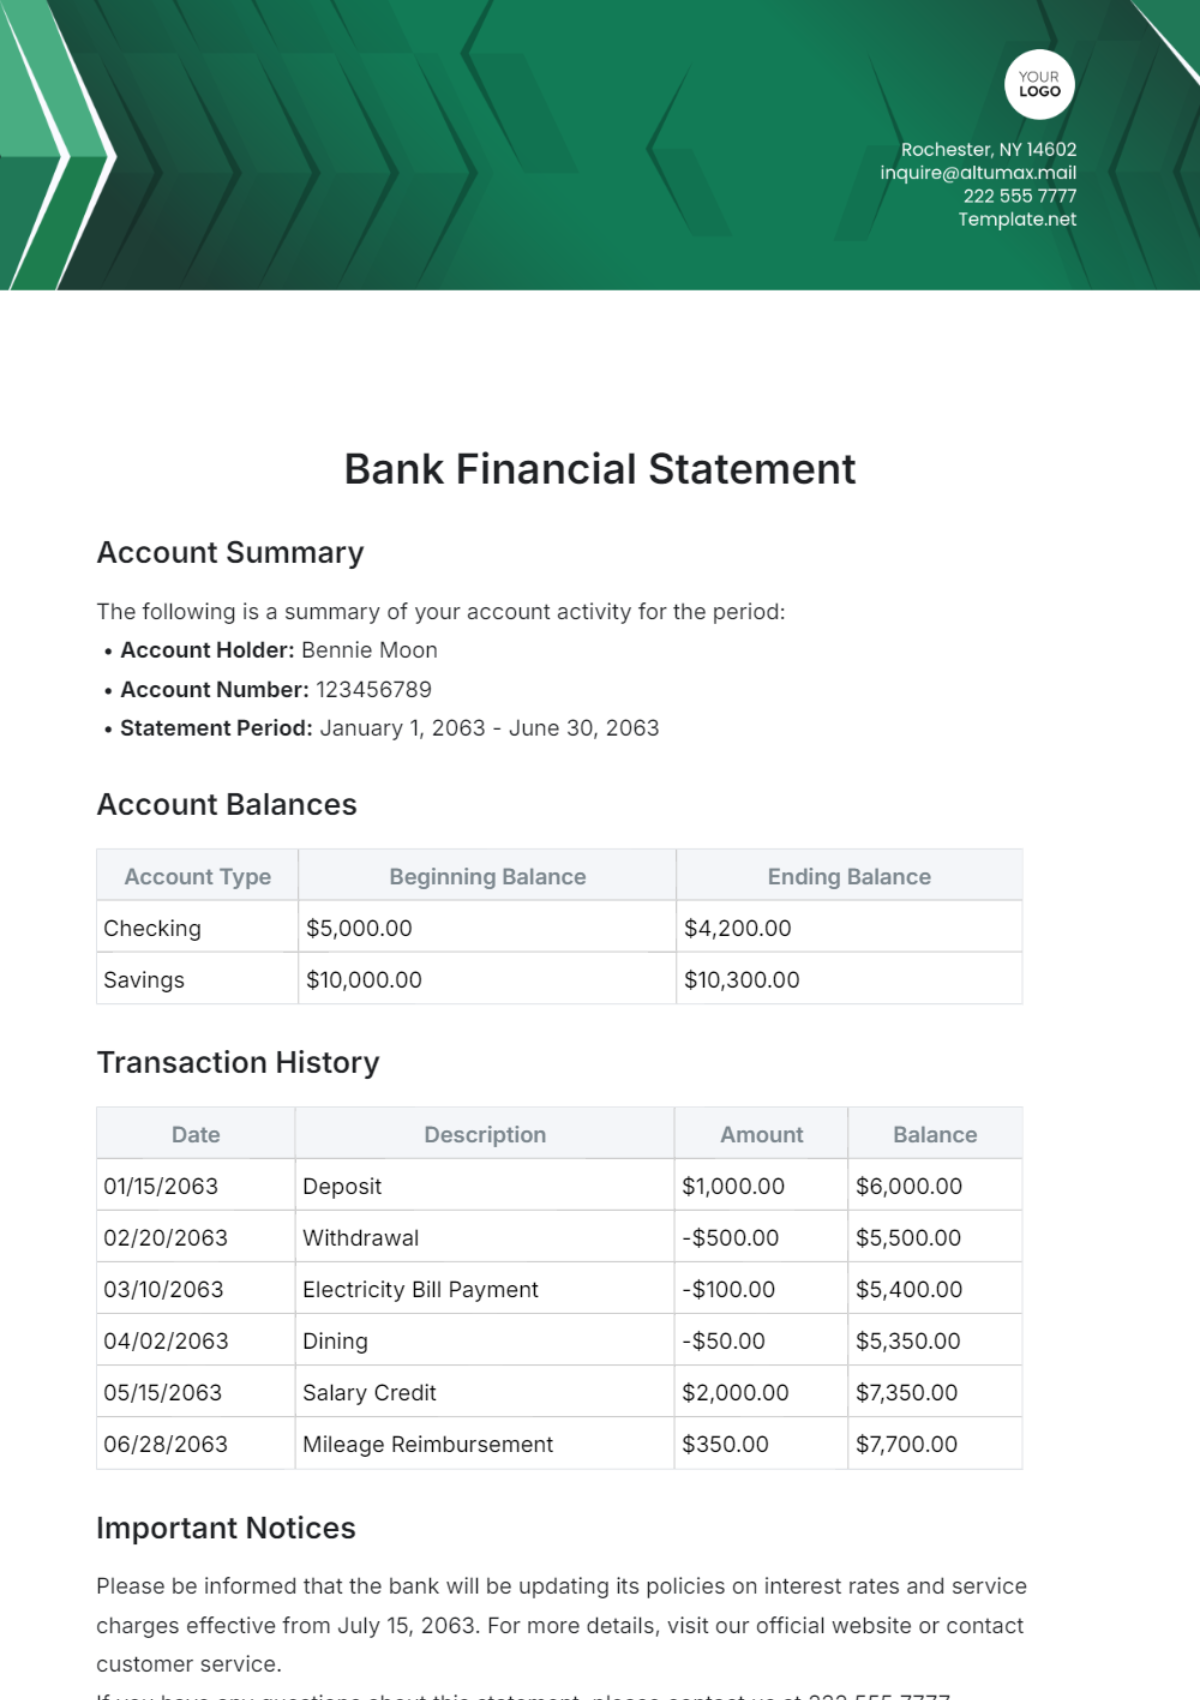
A proper Bank Statement Template should capture these fields at minimum: transaction date, posting date, transaction description or merchant name, amount debited, amount credited, running balance, and the transaction reference number. Everything else is noise. I've seen people try to include category codes and routing details, but 90 percent of the time those don't matter until you hit an audit situation. The format matters less than the fields. CSV works fine. Excel works fine too, though I've had issues with auto-formatting turning dates into numbers. Stick with YYYY-MM-DD for dates. It saves you from parsing errors later. Here's the practical part. When I was setting this up for a mid-size operations team, we had a problem where Chase and Wells Fargo would both list the same recurring payment twice on the statement — once as a pending charge and once as posted. A basic template wouldn't flag this. I built in a deduplication column using the transaction reference number combined with the posting date. If two rows shared both values within a 48-hour window, the template flagged it for review. That single addition cut our monthly reconciliation errors from about eight per month down to one or two.
Setting Up the Template
Open a blank spreadsheet. Set the first row as headers. Column A: Date. Column B: Posting Date. Column C: Description. Column D: Debit. Column E: Credit. Column F: Balance. Column G: Reference ID. Column H: Flagged for Review. That's it for the core version. Now the formula work. In the Balance column, if you're pulling from raw data, use a running total formula. Starting from row 2, enter =F1+E2-D2 and drag it down. This keeps the balance accurate even if transactions come in a jumbled order. For the flagged column, use this logic: =IF(AND(G2=G1,B2=B1,ABS(A2-A1)
=4),"Review",""). This catches duplicate entries based on reference ID and date proximity. Adjust the 4 to your comfort level — some banks post same-day transactions that look like duplicates but aren't.
Get the Full Details

Where This Breaks Down
I need to be straight about the limitations. A template like this only works well when your banks provide exportable data. Some regional credit unions still don't offer CSV downloads, which means you're manually entering data and the whole efficiency argument falls apart. In those cases, using a tool like Plaid or Yodlee to aggregate the data first is worth the setup time. It adds maybe 20 minutes initially but pays for itself within a couple months. Another problem: multi-currency accounts. The template assumes a single currency. If you deal with international transactions, add a currency column and a conversion rate column, then calculate a localized balance. Without this, your running balance will be wrong and you won't notice until the audit hits. The biggest pitfall beginners miss is not including the source bank and account number as columns. When you're consolidating statements from four or five institutions, you'll end up with a merged sheet and have no idea which transaction came from where. Add a Bank Name column and an Account Number column at the front. Takes ten seconds and prevents hours of confusion later.
Getting the Data In
Export your statement from the bank's website in CSV format if possible. If they only offer PDF, you'll need to either rekey the data or use an OCR tool. The OCR route works okay for clean statements but struggles with banks that use tables or split descriptions across multiple lines. I learned this the hard way when a vendor statement had transaction details wrapped across three lines and my parser ate half of them. Once you have the CSV, open it and clean it up. Remove header rows that the bank includes before the actual data starts. Some banks put three to five lines of junk at the top. Look for the first row that has a valid date and build from there. Map the bank's columns to your template columns. Date maps to Date. Description maps to Description. If the bank combines debits and credits into a single Amount column, split it: negative values go to Debit, positive to Credit. This is where most people get stuck, so pay attention here.
After mapping, run a quick validation. Sum your Debit column and Credit column separately. They should equal the difference between your opening and closing balances plus any fees. If they don't, you missed a column or mis-mapped something.

How Long This Takes
First time setting it up for a new bank: about 25 to 40 minutes depending on how clean their export is. Once the template is built, monthly maintenance drops to roughly 10 to 15 minutes. Import, map, validate, done. That's compared to the 2 to 3 hours I used to spend doing this by hand before I built the template system. If you have more than five accounts to reconcile each month, the time savings compound fast. A template costs you an afternoon to set up properly and then pays you back every single month after that.