Why Most Budget Spreadsheets Are Overcomplicated
The standard approach to personal budgeting is bloated. People build spreadsheets with conditional formatting, data validation dropdowns, dynamic arrays, and charts that refresh every time you change a cell. Then they abandon the thing three weeks later because maintaining it became a part-time job. The bare bones approach strips all of that away and leaves only what actually matters: numbers going in, numbers going out, and whether the result is positive or negative. I built and broke more budget templates than I care to count between 2014 and 2019. The turning point came when I tried to track a freelance income stream that varied between $2,000 and $8,400 per month while also juggling quarterly tax estimates, irregular client reimbursements, and a joint household expense split that changed month to month based on who was home more often. My previous template had so many interconnected sheets that a single typo in a summary tab would cascade across eight other pages and quietly produce the wrong number. I spent forty-five minutes hunting a #REF! error on a Tuesday night. That was the last time I did that to myself.
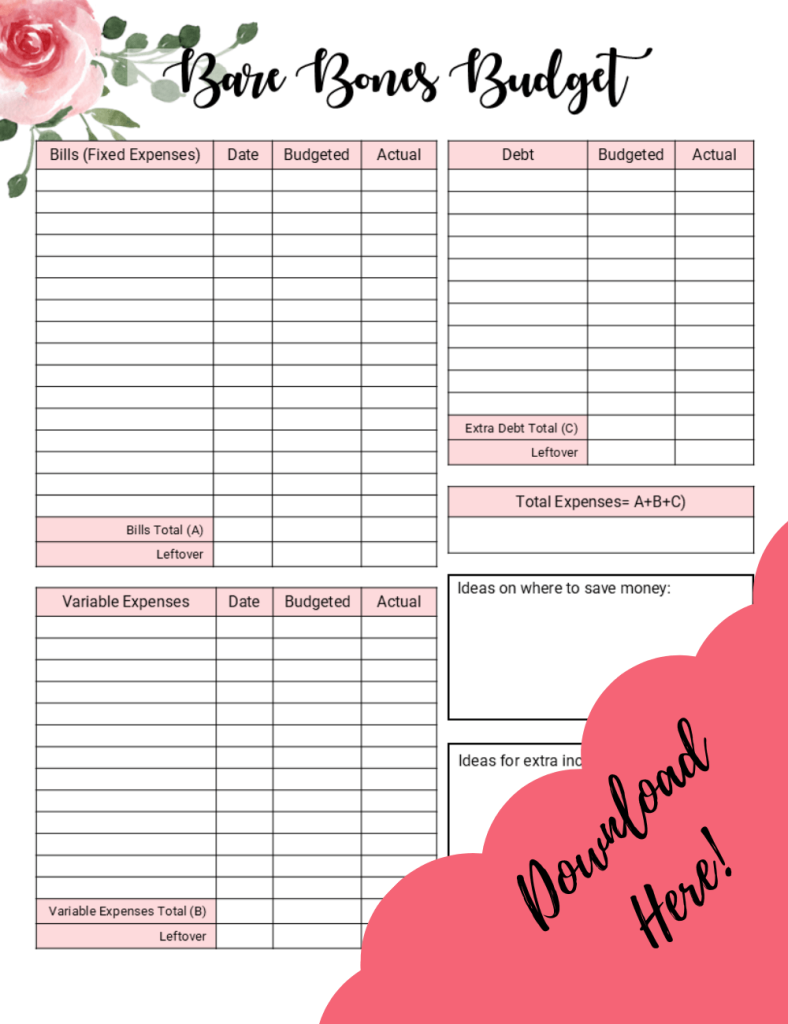
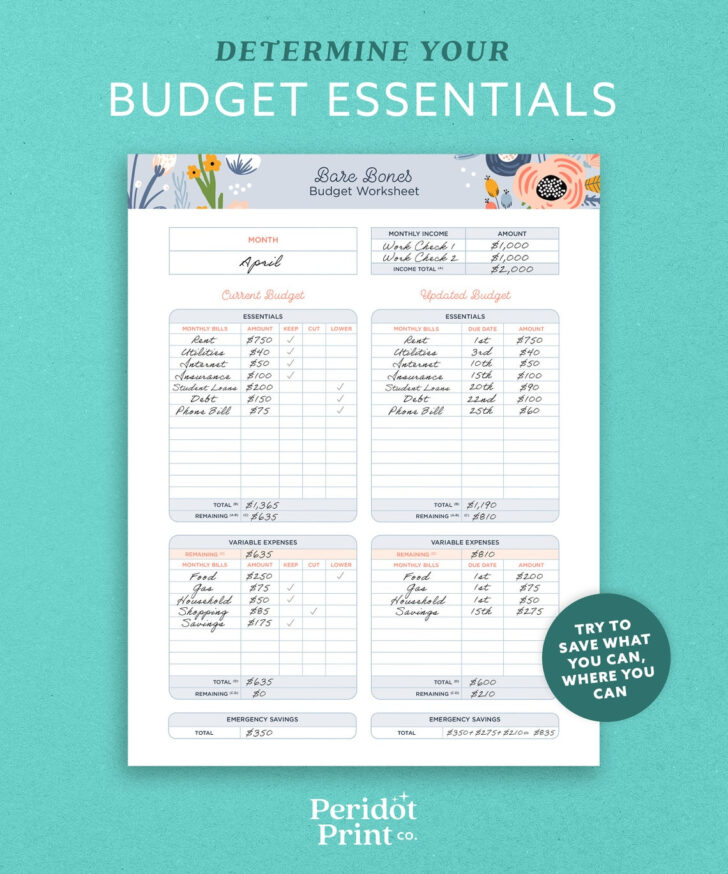
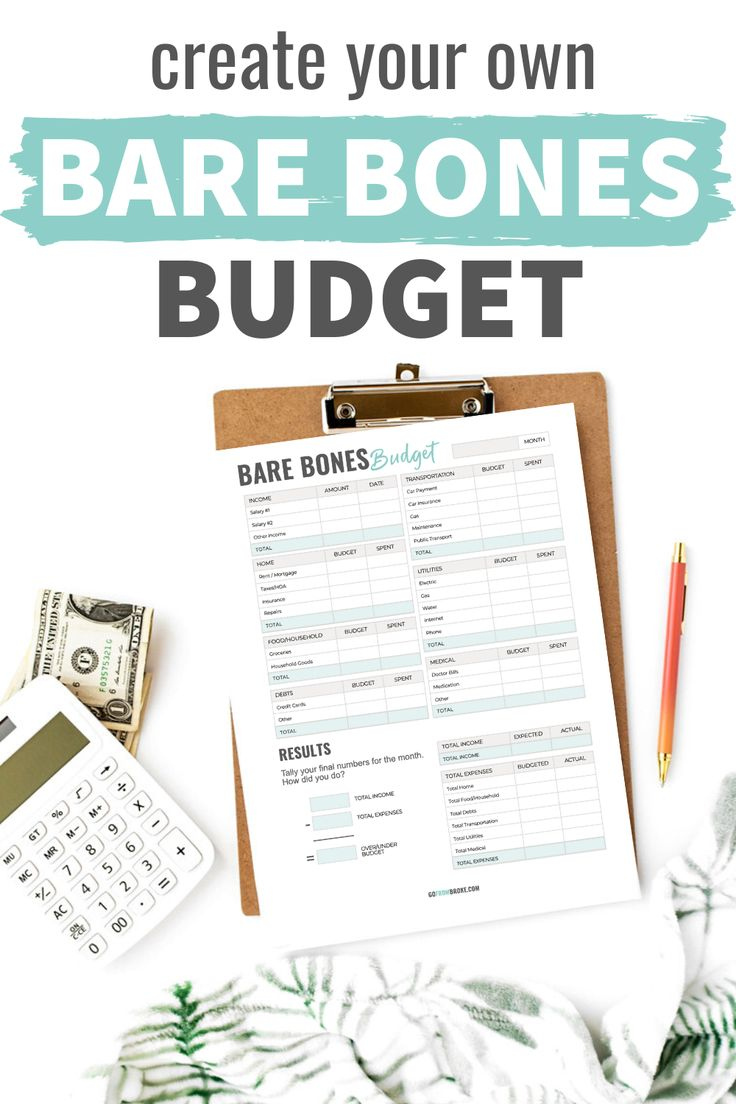
Bare Bones Budget Worksheet
A bare bones budget worksheet is intentionally minimal. It typically contains three sections: income, fixed expenses, and variable expenses. That is it. No nested subtotals, no category roll-ups, no percentage calculations embedded in cells meant for input. You type your numbers into designated rows, and at the bottom you subtract expenses from income. If the result is zero or positive, you are financially functional for that month. If it is negative, you adjust until it is not. The philosophy behind it is straightforward. Budgeting tools fail most often because of friction, not because of missing features. Every extra click, every formula that breaks when you enter a number wrong, every dropdown you have to navigate adds cognitive load. When the tool fights you, you stop using it. A flat, simple sheet removes the fight.
How to Set One Up in Under Fifteen Minutes
Open a blank spreadsheet. This works in Google Sheets, Excel, LibreOffice Calc, or any equivalent. Make column A your labels. Column B is January. Columns C through N are the remaining months. Label row 1 as Month, Row 2 as Income, Row 3 as Rent or Housing, Row 4 as Utilities, Row 5 as Groceries, Row 6 as Transportation, Row 7 as Debt Payments, Row 8 as Insurance, Row 9 as Subscriptions, Row 10 as Entertainment and Dining, Row 11 as Miscellaneous, Row 12 as Total Expenses, and Row 13 as Net Income. That is the entire structure. Now type =B2-SUM(B3:B11) into cell B13. Copy that formula across all twelve month columns. Input your actual numbers into the yellow-highlighted input cells. Everything else calculates automatically. There is nothing else to set up. The total expense formula is deliberately simple. SUM(B3:B11) adds every listed expense without referencing any other sheet or tab. This prevents the kind of broken-link hell that occurs when you accidentally rename a worksheet and a SUMIFS formula silently returns zero instead of an error message. Silent zeros are the worst kind of error in a budget spreadsheet because they look correct until you realize the number is wrong.
Get the Full Details
What Beginners Miss About This Approach
The biggest mistake people make when attempting a bare bones layout is filling it with subtotals and derived percentages. Do not add a row that calculates what percentage of your income goes to rent. Do not create a separate section that totals your discretionary spending. The raw numbers are sufficient. Percentages come later during review, and even then only if you find them useful. The sheet is for tracking, not for analysis. Keep those functions separate if you need them. Another common failure mode is splitting one expense category into too many subcategories. Groceries becomes Produce, Dairy, Meat, Pantry, Snacks, and Cleaning Supplies. This looks organized until you realize you spend approximately twelve seconds deciding what to label a purchase and then give up. One line item per category. If you cannot decide between two categories, pick one and live with it for three months. Your instinct to over-categorize is your brain seeking a false sense of control. Variable income is where people usually hit a wall. If you are salaried, you type the same number into each month and move on. If your income fluctuates, the temptation is to build a complex averaging formula that projects future earnings based on trailing data. Resist that. Enter your best estimate for each month individually. If you guessed wrong, you will notice the deficit immediately instead of weeks later when a moving average smooths the problem into invisibility. Raw estimates exposed upfront are more honest than polished projections that hide volatility.
The Edge Case That Broke My First Template
I once had a client who received an annual bonus in March that made up roughly forty percent of their yearly income. Their monthly expenses were higher in March because of property tax escrow adjustments and a higher car insurance premium that reset annually. In every previous template, the March column looked like a financial crisis because expenses spiked while the budgeted income remained flat. The user panicked and cut back elsewhere, which created a false surplus in the other months and ultimately distorted their understanding of their actual financial position. The fix was trivial but easy to miss. I added two rows at the bottom: one labeled Annual Adjustments and one labeled True Monthly Average. The Annual Adjustments row simply summed the variance between actual income and average monthly income across the year. The True Monthly Average row divided total annual net by twelve and displayed that number in every month column as a reference line. This let the user see both the raw monthly picture and the smoothed baseline without layering complexity into the input section. The input section stayed untouched. Only the reading layer changed.
When a Bare Bones Spreadsheet Actually Fails You
This method assumes you are comfortable with basic arithmetic and have a stable enough financial situation that a single spreadsheet can capture your reality. It does not handle currency conversion, multi-account reconciliation, or investment tracking. If you manage multiple bank accounts across different institutions and need automated syncing, this approach will feel archaic. A dedicated budgeting app with API connections handles that better. It also fails for people who struggle with numerical honesty. A blank spreadsheet with no guardrails will not stop you from underreporting spending. If you need structural accountability, a zero-based budgeting system with mandatory balance checks each period may serve you better. The bare bones model trusts you to be accurate. That trust is its strength and its weakness. Another scenario where this breaks down is multi-person households with highly irregular expense sharing. I encountered a case where two roommates split rent evenly but divided all other costs based on individual usage tracked through a shared receipt app. Putting that into a simple grid required manual adjustment every single month and introduced enough friction that the spreadsheet was abandoned within six weeks. In that situation, a shared expense tracker with per-person ledgers, even if slightly more complex, was the practical choice.

Practical Maintenance Habits
Enter numbers weekly, not monthly. The longer you wait, the more items you forget and the more the exercise turns into reconstruction instead of tracking. Twelve minutes on a Sunday afternoon is manageable. Two hours the first of the month when you realize you missed three weeks of entries is not. Keep the formatting identical each month. Do not change column widths, reorder rows, or add new categories mid-year. Consistency matters more than customization. When you open the sheet in July, you should be able to read January without relearning the structure. If you are downloading an existing template, verify that the formulas are transparent. Open the formula bar and check that each cell references only direct inputs and simple arithmetic. Avoid templates that use INDIRECT, OFFSET, or complex array formulas. Those break unpredictably when you modify the structure. A broken template is worse than no template because it creates false confidence.
A functional Bare Bones Budget Worksheet does not impress anyone. It will look almost insulting in its simplicity to someone accustomed to seeing dashboards with sparklines and conditional color scales. That is the point. The goal is not to impress. The goal is to produce a number you can trust and to keep doing it without burning out.