The Bookkeeping Trap Most Small Business Owners Fall Into
Most small business owners treat accounting like something they need to survive tax season. They buy a spreadsheet template, dump receipts into a shoebox, and try to figure it out in March. That approach works until it doesn't. The first time the IRS asks for documentation you don't have, or your bank account shows money that isn't yours, you realize you've been swimming in shallow water without knowing how deep it actually gets. I ran a small contracting operation for about eight years. The first year, I used QuickBooks Self-Employed on a Sunday night when I couldn't sleep. By year three, I was doing everything in a mess of five different spreadsheets because the software felt like it was working against me. The turning point came when I had a contractor who used his company truck for both job sites and personal errands. He kept a mileage log, sure, but he also bought groceries, paid for his kids' summer camp, and filled up at a random gas station that wasn't near any job site. The issue was that he'd started categorizing everything as "vehicle expense" because that's what felt easiest. When I tried to pull his actual business use percentage, the numbers were all over the place — some months showed 60% business use, others 22%. That inconsistency is the kind of thing that triggers audits. My workaround was simple but tedious: I pulled his actual mileage reports from the truck's onboard computer and cross-referenced them with job site timestamps. This revealed that his real business use hovered around 41%, not the inflated numbers he'd been claiming. The discrepancy saved us from a much larger problem down the line.
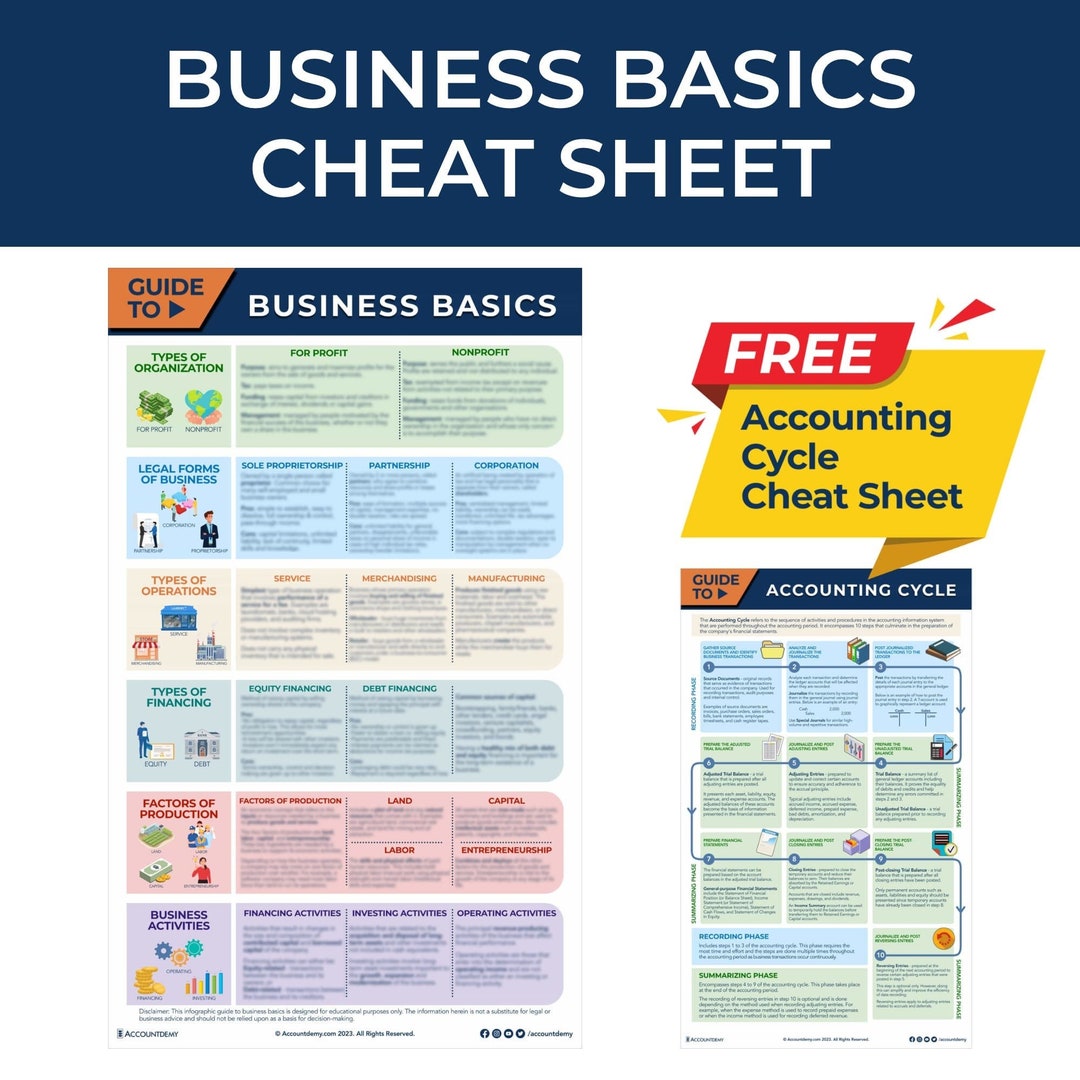
Basic Accounting For Small Business: Why It Matters Before You Think It Does
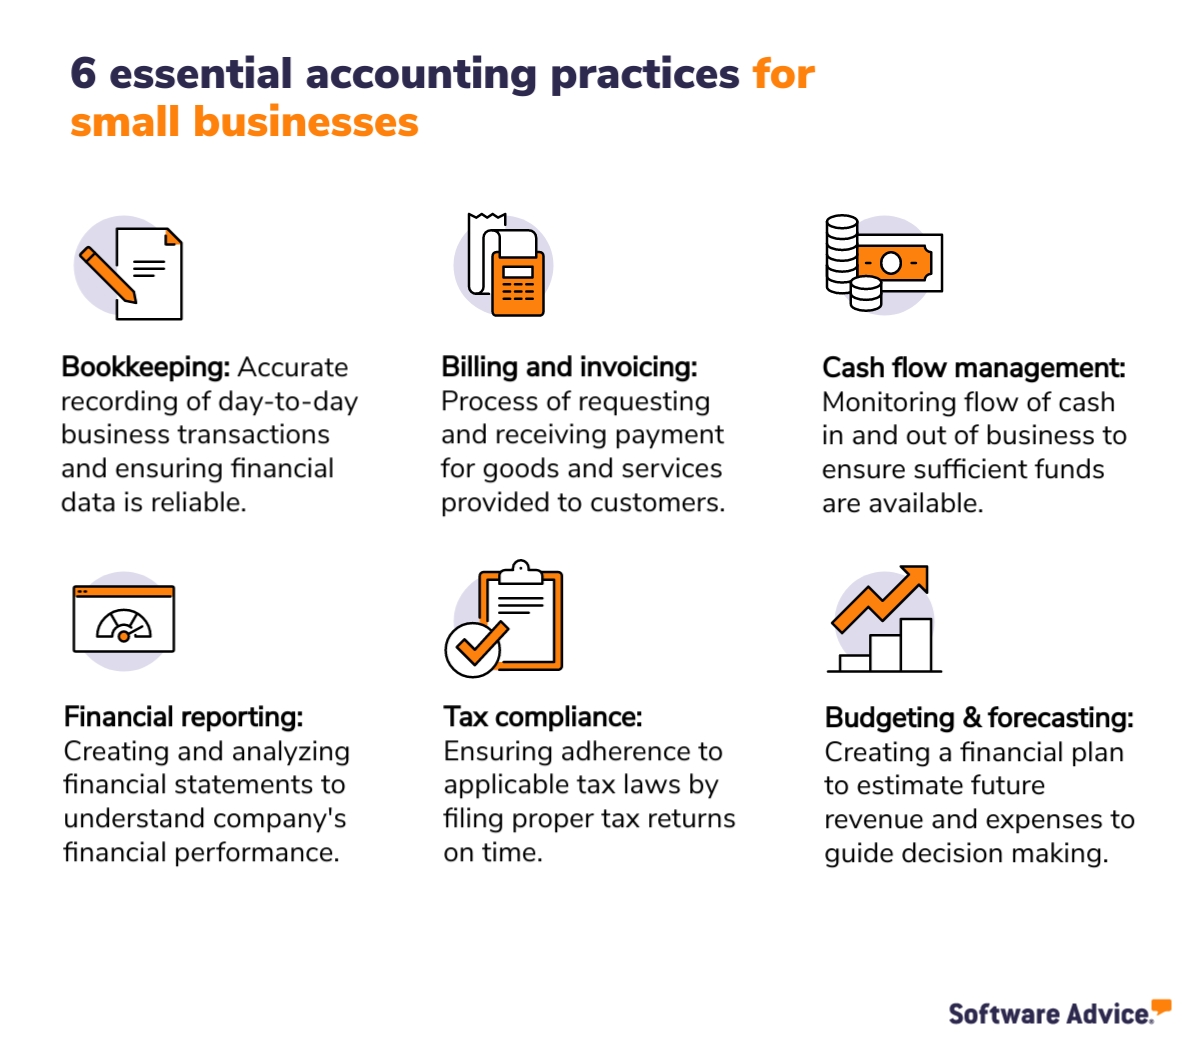
Accounting isn't about making yourself look good to the bank. It's about having a documentable trail that tells you what's actually happening with your money. The difference between looking profitable and being profitable is usually just a matter of cash flow timing. You can have $50,000 in revenue and still not have enough to pay your bills if all of it is tied up in unpaid invoices or inventory. The core mechanics are straightforward. You record every transaction that affects your business finances, categorize it properly, and reconcile everything at the end of each period. That's it. The reason people struggle isn't the concept, it's the consistency. A single missed receipt or misclassified expense compounds over time. Three years of sloppy bookkeeping looks like chaos when you finally try to clean it up.
Setting Up Your System Without Overcomplicating It
Start with a dedicated business checking account. Not a high-yield savings account, not your personal account with a label on it. A checking account. This single decision eliminates about 40% of the headaches people face later. When personal and business funds mix, you spend hours untangling transactions instead of making decisions. Pick one accounting method and stick with it. Cash basis recording means you log income when you receive it and expenses when you pay them. Accrual basis means you log income when you earn it and expenses when you owe them, regardless of when money actually moves. Cash basis is simpler and fine for most small operations under $25 million in gross receipts. Accrual gives you a more accurate picture of your financial health but requires more discipline. I recommend cash basis unless you have inventory or significant accounts receivable. If you're a service business with no inventory, cash basis is usually sufficient and avoids a lot of unnecessary complexity. Choose your software. QuickBooks Online, Xero, FreshBooks — they all do essentially the same thing. Pick the one that costs the least and has the features you actually need. Don't let salespeople convince you that you need the premium tier because you might grow. Growth doesn't change the fundamental accounting process. The Pro tier on most platforms is unnecessary for businesses doing under $1 million in annual revenue.
Get the Full Details

Chart of Accounts: The Structure Everything Else Builds On
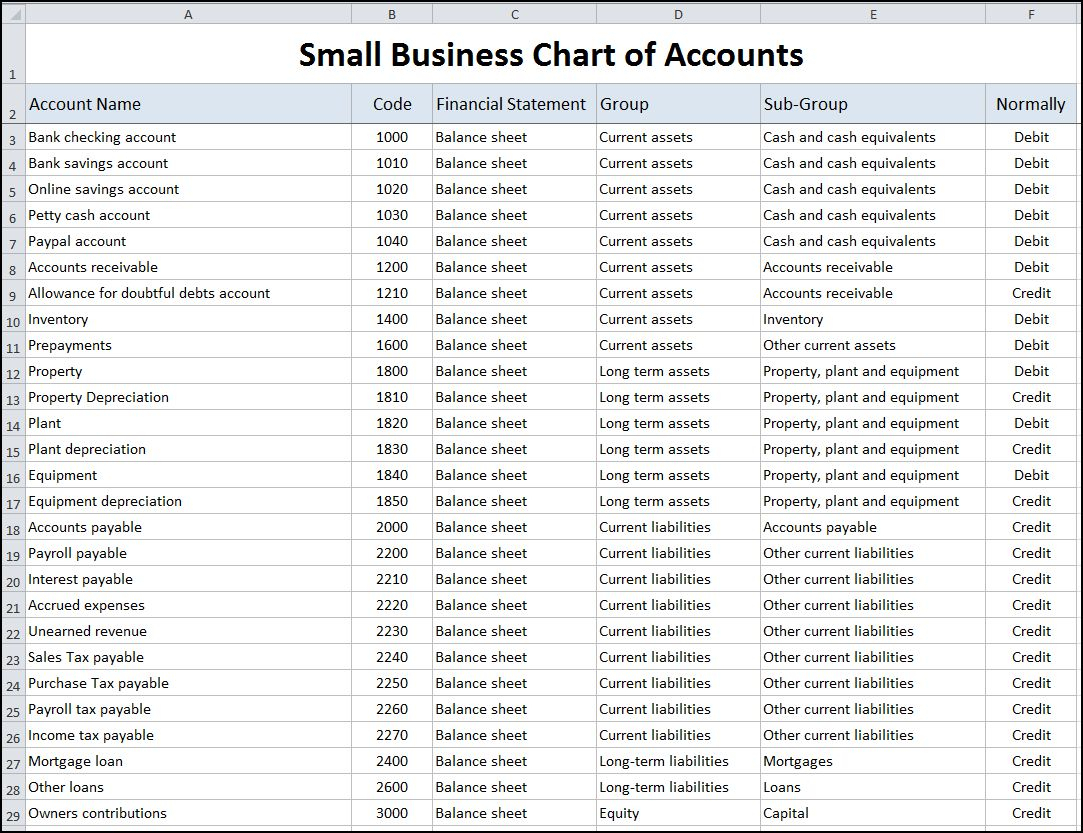
Your chart of accounts is a categorized list of every type of account you'll use. Assets, liabilities, equity, revenue, and expenses. The standard structure uses numbering: assets start with 1000, liabilities with 2000, equity with 3000, revenue with 4000, and expenses with 5000. This isn't a rule you must follow, but it's the convention every accountant expects, and deviating from it just creates confusion later. The detail level matters more than people realize. Don't create twenty different revenue accounts for different clients. One "Service Revenue" account is enough. On the expense side, be specific but not paranoid. "Office Supplies" is a real account. "Postage" is another. "Professional Fees" covers legal and accounting work. Keep it to about 20 to 30 accounts total for a small business. More than that and you'll spend half your time categorizing instead of running your business.
Recording Transactions: The Day-to-Day Reality
Every transaction needs to be recorded within a reasonable timeframe. "Reasonable" means within the week, not within the month. I've seen people batch-process three months of receipts at once, and the errors multiply quickly. A $150 software subscription gets miscategorized as "supplies" when you're rushed and tired. That error might not matter much on its own, but when you have dozens of them stacking up, your profit and loss statement starts looking nothing like reality. Receipts are documentation, not decoration. A screenshot of a credit card statement is not a receipt. You need the actual invoice or receipt that shows the vendor name, date, amount, and what was purchased. The IRS accepts digital copies stored in cloud folders. I use a system where I upload receipts to a shared Google Drive folder organized by month and vendor. This takes about two minutes per transaction if you're disciplined about it. Bank feeds are your friend, but they're not perfect. Most modern accounting software connects directly to your bank and imports transactions automatically. This saves maybe 90 minutes of manual entry per month for a typical small business. The catch is that bank feeds pull descriptions as-is, which means "AMAZON.COM" and "AMZN digital services" and "AMZN Digital Svcs" might all appear as separate line items. You need to clean these up regularly. Set aside 30 minutes each Friday to match and categorize incoming transactions.
Reconciliation: The Step Everyone Skips Until It Hurts
Reconciliation means comparing your accounting records against your bank statements to make sure they match. You do this monthly. If you skip it, errors accumulate silently. A duplicated expense here, a missing transaction there, and suddenly your books show $8,000 more than you actually have. I learned this the hard way when a bank fee posted twice in my system for six consecutive months. That's $72 in phantom expenses that dragged down my reported profit without me noticing. The reconciliation process is mechanical. Open your bank statement, open your accounting software, and go through each transaction. Check off the ones that match. Investigate the ones that don't. If your ending balance doesn't match after checking everything, you have an unresolved difference. Don't force it to match. Find the discrepancy. Missing transactions, duplicate entries, and timing differences are the usual suspects.

Cash Flow Management: Where Businesses Actually Die
Profit and cash flow are different things. A business can be profitable and still go bankrupt because it runs out of cash. This happens constantly. You invoice a client for $10,000, record the revenue, and your P&L looks great. But the client pays in 60 days. During those 60 days, you still have to pay rent, payroll, and suppliers. Your bank account empties even though you're technically profitable. Track your cash flow separately from your profit and loss statement. A cash flow forecast doesn't need to be elaborate. Project your expected income and expenses for the next 30 days. If you're expecting a slow period, arrange a line of credit before you need it. Getting approved for credit when you're already struggling financially is significantly harder than getting approved when you're doing fine.
Tax Preparation: What Actually Saves Money
Most small business owners leave money on the table because they don't claim deductions they're entitled to, or they claim things they shouldn't. Common legitimate deductions include home office expense (a simplified method of $5 per square foot up to 300 square feet, or the regular method requiring actual expense breakdown), mileage, health insurance premiums for self-employed individuals, and a portion of your phone and internet bills used for business. The qualified business income deduction (QBI) allows many pass-through business owners to deduct up to 20% of their qualified business income from their taxes. This is a significant deduction introduced by the TCJA that expires after 2025 unless extended. It doesn't apply to everyone. Service businesses in certain professions hit income phase-out limits. Understanding the specifics here matters more than blindly applying a flat percentage. I once worked with a client who was paying an accountant $3,000 a year but was missing nearly $8,000 in potential deductions. The main culprit was self-employment tax planning. His accountant hadn't set up a SEP-IRA or a Solo 401(k), which would have both reduced his taxable income and built retirement savings. This isn't a bookkeeping error. It's a strategic gap that proper accounting setup can surface early.
When Your Setup Breaks Down
Small business accounting has real limitations. Software tools assume you have clean, organized transactions. They don't handle irregular income well. If you're a consultant with three months of no work followed by a $40,000 project, your monthly financial statements will look erratic. The software produces accurate numbers, but the narrative they tell is misleading. You'll need to add context manually or accept that your P&L will show volatile swings that don't reflect actual business health. Cash basis accounting fails when you have significant receivables or payables. If you regularly wait 90 days for clients to pay and your suppliers want payment in 30, cash basis gives you a dangerously optimistic view of your financial position. The money you think you have isn't actually available. Switching to accrual in this scenario is the right move, even if it adds complexity. There's also a point where doing it yourself stops being cost-effective. If you're spending more than five hours per week on bookkeeping, you're probably better off hiring someone. At that threshold, the opportunity cost of your time exceeds what a bookkeeper would charge, and the quality of your records likely improves. I stopped doing my own books when my revenue grew large enough that every hour spent categorizing transactions was an hour not spent on client work or business development.
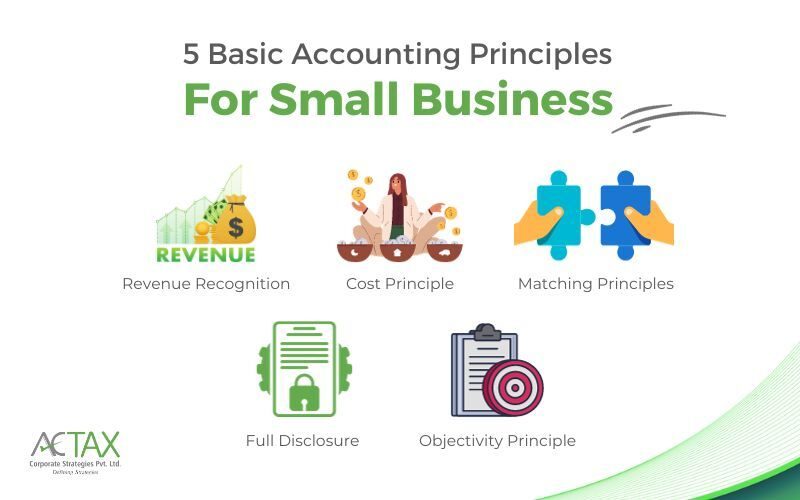
The foundation you build now determines how much pain you'll experience later. Starting with a clean system, consistent habits, and realistic expectations will save you hundreds of hours and thousands of dollars over the life of your business. The work is tedious, but the alternative is significantly worse.