Why We Still Use This Thing
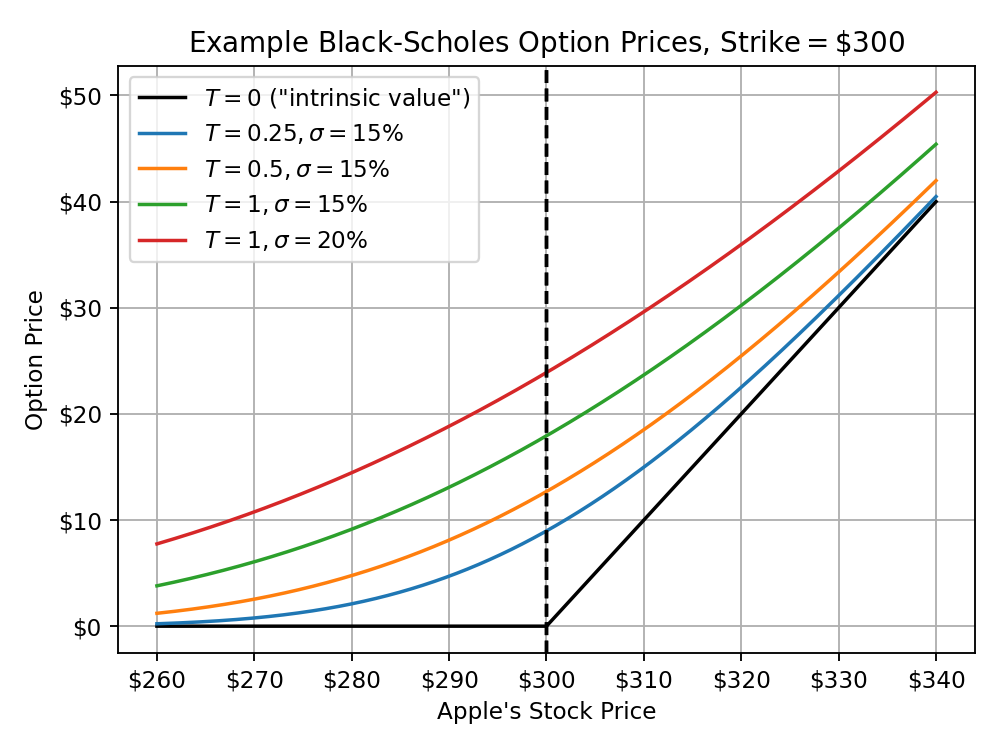
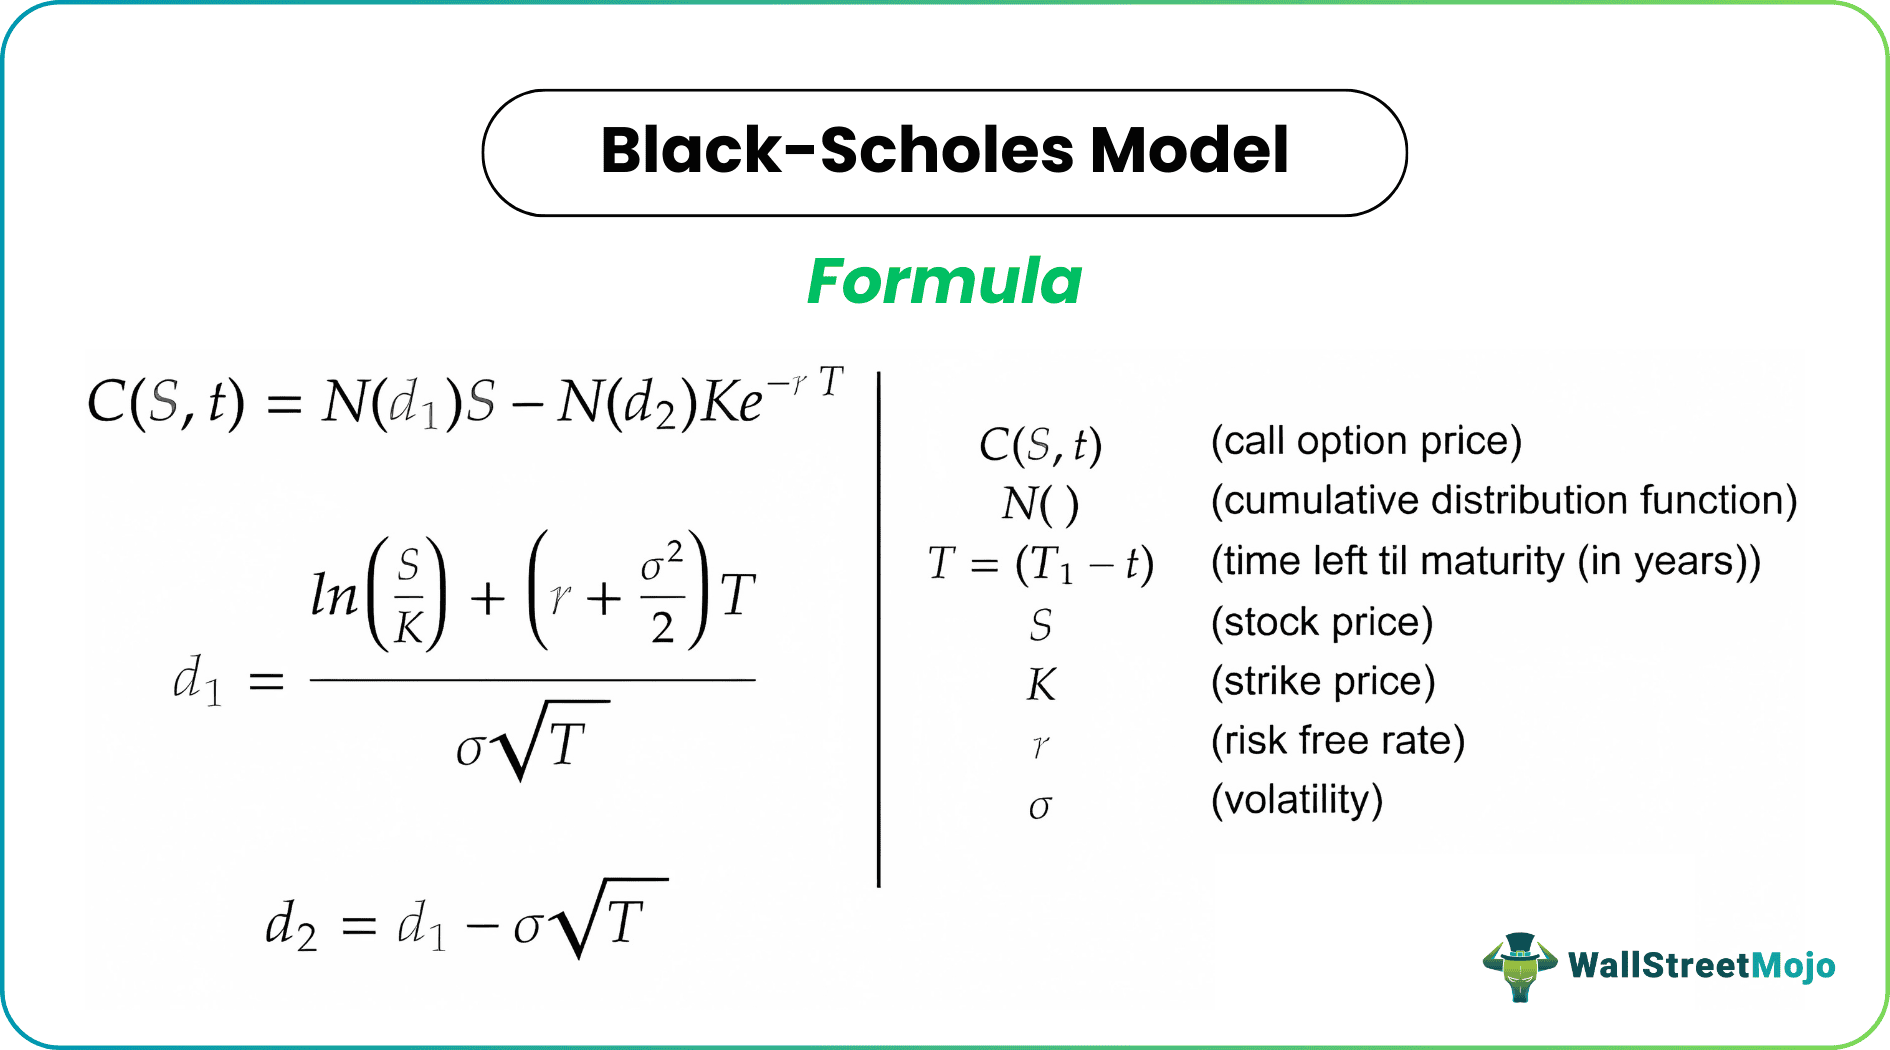
The Black-Scholes formula is the first thing anyone learns in options pricing and honestly the last thing you should rely on blindly. It gives you a fair theoretical price for European-style options under a specific set of assumptions, and those assumptions are wrong almost all the time. That does not make it useless, though. It makes it a benchmark and a starting point for how traders actually think about volatility and option value. When you hear someone talk about Basic Black Scholes Option Pricing And Trading they are usually referring to a two-part process: calculating a theoretical price and implied volatility from market data, then using that to decide whether a specific contract is mispriced relative to your own view of where the underlying is heading. The math is straightforward enough, but the trading application is where people run into trouble. The call option price is N(d1) times the spot price minus N(d2) times the present value of the strike price. N is the cumulative normal distribution, and d1 and d2 are functions of volatility, time to expiry, the risk-free rate, the spot, and the strike. The put formula follows the same structure. In practice, nobody derives this by hand on a trading day. You use it through a spreadsheet, a script, or a pricing tool.
The more useful output is not the raw price. It is the implied volatility. If you plug in the actual market price of an option and solve for the volatility input, you get the IV. Traders spend most of their time comparing that IV to their own forecast of realized volatility. The difference is the edge.
What the Model Actually Assumes
The model assumes constant volatility across all strikes and maturities. It assumes log-normal price distributions. It assumes no dividends unless you adjust for them. It assumes frictionless markets with no transaction costs. It assumes you can trade continuously. Any of these being wrong will push your calculated price away from reality, especially for short-dated or deep out-of-the-money options. The skew you see in real markets exists because all of these assumptions are approximately false simultaneously. I keep a simple Python script that takes the five inputs: spot price, strike, days to expiration, risk-free rate, and volatility. I use the scipy.stats.norm package for the normal cumulative distribution function, and I convert days to years by dividing by 365. For dividends I subtract the continuous dividend yield from the spot before running the formula. The script outputs the call and put prices plus the implied volatility if you feed it a market price instead of a vol input. This usually cuts the process down from twenty minutes to about thirty seconds once the template is set up. If you want something simpler than a script, a Google Sheet with the NORM.S.DIST function and the standard d1 and d2 setup works fine. Put spot, strike, days, rate, and vol in the top row. Calculate d1 and d2 in the next rows. Then compute the call and put prices below that. It takes maybe five minutes to build and you can reuse it indefinitely.
Get the Full Details

How Traders Actually Use It
The primary trading application is volatility trading, not directional trading. If your model says implied vol should be twenty percent based on the option price you see, and you believe realized vol over the life of the option will be twenty-five percent, you buy the option. If you think realized vol will be fifteen percent, you sell it. The directional component is secondary. You hedge delta when needed, but the core bet is on volatility. I track a simple metric: my estimated realized vol over the past twenty days annualized, compared to the implied vol of a nearby ATM option. When the gap is wide, I look for trades. When the spread is tight, I usually sit on my hands. Most amateurs chase small spreads and lose money on theta and bid-ask costs. The big profitable moments tend to come when there is a clear disconnect between IV and what you think will actually happen.
A Real Problem I Faced
Once I ran my Black-Scholes calculation on an earnings event where the stock had just paid an unusual dividend right before expiration. The model price was off by several percent compared to the actual market price, and I could not figure out why at first. The issue was that the market was pricing in the dividend separately from the volatility skew. My script was using a standard continuous dividend yield and missing the discrete jump. I fixed it by adjusting the spot price downward by the present value of the upcoming dividend before plugging it into the formula. After that adjustment, the prices matched the market much better. That was a specific case where the basic model needed a manual adjustment and the fix was obvious once I traced the discrepancy back to the dividend timing. The biggest mistake beginners make is treating Black-Scholes output as a precise price rather than a reference point. The second mistake is ignoring the bid-ask spread. An option priced slightly above the theoretical value looks like a good buy until you factor in that you cannot sell it at theoretical price. The spread alone can erase the edge. The third mistake is using implied volatility from a single option and assuming it applies to other strikes and expirations. It does not. The vol surface is real and it changes daily. Another issue is the treatment of the risk-free rate. People either ignore it or use the wrong rate. Use the actual rate for the relevant maturity, typically the Treasury yield matching your option expiration. It is a small number but it moves the price enough to matter when you are trying to identify small mispricings.
When the Model Breaks Down
Black-Scholes performs poorly for American-style options on stocks with large dividends. It also struggles with far OTM options where the normal distribution assumption about price returns is clearly violated. Real markets show fat tails. The model will underprice crashes and overprice calm periods. If you are trading deep out-of-the-money puts as tail hedges, do not rely on the theoretical price as a fair value benchmark. You are paying for insurance, not exploiting a mispricing. The price reflects risk aversion and demand, not just probability. Set up your inputs. Spot, strike, days to expiry, risk-free rate, and a baseline vol estimate. Calculate the theoretical price. Compare it to the mid-market price. If the difference is larger than your transaction costs plus a reasonable buffer, you have a potential trade. Size the position based on your vol edge and your risk tolerance, not on the raw price difference. Monitor delta and gamma as the option moves toward expiration. Close or roll the position before gamma risk becomes unmanageable, especially on short-dated options. Keep a log of your trades with the IV you traded at and the realized vol that followed. Review it monthly. This is the part most people skip. Without tracking outcomes you cannot tell whether your vol forecasts are improving or drifting worse over time. I have seen traders repeat the same mistakes for years because they never looked at the actual PnL tied to their vol estimates.

What to Do Instead When Black-Scholes Is Not Enough
For American options, binomial models give you more realistic pricing when early exercise matters. For directional traders who want something simpler, I sometimes use a basic Black-Scholes calculator for reference but rely on technical context and sentiment for entry decisions. The model is a tool, not a system. The best use of it is as a quick check on whether the market is pricing in something you do not see yet.