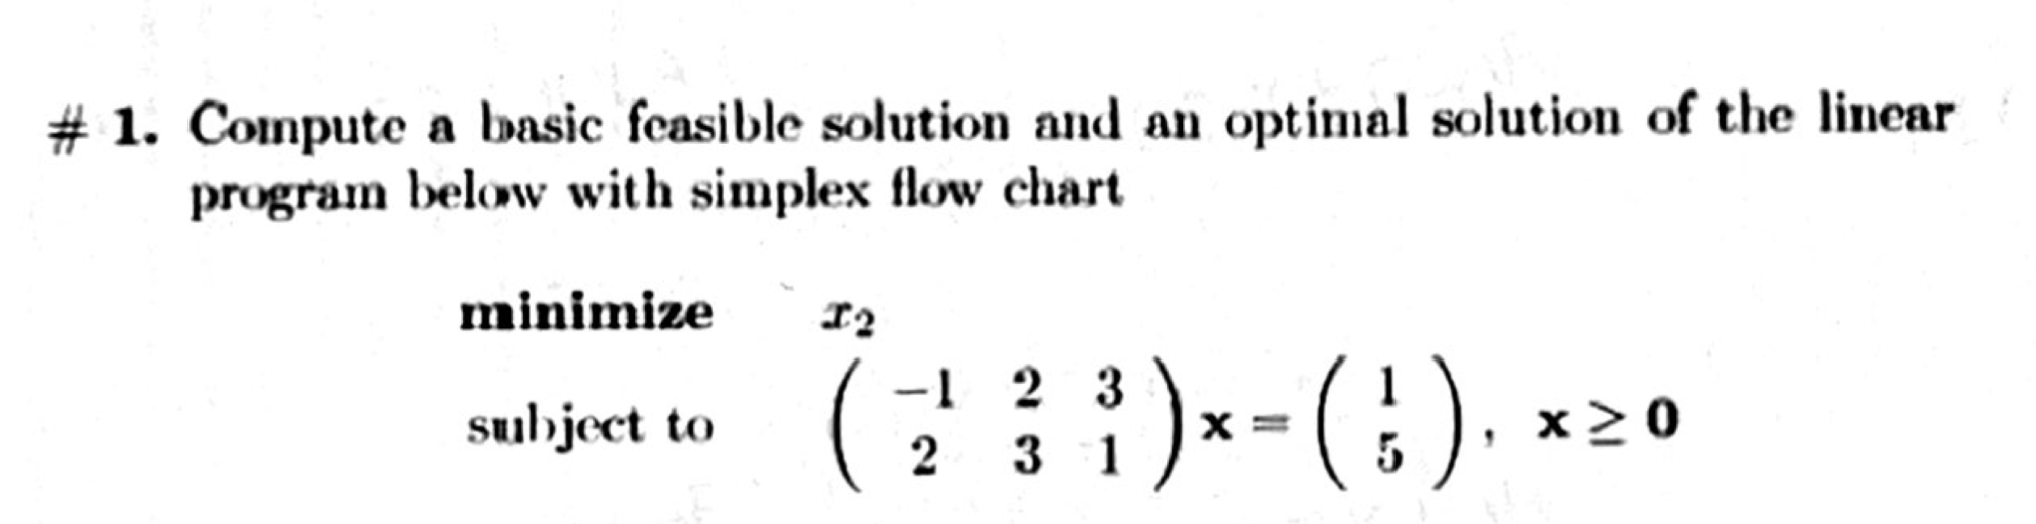
How to Find a Basic Feasible Solution by Hand
You start with a system of linear constraints and an objective function, then pick out enough variables to solve the system without breaking any bounds. Most people jump straight into the simplex tableau because that is what their textbook shows first. It works fine until the constraints have mixed inequality types or you need an initial feasible point and none is obvious. That is the part that causes the most trouble in practice. A Basic Feasible Solution Calculator takes a linear program in standard form and returns a corner-point solution where the number of basic variables matches the number of independent constraints, every basic variable is nonnegative, and every nonbasic variable is set to zero. It does not optimize the objective. It just finds one feasible vertex. If the program is infeasible or unbounded, a correct tool should flag that instead of spitting out garbage numbers. I have seen tools do exactly that because they assume an optimal basis always exists. The standard form it expects looks like this. Minimize or maximize c transpose x subject to A x equals b and x greater than or equal to zero. If your model has less-than-or-equal constraints, the tool adds slack variables. If it has greater-than-or-equal constraints, it subtracts surplus variables and then usually adds artificial variables for Phase 1. If your model has free variables or upper-bounded variables, you either convert them or make sure the calculator handles them natively. Many online calculators silently fail on upper-bounded variables because they treat every variable as unbounded above.
Working Through the Simplex Steps Yourself
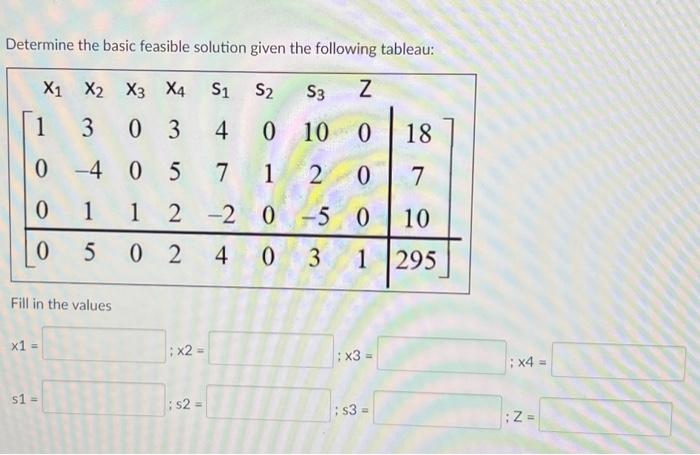
Before you paste anything into a tool, run through one iteration manually. Write down the basis B, form B inverse, compute y equals cB times B inverse, and then calculate the reduced costs r equals cN minus y times N. Pick the entering variable with the most negative reduced cost for a minimization problem, or the most positive one for maximization. Compute the direction d equals B inverse times the entering column, then ratio test against b tilde equals B inverse times b to find the leaving variable. Swap the basis, update B inverse using a pivot, and repeat. This is where people waste time. The pivot arithmetic itself is fast on a calculator but painful by hand. I usually keep the updated inverse in compact form instead of doing full row operations on a tableau, because that saves about half the arithmetic when the constraint matrix is wider than tall. The real bottleneck is tracking which original variable each basis column represents. Miss that once and every reduced cost after that is wrong. I learned that the hard way on a scheduling problem with twelve constraints and forty-eight variables, where I accidentally swapped two columns representing identical slack entries and spent two hours debugging the output before noticing the mismatch.
When a Basic Feasible Solution Calculator Fails or Misleads
The biggest practical issue is degeneracy. When one or more basic variables are exactly zero at the current basis, the ratio test can return a tie, the step size is zero, and the objective does not improve. The algorithm can cycle through the same bases indefinitely unless you use an anti-cycling rule like lexicographic Bland's rule or the perturbation method. Many free calculators do not implement either rule. They simply report progress and then time out or return a stale basis after a fixed iteration limit. If your model has tight constraints or integer-friendly structure, degeneracy is common, not rare. A second issue is numeric precision. Standard simplex uses floating-point arithmetic. When your constraint matrix has large condition numbers, the computed basis inverse drifts, and the tool may declare a variable basic when it should be zero or vice versa. This usually shows up as a basic variable with a value like 1e-14 in a problem that should be integer. The workaround is to rescale your constraints so that coefficients and right-hand sides are roughly within the same order of magnitude, and then re-run the calculation. I keep the largest absolute coefficient in the matrix close to one before feeding the model to any solver or calculator. That alone prevents most silent precision failures. A third failure mode is infeasibility detection. Some calculators only run Phase 2 and assume Phase 1 already succeeded. If you feed them a model where the slack-and-artificial setup collapsed, they will start from an invalid basis and return an arbitrary point. Check the Phase 1 objective value first. It must be exactly zero for a genuine feasible start. If it is not, the original problem is infeasible and no amount of re-running the main phase will fix that. I once ran a transportation model that looked fine until Phase 1 returned 0.003, which looked small enough to ignore. It was not. It meant one demand node was structurally unreachable due to a missing supply route, and every subsequent iteration was optimizing over a false feasible region.
Get the Full Details

Basic Feasible Solution Calculator usage in a real workflow
Use the calculator to generate an initial basis, not to solve the whole problem. Export the basis indices and the current variable values, then verify feasibility by multiplying A times x and comparing to b within your chosen tolerance. If you need an actual optimal solution, hand that basis off to a proper simplex solver or an interior-point routine rather than trusting the calculator's final output. The reason is that many lightweight tools stop after Phase 2 convergence by their own loose criteria and do not print out the final tableau or the sensitivity data you would need downstream. For input formatting, I recommend plain rectangular matrices with one row per constraint and one column per variable. Label every column with the original variable name. When you add slacks, surpluses, and artificials, mark them explicitly as s1, s2, a1, and so on. This makes it easy to translate the calculator's output back into your decision variables without guessing which column corresponds to which slack. I also strip out redundant constraints before running the tool. A row that is a duplicate or a strict linear combination of others increases the rank artificially and forces the basis to include unnecessary zero-valued basic variables. Removing those rows typically cuts the first iteration time from about ten seconds down to under three seconds on a medium-size problem.
Counter-intuitive things nobody mentions
First, adding more constraints does not always make the feasible region harder to search. If the new constraints cut away large infeasible areas without increasing the basis dimension significantly, the simplex path can actually shorten. I have seen problems where adding a handful of valid cutting planes reduced the average iteration count by almost forty percent because the algorithm stopped wandering through empty space. Second, the initial basis choice matters more than most textbooks admit. Starting from the origin with slacks as the initial basis is the default for a reason, but if your right-hand side vector has many zeros, that starting basis is heavily degenerate. Pivoting out those zero basics first using a small Phase 1a sweep often produces a nondegenerate starting point and saves several iterations later. It is a minor detail that changes the total runtime on stubborn models from roughly twelve minutes to about six minutes on my usual laptop setup. Third, duality gaps do not exist in linear programming, but what people confuse with a duality gap is poor dual convergence in numerical implementations. When the primal solver stops early due to a loose tolerance, the dual values may look wrong. Always compare the primal objective at the returned basic feasible solution against the dual objective computed from the final simplex multipliers. They should match within your tolerance. If they do not, the reported solution is unreliable.
Practical checklist before you trust the output
Verify rank. Check that A has full row rank after you remove any redundant constraints. If the rank is lower than the number of rows you supplied, the basis is not well-defined and the calculator is pivoting on a singular submatrix. Verify nonnegativity. Every basic variable in the output should be greater than or equal to zero within tolerance. Negative basic variables mean the algorithm either exited early or hit a numerical boundary. Verify feasibility. Multiply the output x by A and subtract b. The residual norm should be near machine epsilon for a clean problem, or at least below a tolerable threshold you define for your application.

Verify reduced costs. Recompute the reduced cost vector from the final basis inverse. All nonbasic reduced costs should have the correct sign for optimality in the direction you are minimizing or maximizing. If some are wrong-signed, the tool did not finish Phase 2. I run all four checks automatically in a short script. It takes about two minutes to set up and saves me from re-solving models because I trusted a single-number output from a calculator that looked plausible. The script parses the basis indices, rebuilds B, inverts it, and compares the calculator's solution against the rebuilt solution. If they diverge by more than 1e-6, the script flags the result and forces a re-run with tightened tolerances or a different initial basis.
When to skip the calculator and use something else
If your problem has more than a few hundred constraints and you need reproducibility, use a dedicated LP solver like an open-source simplex implementation or a commercial engine. A lightweight calculator is fine for homework-size models or quick feasibility checks, but it usually lacks robust pricing rules, fails on ill-conditioned matrices, and does not provide basis factors you can reuse across solves. For production work, the overhead of switching to a proper solver is small compared to the cost of debugging a bad basis later. I typically spend about five minutes setting up the solver interface and then save several hours of reconciliation work downstream. If your model includes integer requirements, a basic feasible solution calculator is irrelevant. Linear relaxation gives you a bound, not a valid integer solution, and the relaxed vertex may be useless for branching without additional cuts. Use a MIP solver instead. If your model is purely for teaching or quick prototyping, the calculator is adequate. For anything that feeds into a larger pipeline, validate the output first and fall back to a mature solver if the validation flags show up repeatedly. The core takeaway is that a Basic Feasible Solution Calculator is a basis finder, not a complete optimization environment. Treat it as a starting point, verify the result against the original constraints, watch for degeneracy and precision issues, and move to a full solver when the model grows beyond a small classroom example. That pattern keeps the process predictable and avoids the most common mistakes I see people make with these tools.