Working Through Berk Demarzo Chapter 4: The NPV Rule and Valuation Decisions
Chapter 4 is where most students realize they actually need to pay attention. The chapter covers the net present value rule, how to value cash flow streams, and the distinction between NPV and IRR when making investment decisions. It sounds straightforward until you start doing the problem sets. The core framework is simple enough. You discount future cash flows at the appropriate cost of capital and subtract the initial outlay. If the result is positive, the project adds value. If it is negative, you walk away. That is the entire chapter in one sentence. The problem is that the chapter is actually full of nuances around compounding frequency, equivalent annual annuities, timing of cash flows, and when NPV and IRR will give you conflicting answers.
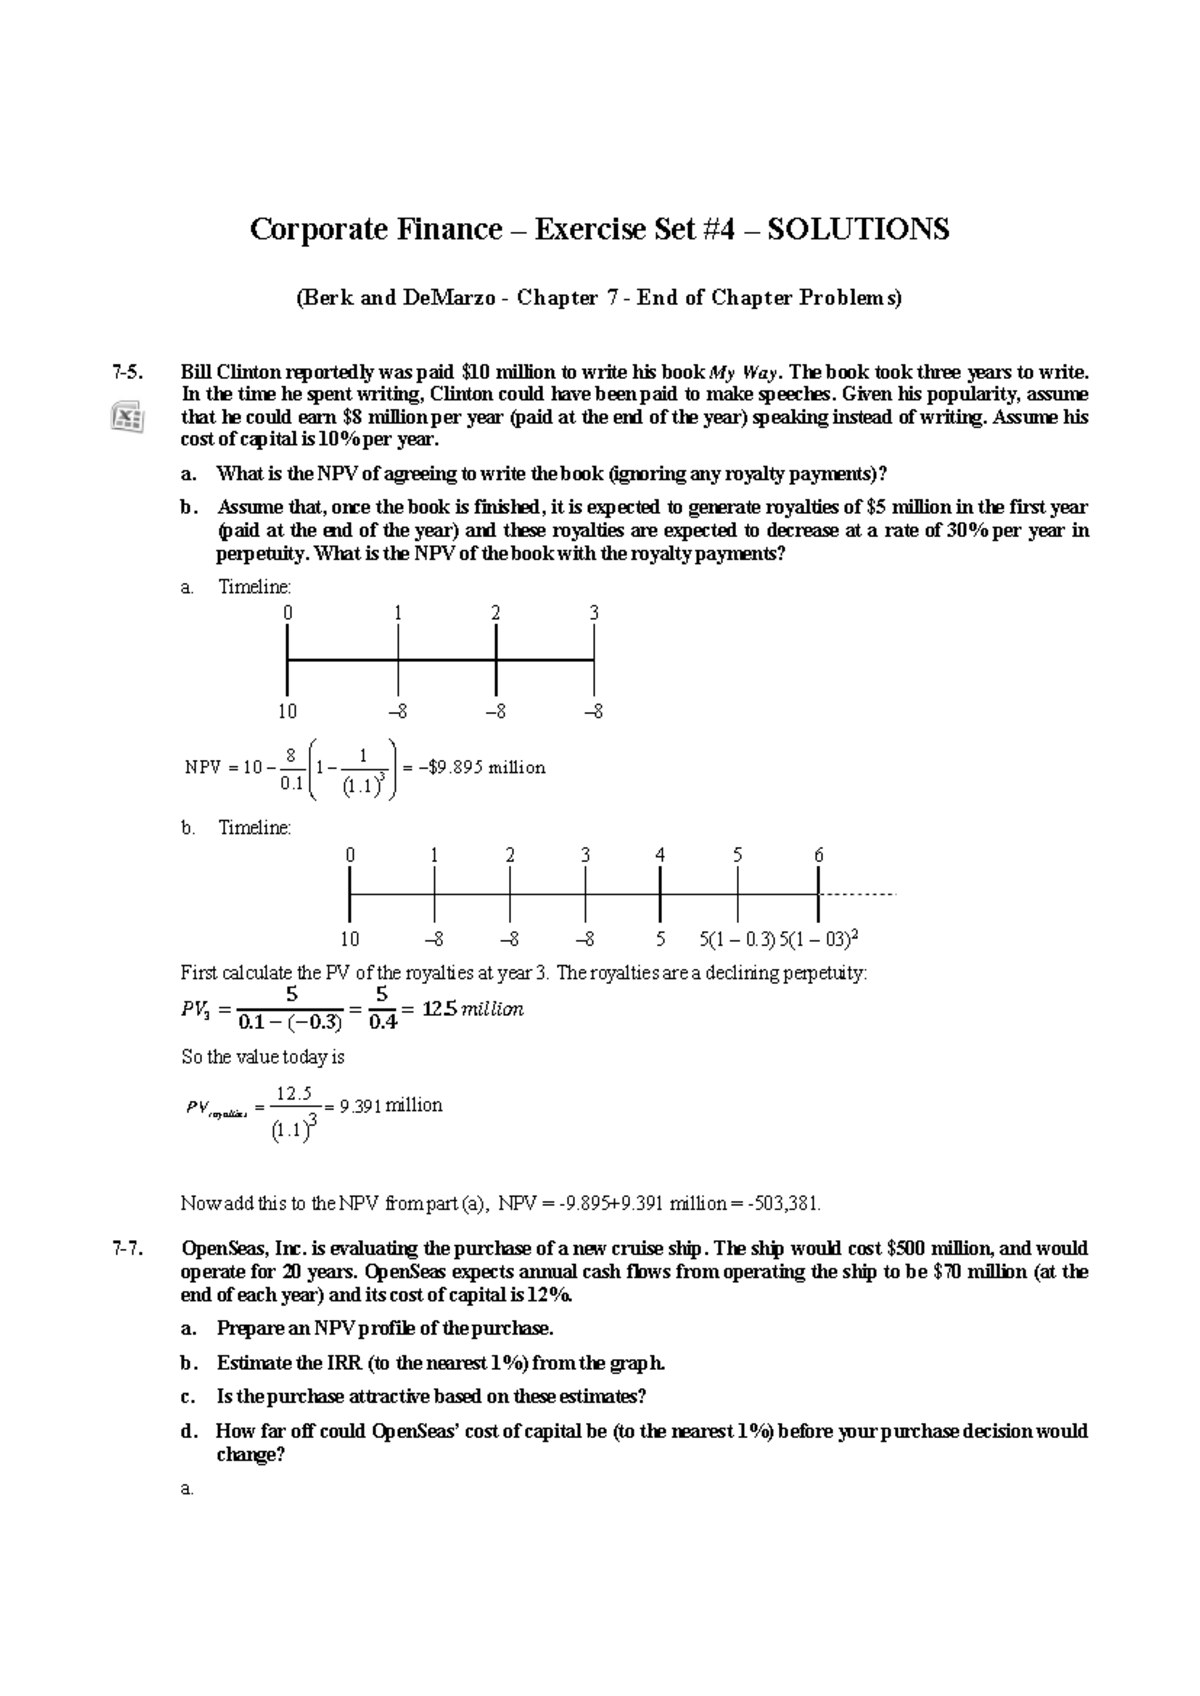
Berk Demarzo Corporate Finance Solutions Ch 4
When you are working through the solution sets for this chapter, you will run into a specific edge case that the textbook glosses over pretty quickly. It is in the IRR vs NPV ranking conflict section. You get a set of mutually exclusive projects where the cash flow patterns are non-conventional, meaning there are multiple sign changes in the cash flow timeline. I remember hitting this exact problem on a practice set about two years ago when I was tutoring undergrads. The IRR calculation spat out two different rates because of the sign flip, and the textbook solution manual barely acknowledged the issue. It just told you to fall back on NPV and move on. That answer is technically correct but it leaves you confused about what actually happened. The workaround is to plot the NPV profile. You calculate NPV at several discount rates, say 0%, 10%, 20%, 30%, and 50%, and you graph them. When you see the curve cross the horizontal axis twice, you know you have multiple IRRs. In that situation, you use the modified internal rate of return, or MIRR, which assumes reinvestment at the cost of capital rather than at the IRR itself. The textbook mentions MIRR in a footnote almost as an afterthought. It shows up in problems 4.23 through 4.28 depending on the edition, and it is not worth your time to master it unless your professor actually tests on it. Stick to NPV for ranking conflicts. It is the only method that does not break when cash flows get weird. Another thing most people miss when they first read this chapter is the difference between nominal and real cash flows. The Berk Demarzo treatment is decent but it assumes you already know how to adjust for inflation properly. Here is what I have found from actually doing these calculations: if you are given a nominal discount rate and real cash flows, you cannot just plug them together. You either convert the nominal rate to a real rate using the Fisher equation, or you inflate the cash flows to nominal terms first. Most students forget step one and just discount nominal cash flows with a nominal rate without adjusting the growth assumptions. That double counts inflation and gives you a wildly wrong NPV. I had a student once who got the answer wrong by nearly forty percent because he used a five percent real growth assumption with an eight percent nominal discount rate without converting anything. The gap between the nominal and real approach was huge, and he had no idea where he went wrong.
Equivalent annual annuity is the other topic in this chapter that deserves more attention than it gets. You encounter it when comparing projects with different lifespans. You calculate the NPV of each project and then convert that NPV into an annuity payment over the project's life using the annuity factor. The project with the higher EAA wins. The trap here is that students sometimes use the wrong compounding period for the annuity factor. If the cash flows are quarterly but you are using an annual discount rate, you need to either convert the rate or convert the cash flows. Mixing periods is the most common arithmetic error I see in these solution sets, and it shows up repeatedly in the problem bank. There is also a practical limitation to the NPV rule itself that the chapter does not stress enough. NPV assumes you can reinvest intermediate cash flows at the discount rate you chose. In the real world, that assumption rarely holds. A discount rate of ten percent is a hurdle rate for acceptance, not necessarily a realistic reinvestment rate. This is another reason why IRR can be misleading beyond just the multiple roots problem. The MIRR fixes part of this, but neither method addresses the fundamental issue that your reinvestment environment may shift over the life of the project. If you are working on a multi-year infrastructure project with a fifteen-year horizon, the discount rate you pick today may not reflect the rate environment in year seven through fifteen. NPV still beats the alternatives, but you should be aware that the number coming out of your calculator rests on a fairly shaky assumption. If you are looking for Berk Demarzo Corporate Finance Solutions Ch 4, most legitimate sources host the solution manual through the publisher or through university course reserves. You will find PDF versions scattered across study document sites and academic sharing platforms, but I would caution against relying on any single source without cross-checking. The solution manuals have errata, and different editions of the textbook have different problem numbering. A solution from the third edition will not always map cleanly to the fourth. I learned that the hard way when I assigned problem 4.15 from one edition and the posted solution was for a different version with different numbers. You should always verify that the cash flow figures in the solution match the problem statement exactly before you trust the final answer.
Get the Full Details
The chapter also introduces the concept of opportunity cost in capital budgeting, and this is where many students lose points. When a firm uses an existing asset for a new project, the foregone market value of that asset is an opportunity cost that must be included in the initial investment. The textbook example with the warehouse is clear, but the harder problems hide the opportunity cost inside a paragraph of text. I usually recommend circling every mention of an existing asset, a current market value, or an alternative use in the problem statement before you start building your cash flow table. It takes maybe thirty seconds and it saves you from missing a line item that can swing the NPV from positive to negative. Sinking funds and bond valuation show up tangentially here as well. Not as a main topic, but the connection between yield to maturity, coupon payments, and present value calculations is something you need to be comfortable with. If your foundation in bond math is weak, Chapter 4 will feel harder than it actually is. Spend an afternoon reviewing how bond prices are calculated and how yield is derived, and you will save yourself a lot of frustration when the chapter starts blending those concepts into project evaluation problems. The solution sets for this chapter are generally thorough if you use them correctly. The recommended approach is to attempt every problem on your own first, even if you get it wrong. Then check the solution and focus specifically on where your logic diverged from the published method. The gap between your answer and the correct answer usually reveals whether the issue is a conceptual misunderstanding, a formula misapplication, or a simple calculation error. Conceptual gaps are the expensive ones. They require going back to the text and rereading the relevant section. Calculation errors are cheap. They just need more careful work.
I also want to flag the annuity due versus ordinary annuity distinction. Chapter 4 sometimes assumes ordinary annuities where cash flows occur at the end of each period, but real-world projects often have beginning-of-period cash flows. The textbook does not always make this explicit in every problem, so you need to read carefully and determine the timing. Using the wrong annuity type shifts your NPV by a factor of one plus the discount rate, which is a material difference on large projects. I had a case where this timing error alone changed the decision from accept to reject on a capital budgeting problem, and the student could not figure out why his answer did not match the solution manual. There is not much more to add about this chapter that will fundamentally change your approach. The NPV rule is the standard, the pitfalls are mostly computational, and the conceptual framework is consistent throughout the rest of the book. If you can handle the problems involving mixed cash flows, project lifespan differences, and inflation adjustments, you are in a good position for the chapters that follow. Chapter 5 moves into depreciation and tax shields, which builds directly on the NPV foundation here. Getting Chapter 4 solid will make the next one significantly easier.