Understanding the General Journal in Practice
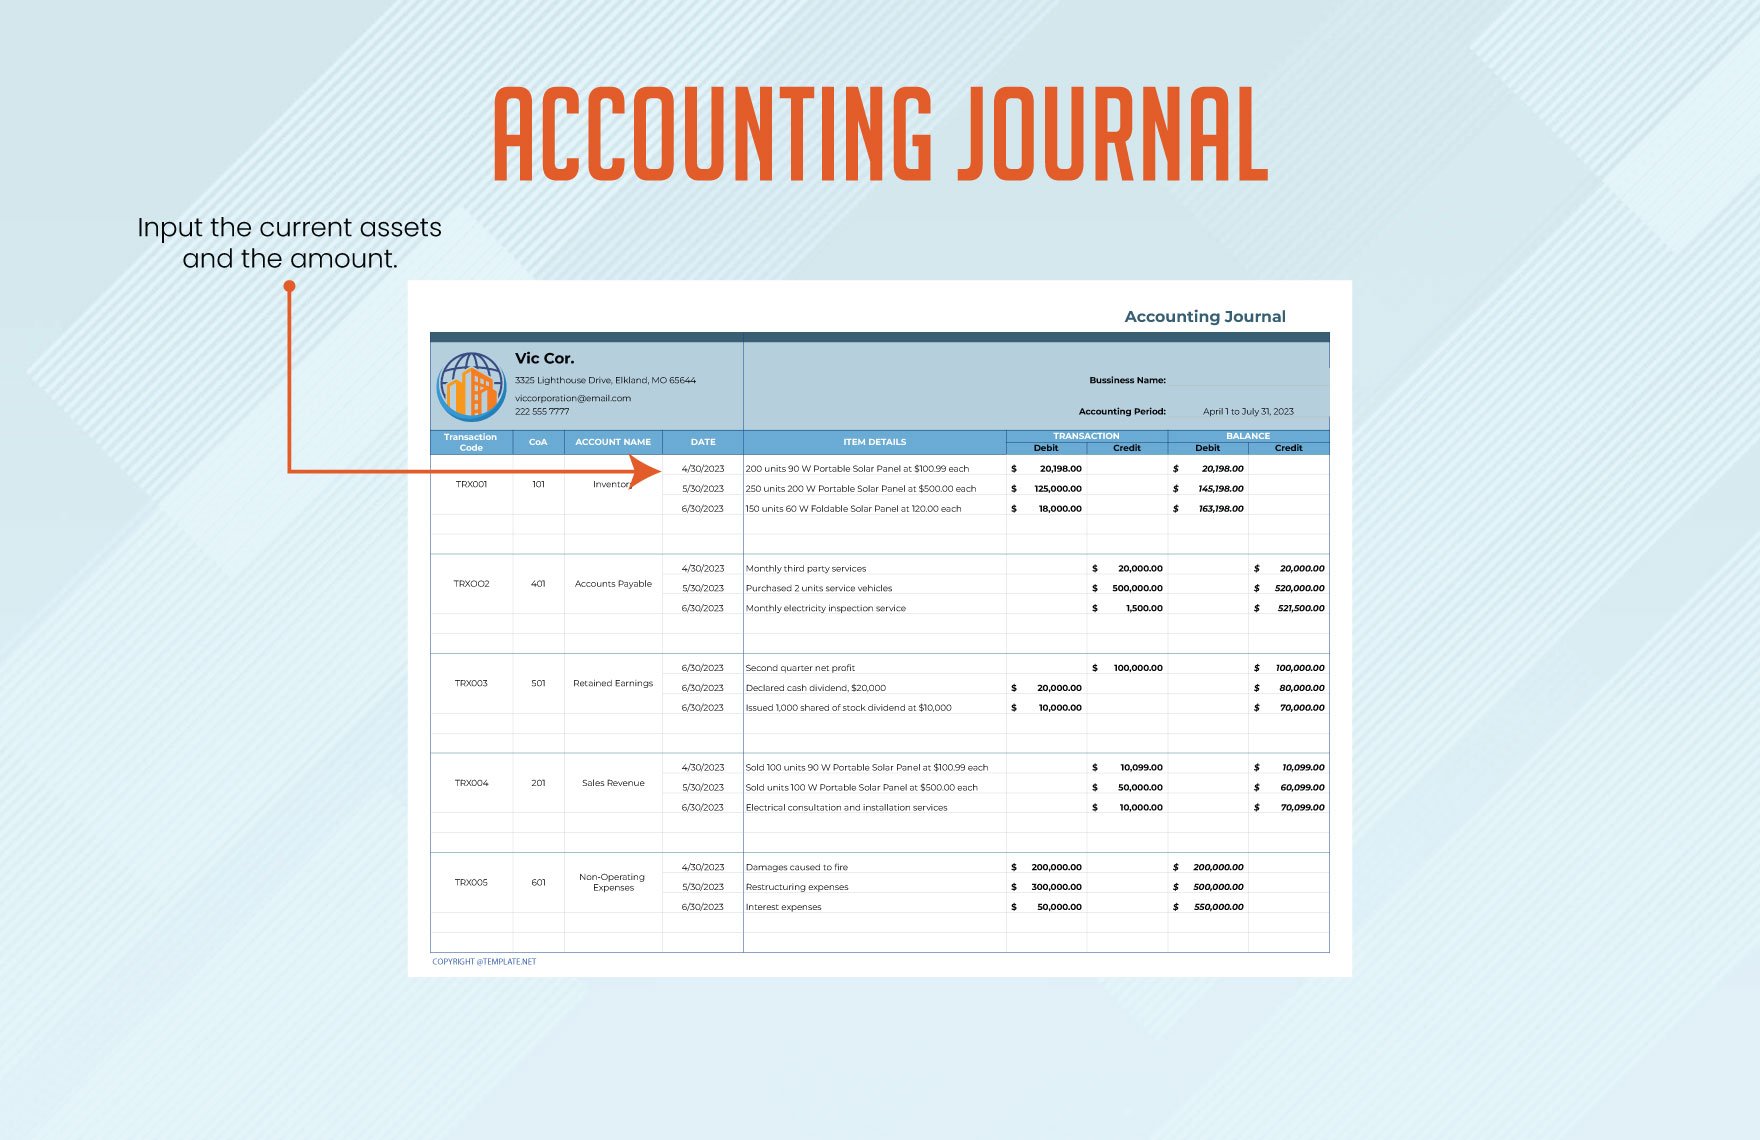
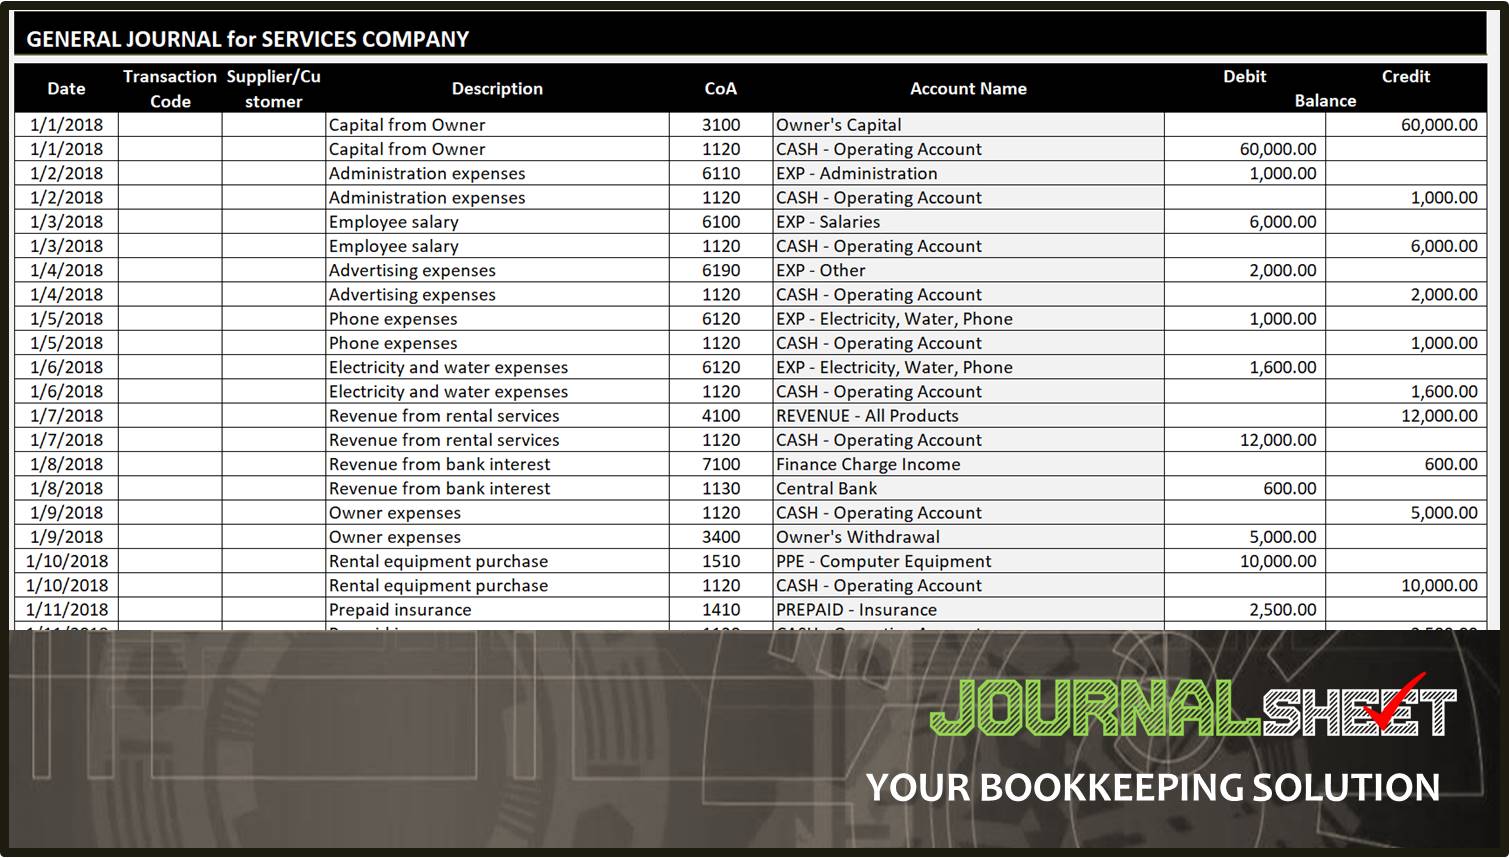
The general journal is where transactions get recorded before they move into ledger accounts. Most people think it is just a book of debits and credits, but the reality is messier than that definition suggests. I spent years watching small business owners skip this step entirely because they found it tedious, and then wondered why their trial balance never seemed to balance no matter how many times they adjusted things. The core function is straightforward. You take a source document — an invoice, a receipt, a bank statement line — and you translate it into journal entry format. That means identifying which accounts are affected, determining whether each needs a debit or credit, and making sure the totals match. If they do not match, the entry is wrong and you cannot post it to the ledger.
Best Accounting Journal Entry Methods for Small Operations
There are several approaches people use, and the right one depends entirely on your transaction volume and the complexity of your business. The manual method works fine if you are dealing with ten or twenty entries a month. You write them in a physical book or spreadsheet, double-check the arithmetic, and then transfer the totals to the appropriate ledger accounts. When I was working with a retail operation that had about forty employees and monthly revenue around two hundred thousand dollars, we switched to a hybrid approach. We kept the general journal in QuickBooks but ran a parallel spreadsheet for intercompany transfers and adjusting entries. The reason was that QuickBooks made certain non-routine entries awkward to track, and I needed an audit trail that showed exactly when and why an adjustment was made. The spreadsheet became my Best Accounting Journal reference, and it saved us during three separate IRS reviews over five years. Automated journal systems exist, but they introduce their own problems. The software can post entries without human review, which means errors multiply silently. I have seen a company miss a six-figure revenue recognition mistake for eight months because the automation mapped everything incorrectly and nobody noticed until the quarterly close. The fix was rebuilding the chart of accounts with proper classification rules and adding a mandatory review step before any automated entry posted.
Here is a counter-intuitive point most beginners miss. A shorter journal is usually better than a longer one. When you break transactions into multiple entries, you create more opportunities for classification errors and reconciliation mismatches. One well-structured compound entry is cleaner than three simple entries that reference the same underlying transaction. The tradeoff is that compound entries require more judgment upfront, but that investment pays off during close. The other thing nobody tells you about general journaling is that date sequencing matters more than people expect. If you post a December transaction on January third without proper cut-off notation, your accruals become unreliable. I once worked with a manufacturing client whose inventory valuation was off by fourteen percent because someone had been backdating entries to hit monthly targets. The journal looked fine on its own, but the cumulative effect across twelve months made the financial statements useless for decision-making. There are scenarios where the general journal simply does not work well. If you process hundreds of identical transactions daily, like a subscription service with recurring billing, the journal becomes a bottleneck. In those cases, a sub-ledger system with periodic summary postings is more practical. The journal still exists, but it records the summaries rather than individual line items. This cuts the manual work from maybe four hours per month down to about thirty minutes for review and reconciliation.
Get the Full Details
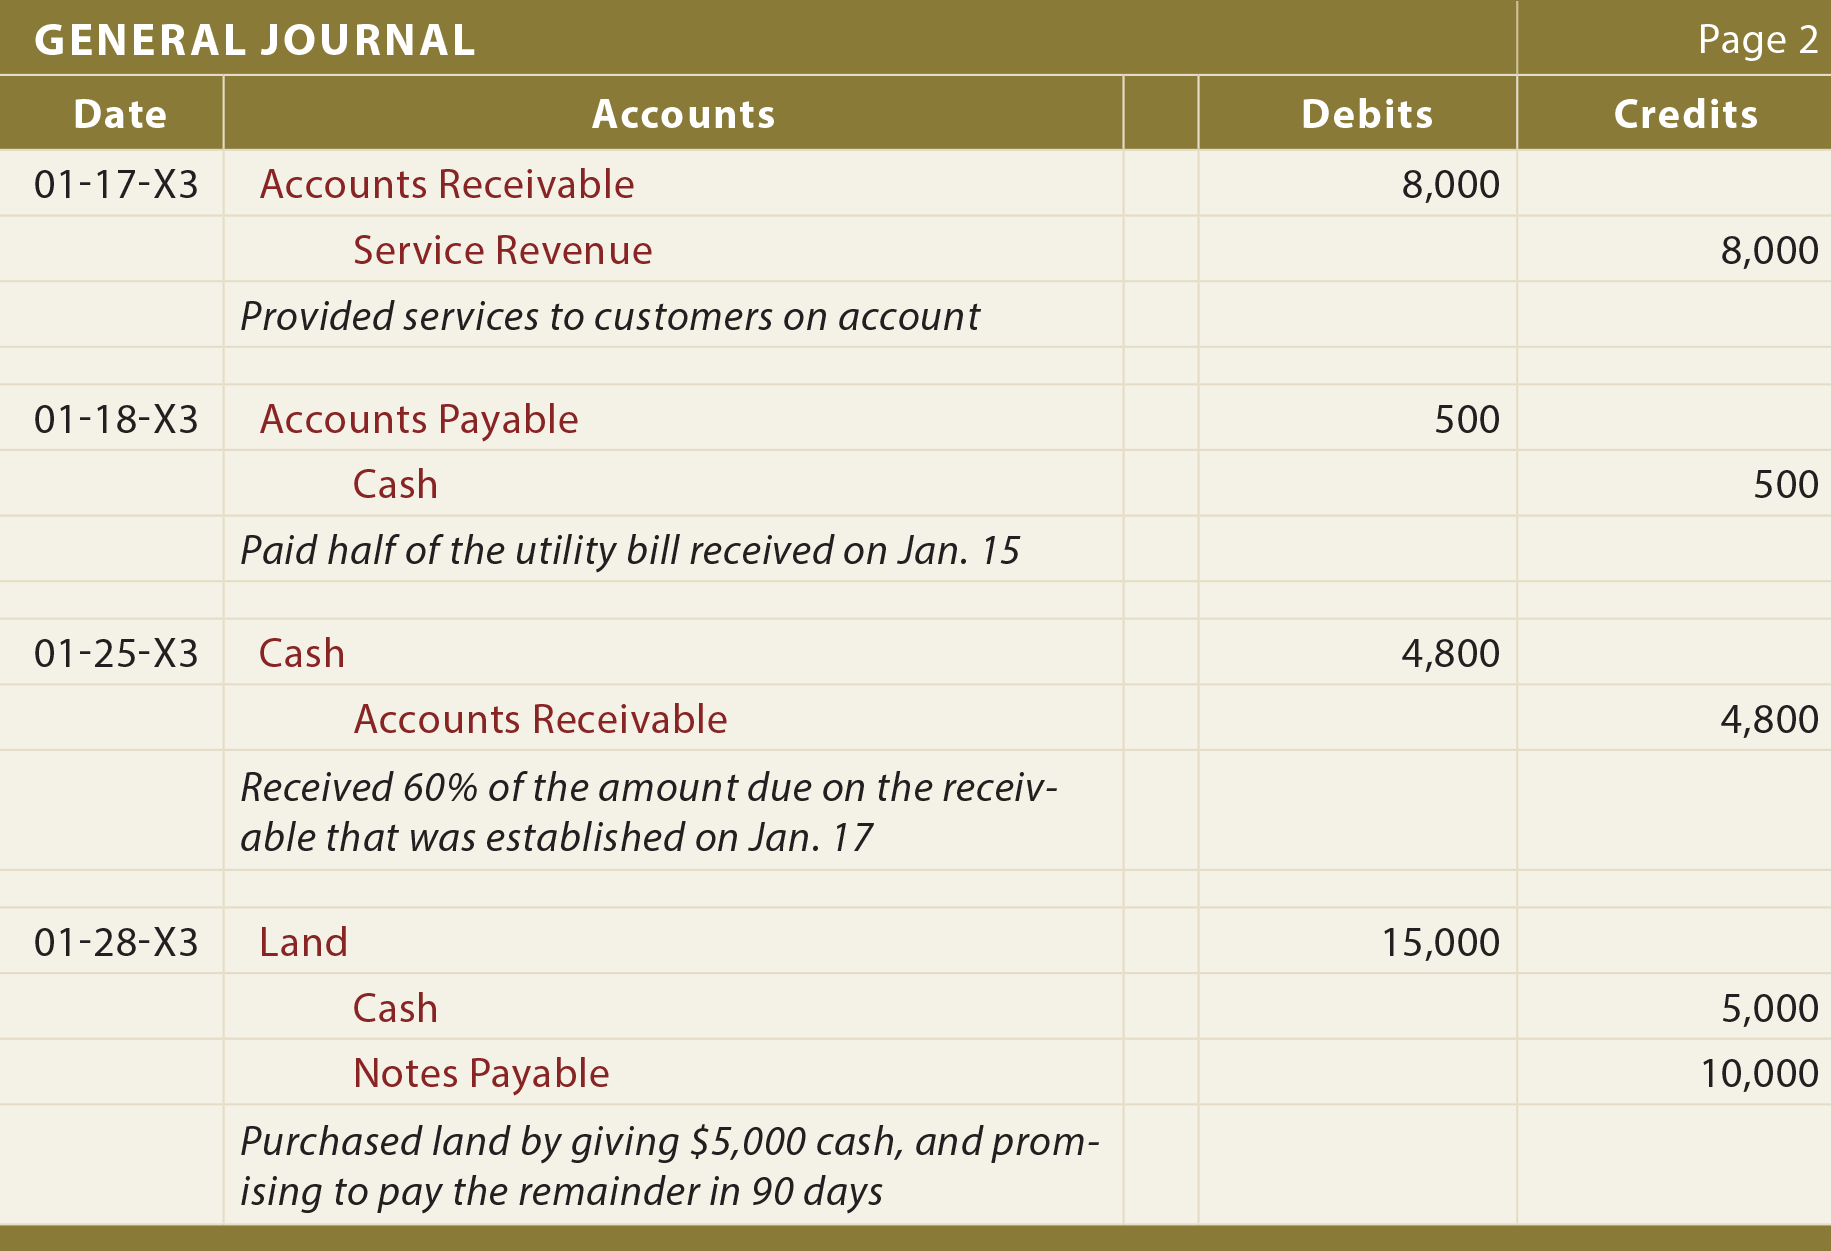
Another limitation is that the general journal does not handle non-financial data. You cannot record customer satisfaction scores or employee turnover rates in it. For those metrics, you need a separate management reporting system. Trying to force everything through the journal creates clutter and makes it harder to find the financial information you actually need. If you want to download a template or starter file for your general journal, most accounting software packages include them. The free versions of spreadsheets like LibreOffice Calc or Google Sheets work too if you keep the format simple. I usually recommend starting with columns for date, transaction reference, account debited, account credited, debit amount, credit amount, and a memo field. Do not overcomplicate the header row, and keep the memo field populated with enough detail that someone reviewing the entry six months later can understand what happened without asking questions. The most common mistake I see is treating the journal as a filing system rather than a recording system. You should not be able to reconstruct the entire transaction from the journal entry alone. If the memo says "payment received" without a reference number, invoice date, or customer name, the entry is useless for audit purposes. A three-second addition of that detail saves three hours of investigation later.
I also want to mention that the general journal should be reviewed before posting, not after. Reviewing after posting gives a false sense of security because the numbers are already locked in. A quick check for obvious errors — mismatched debits and credits, wrong account selections, duplicate entries — takes less than two minutes per entry and prevents most common mistakes before they enter your ledger. Some businesses try to eliminate the journal entirely by posting directly to the ledger from source documents. This works for very simple operations with maybe five or six account types, but it breaks down quickly. The journal serves as a control point, a place where errors get caught before they propagate. Skipping it means you are relying on perfect data entry from the start, which rarely happens in practice. If your business grows beyond a certain size, you will need to consider whether the general journal is still the right tool. A mid-size company with complex revenue recognition rules, intercompany transactions, and multiple subsidiaries usually benefits from an enterprise resource planning system instead. The general journal still exists inside those systems, but it is integrated with inventory, payroll, and receivables modules so the data flows automatically. The manual step is reduced to exception handling rather than routine recording.
For most small to medium operations, the general journal remains essential. It provides the foundation for accurate financial statements, supports audit requirements, and gives you visibility into what is actually happening in the business. The key is to keep it simple, maintain it consistently, and review entries before they post. Those three habits prevent maybe eighty percent of the problems I encounter in year-end close.