The Finance Books Most Indians Actually Need to Read
The personal finance publishing space in India has gotten noisy. You open any bookstore or Amazon category and you are immediately confronted with hundreds of titles promising to make you rich, often written by people who made money in stock markets during the last bull run and have never managed a household budget. Most of them are not worth your time. A smaller number are genuinely useful if you know what to look for. I spent years trying to help junior colleagues at a fintech startup get their finances in order, and the pattern is always the same. They pick up the wrong books first, read the motivational parts, feel good for a day, and then return to the same spending habits. The problem is not willpower. It is that beginner finance material in India is split into two camps: generic American advice that does not apply here, and overly salesy books written to promote some course or financial product. Finding middle ground takes work.
Where to Start With the Best Finance Books For Beginners In India
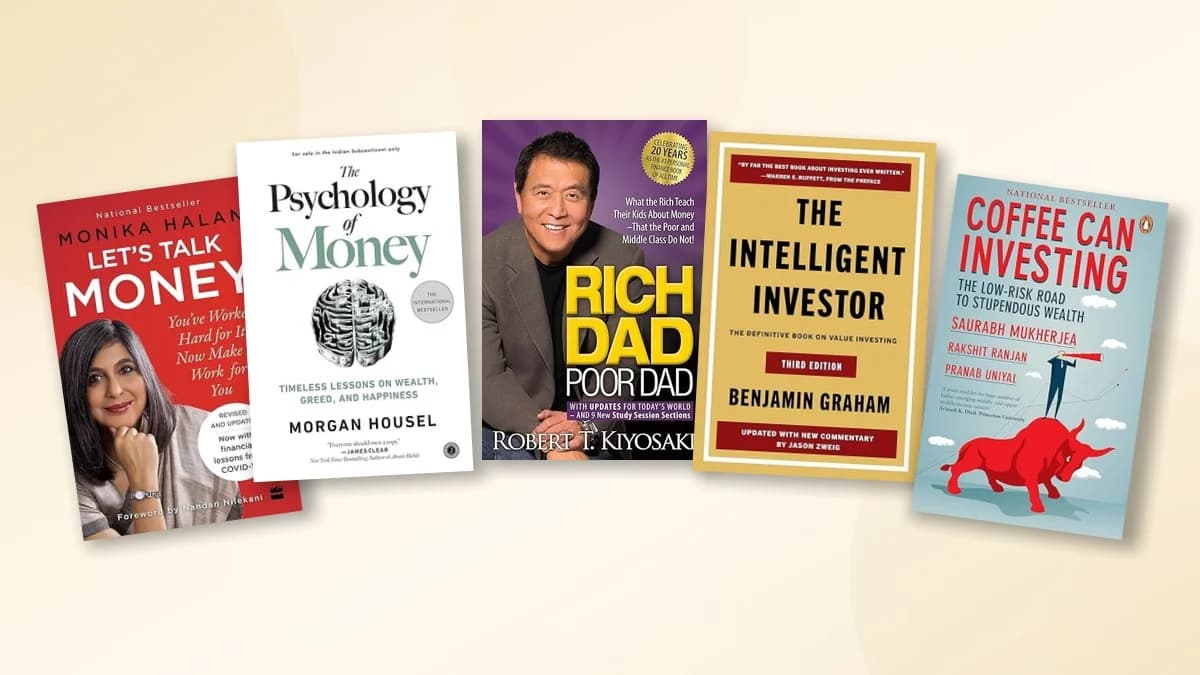
If you are starting from zero, you do not need twelve books. You need four. Read them in this order and you will have more functional knowledge than most people with MBAs after five years. Rich Dad Poor Dad by Robert Kiyosaki. This one comes up everywhere, and for good reason. It is not a technical manual. It is a mindset primer that forces you to think about assets and liabilities differently. The Indian context matters here because most Indians grow up being told that a salaried job is the safest path and that property is the ultimate wealth builder. Kiyosaki challenges both assumptions without being dismissive. The book is simple enough that you can finish it in a weekend, but the framework it leaves behind shapes how you read every other finance book after this one. Let's Talk Money by Kavita Nagarajan. This is probably the most practical beginner book written specifically for India. It covers insurance, retirement planning, taxes, and debt in plain language. What makes it valuable is that it does not borrow American assumptions about 401ks and Roth IRAs. It talks about EPF, NPS, tax regimes under both the old and new systems, and how term insurance actually works in the Indian market. I have recommended this to countless people who were struggling to separate marketing from actual advice, and it consistently cuts through the noise.
Psychology of Money by Morgan Housel. This is not an India-specific book, but it should be on everyone's list regardless of geography. It is a collection of short chapters that explain why smart people make terrible financial decisions. The chapters are standalone, so you do not need to read it cover to cover in one sitting. The section on compound interest and the section on wealth being what you do not see are genuinely eye-opening for beginners who have only ever looked at surface-level returns. Common Sense on Mutual Funds by Mintos Mukherji. This is the technical core of your reading list. Mutual funds in India are confusing because there are so many types, and distributors have every incentive to sell you the products with higher commissions rather than the ones that fit your goals. Mukherji explains the mathematics simply and walks you through asset allocation in a way that actually sticks. It is dry, but it is the kind of dry that prevents costly mistakes later. The rest of the market is optional. Think like a Hedge Fund Manager by Abhay Jere is decent for understanding how professional investors approach value investing in Indian equities. The Psychology of Your Money Future by Brian Portnoy is good if you want to go deeper into behavioral finance after Housel. Wealth Wars by Raghav Bahl gives historical context on Indian business, which helps if you are thinking about entrepreneurship or understanding where India's wealth creation story has come from.
Get the Full Details
What Nobody Tells You About Reading Finance Books in India
Here is a practical detail most beginners miss. The tax rules in India changed significantly with the introduction of the new tax regime, and several books published before 2020 contain outdated numbers. When I was helping a friend set up his retirement corpus in 2023, he followed the EPF withdrawal rules from a book published in 2018, almost making a tax mistake that would have cost him roughly twenty percent more than necessary. Always check the publication date and verify the tax figures against the latest Income Tax Department website. Books on mutual fund classification and direct versus regular plans tend to stay accurate longer because those structures do not change as frequently as tax slabs. Another thing worth noting. Reading finance books will not fix a cash flow problem. I saw this repeatedly in my work. Someone earning forty thousand a month with expenses of thirty-eight thousand could read every book on this list and still not be financially stable. The books teach allocation and compounding and risk management, but they assume you have something to allocate. If you are in that position, the priority is income expansion and expense tracking, not reading. Books accelerate decisions. They do not create the conditions for those decisions to matter. There is also a distribution problem specific to India. Many good finance books are imported or published by small presses and become expensive quickly. A standard US import can run between eighteen hundred and three thousand rupees once shipping and taxes are included, while an equivalent Indian-published book costs between two hundred and four hundred fifty rupees. The price difference is real, and it matters for beginners who are just starting. Paperback editions of Indian-published books age faster and sometimes have poorer paper quality, but the content is usually identical. Used copies on platforms like Olx or local book markets are another option. I have picked up older editions of Let's Talk Money and Psychology of Money for under one hundred rupees, and the advice has not expired.
The one gap in the current Indian finance book market is introductory material on credit scores and responsible debt use. Most beginner books mention credit cards and loans but do not go deep enough into how credit utilisation, payment history, and inquiry counts actually affect your CIBIL score over time. If that is your area of concern, supplement your reading with the RBI's consumer education materials and the official CIBIL website guides. Those are free and more current than any book on the subject. Start with the four books listed above. Read them without rushing. Take notes on the chapters that make you uncomfortable, because that is usually where your actual bias is hiding. Then apply one concept at a time rather than trying to overhaul your entire financial life after finishing a single book. The people I know who actually built financial stability did not read faster. They read slower and implemented more.