Why Most Finance Printables Are Useless
The problem isn't that finance journals don't exist. They're everywhere. The problem is that most of them are designed for people who want to feel productive, not for people who actually need to track money. A blank template with columns labeled "income" and "expenses" looks helpful until you realize you're spending twenty minutes every Sunday copying numbers from your banking app into a grid that doesn't even have a reconciliation column. That's not a system. That's busywork with extra steps. I spent about three years running my own finances through various spreadsheets, printables, and notebooks before I stopped chasing the perfect format and started building something that would actually survive contact with real life. The version I use now has about forty-seven columns in some views, takes up two pages when printed, and still requires me to reconcile it against my statements at the end of every month. It's not glamorous. It works.
How to Build a Best Finance Journal Printable That Doesn't Abandon You by February
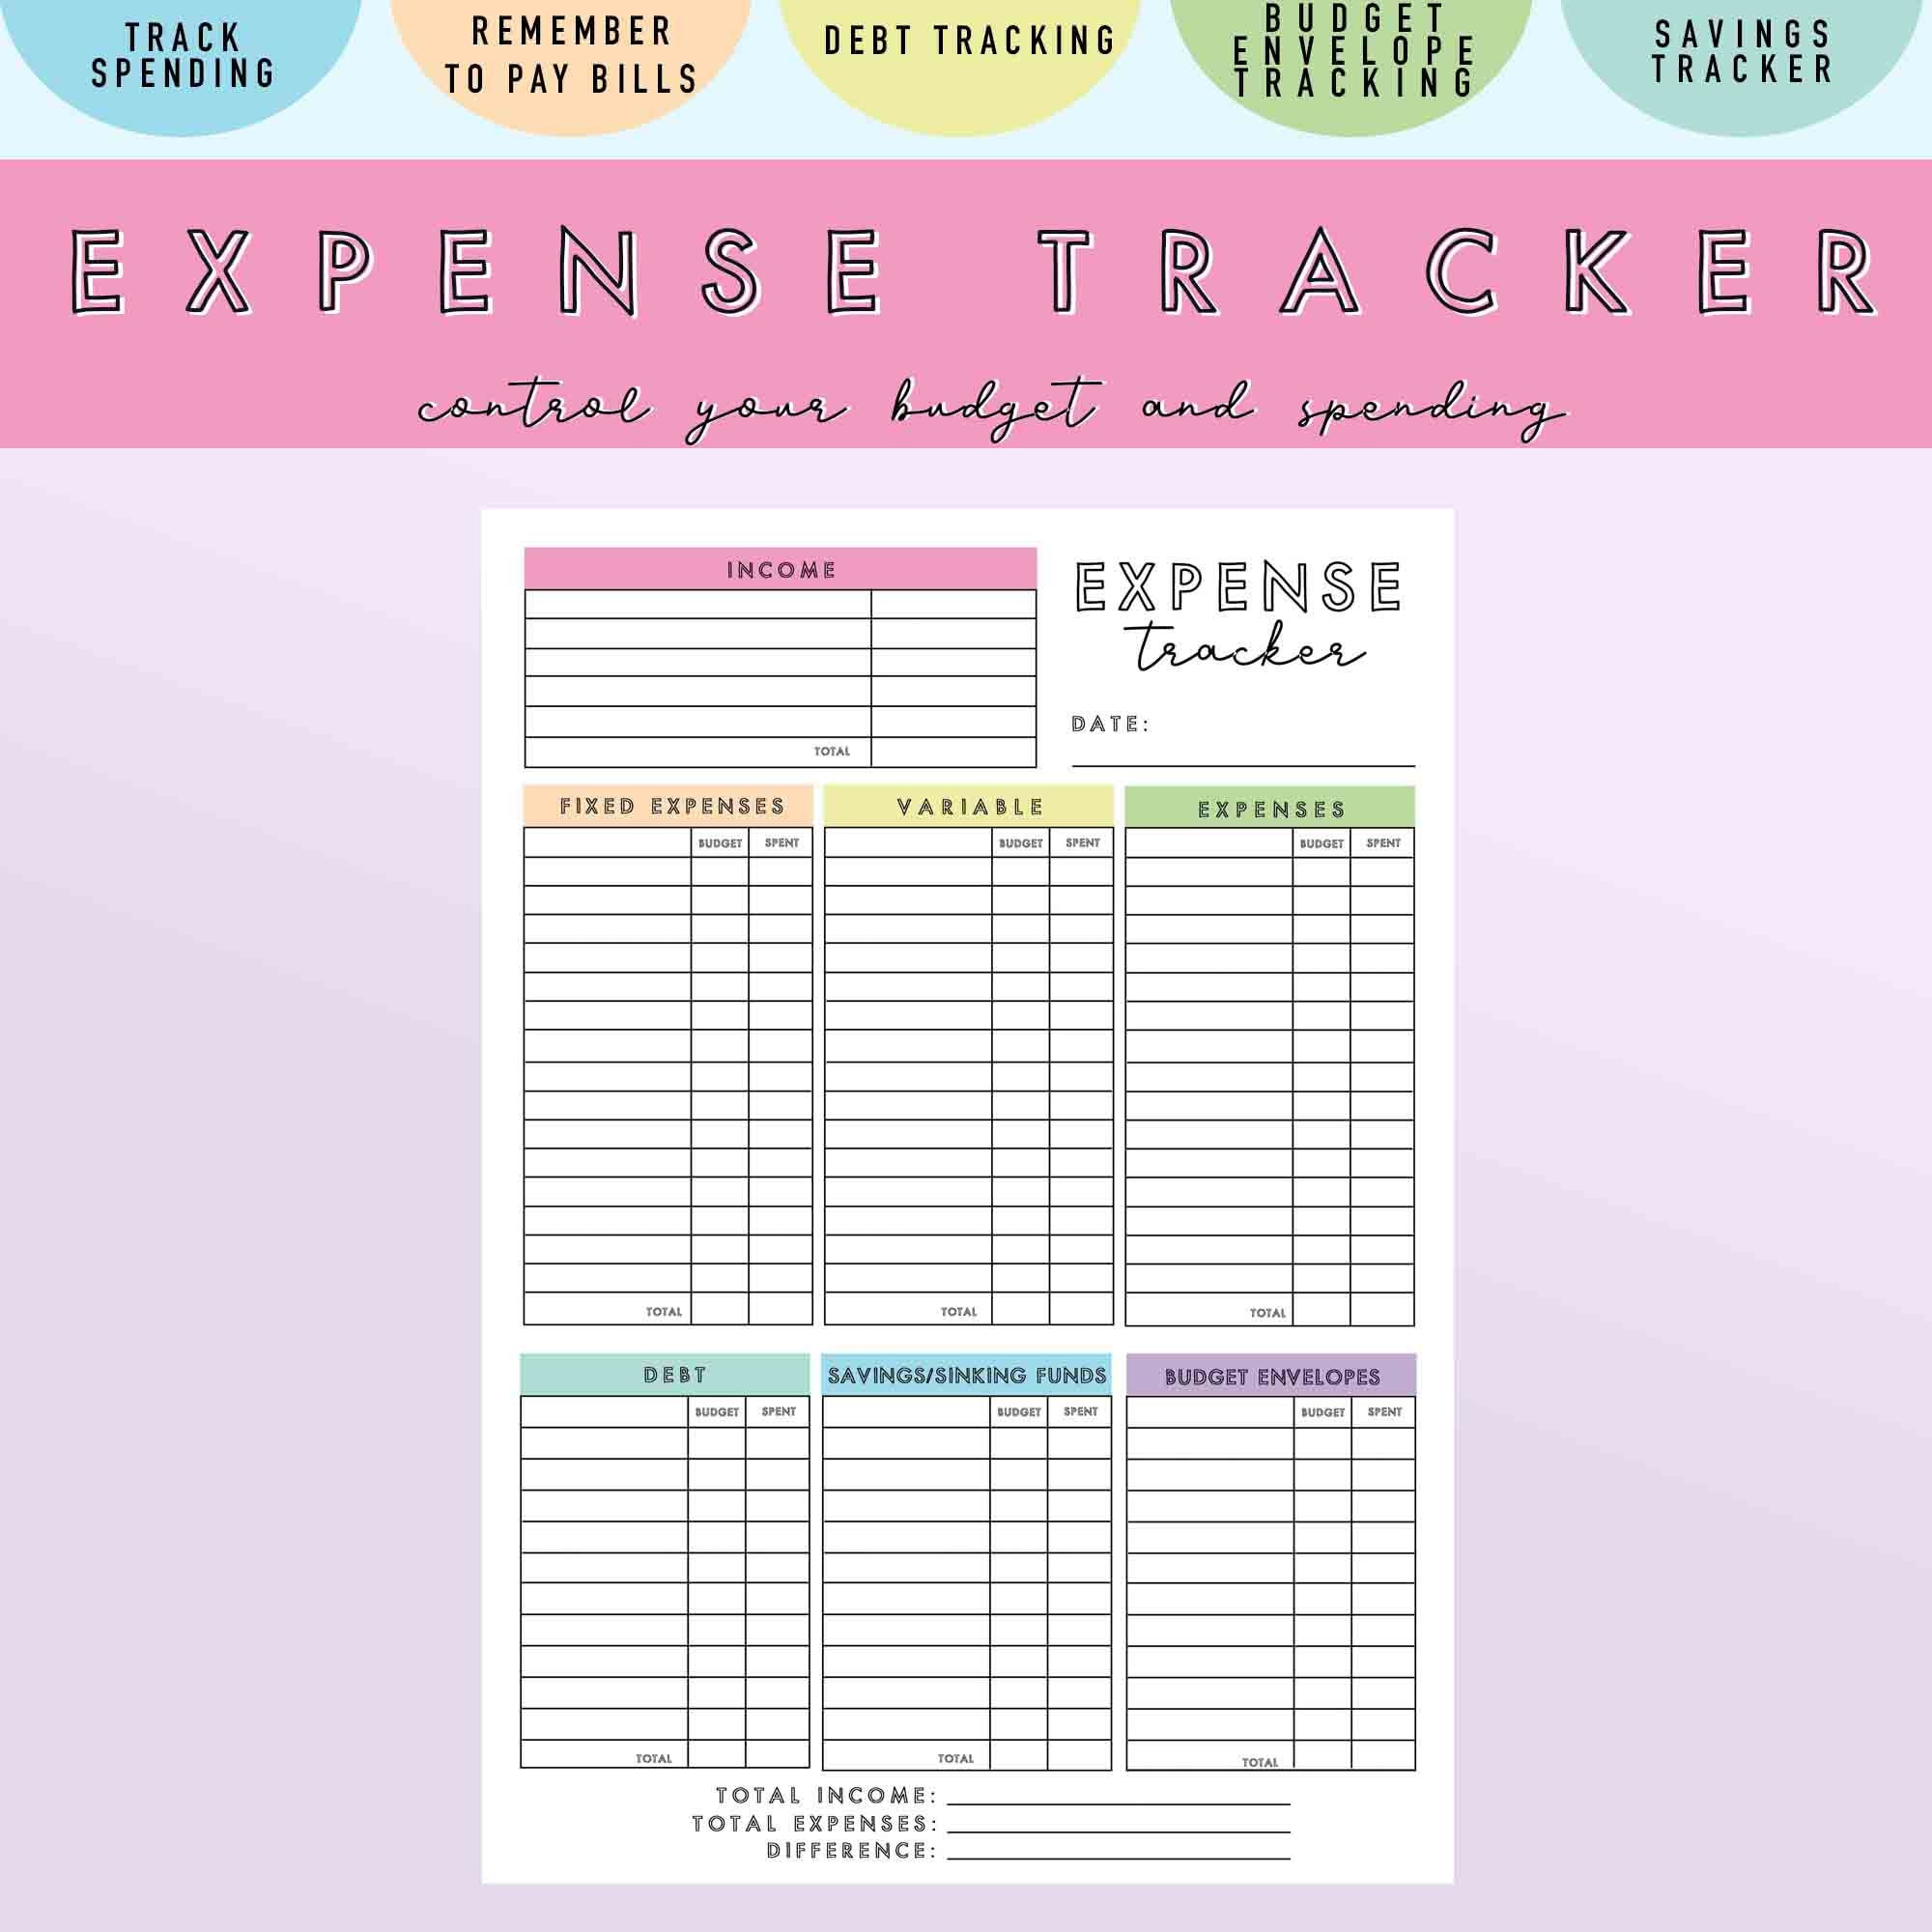
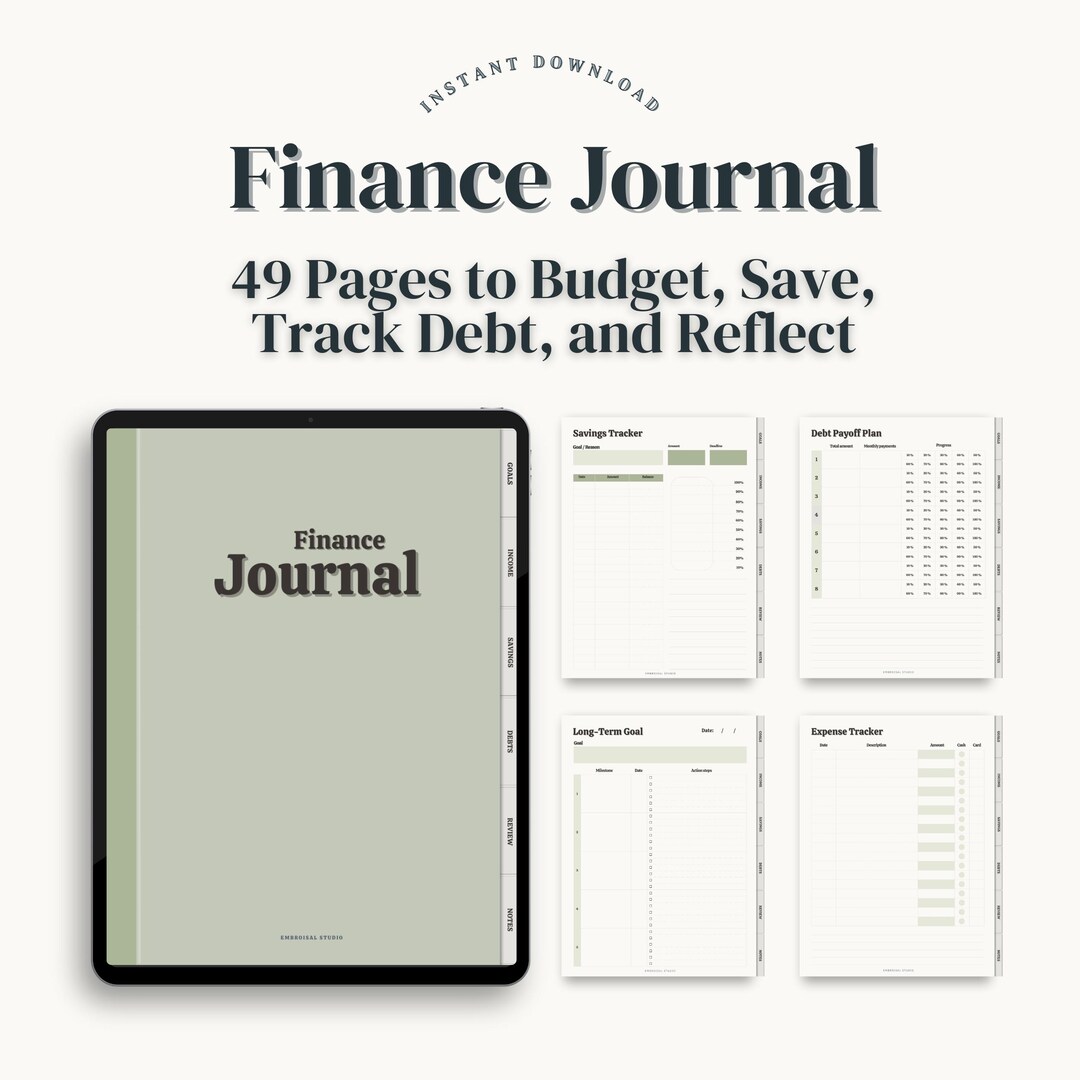
Start by mapping out your actual transactions, not an idealized version of them. Sit down and pull your last three months of bank statements. Count how many distinct categories you actually spend across. For me this came to roughly eighteen categories when I separated business from personal, but for a solo person tracking household expenses alone, you'll probably land somewhere between ten and fourteen. The printable should accommodate slightly more than what you actually use so you aren't constantly editing the sheet when a new expense type appears. Include these columns at minimum: date, transaction description, category, amount, payment method, reference number, and notes. Add a reconciliation field if you're doing this manually, which means a box next to each transaction where you tick off whether it matched your statement. Without that check, you have no way of knowing where the discrepancy is until the end of the month, and by then you've usually forgotten which coffee shop charge was the error. The printable itself should be sized for standard letter paper at 11 by 17 inches if you're doing monthly layouts, or regular 8.5 by 11 for daily entry. I prefer the larger format because it lets me fit two weeks per page with enough space to write actual descriptions instead of cryptic three-letter abbreviations that look meaningful the day I write them and make no sense three months later. A friend of mine switched from A4 to letter size because her printer would only feed letter reliably. Don't overthink it. Just make sure the file you download matches your printer.
If you're building this from scratch in Google Sheets or Excel, set up data validation on the category column. It sounds like a minor detail but it prevents the exact problem I ran into in year two of trying to track things properly, where I had "groceries," "Groceries," and "GROCERIES" all as separate categories because I typed them differently each time. When I finally ran a pivot table to review spending, the numbers were useless. Dropdown menus fix this in about five minutes.
Get the Full Details
Where to Actually Download Something Usable
If you want the Best Finance Journal Printable, the honest answer is that the version I use now doesn't live on any public website. It's been modified so many times across four years that it's basically unrecognizable from whatever original template I started with. But the base structure came from a free resource on the Personal Finance subreddit where someone posted a budget tracker they'd been refining since 2018. It's called the Five Envelope Budget template and it was originally designed for cash-based systems. You can find archived copies of it by searching "r/personalfinance budget tracker sheet." The spreadsheet format is more practical than the printable version because it includes formulas for subtotals, but the printable PDF is what most people actually want to fill out by hand. There's also the Barefoot Investor spreadsheet by Sue Nicholls. It's Australian-focused so the tax categories are off for US users, but the structure is sound and the PDF printables are clean and well-formatted. I used this as my starting point before adapting it heavily. Another option is the EveryDollar zero-based budget templates, which are free if you sign up. They're simpler than what I recommended above, better suited for someone just getting started rather than someone who needs full transaction tracking with reconciliation built in.
What Nobody Tells You About Using a Printable Finance Journal
Printables assume a level of consistency that most people don't maintain. You will skip days. You will lose the sheet. You will stop using it for three weeks and then come back and try to reconstruct a month of spending from memory while simultaneously feeling guilty about it. This is normal. The workaround I use is to keep a backup copy on my phone in a notes app where I dump quick entries during the days I'm too lazy to open the actual journal. On Sundays I consolidate everything into the printable. It adds maybe twelve minutes to my weekly routine but it keeps the main record accurate. Another issue that comes up with printable systems is the physical storage problem. After six months of paper journals, you have a growing stack of sheets that you can't search through digitally. I solved this by photographing each completed month and storing the images in a labeled folder on Google Drive. Takes about ninety seconds per month. The alternative is a physical binder, but those tend to get lost, damaged by spills, or just pushed into a drawer and forgotten entirely. Digital backup costs nothing and takes one minute. There's also the issue of categorization drift. The categories you set up in January won't match your spending patterns in June. This isn't a failure of the system. It's expected. Budgets evolve. When I noticed my "entertainment" category ballooning to nearly forty percent of discretionary spend, I split it into dining out, subscriptions, and hobbies. The printable didn't have a clean way to merge old data into new categories, so I created a separate log sheet for the transition month and then moved everything forward. It added an hour of work but prevented two months of confusing data.
The biggest limitation of any printable system is scale. Once your transaction volume exceeds roughly forty entries per week, a paper journal stops being practical. You'll either run out of space mid-month or you'll start rushing entries just to keep up, which defeats the whole purpose. If you're above that threshold, a spreadsheet with auto-categorization rules or an app like Monarch Money or the NerdWallet budget tracker will save you hours each month. The printable is fine for simple households, part-time freelancers, and anyone tracking under two hundred transactions a month. Beyond that, you're better off automating the data capture and using the printable only for weekly summaries and monthly reconciliations.