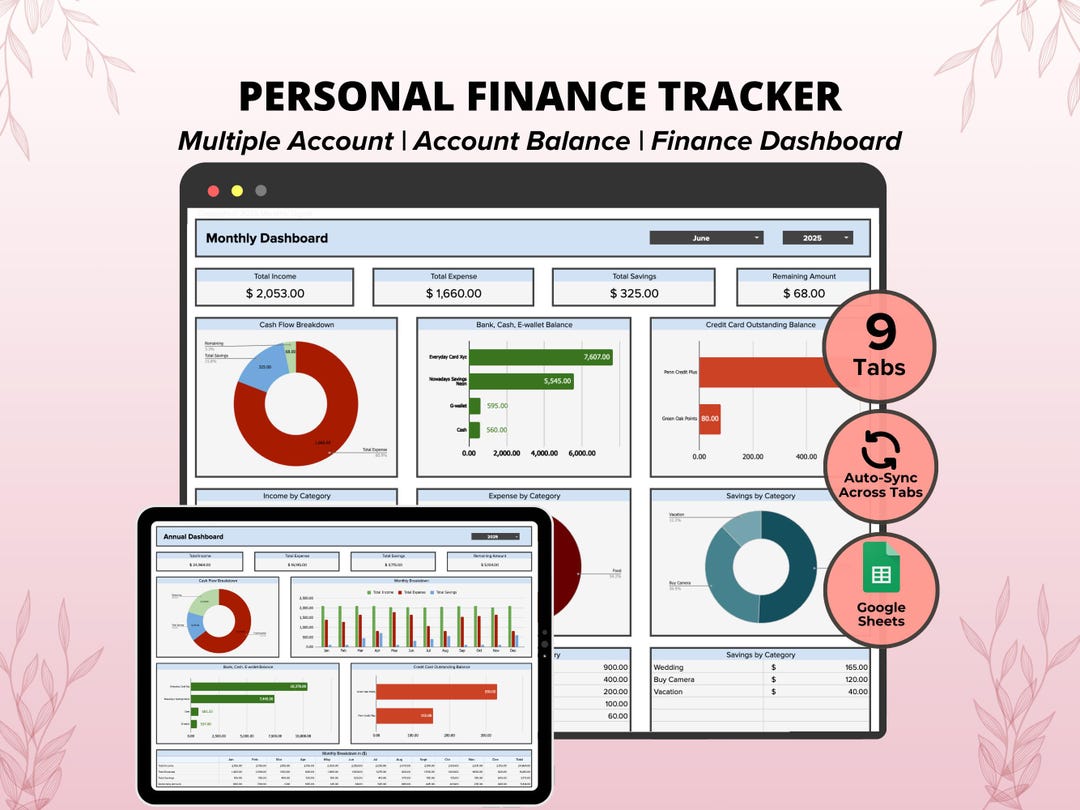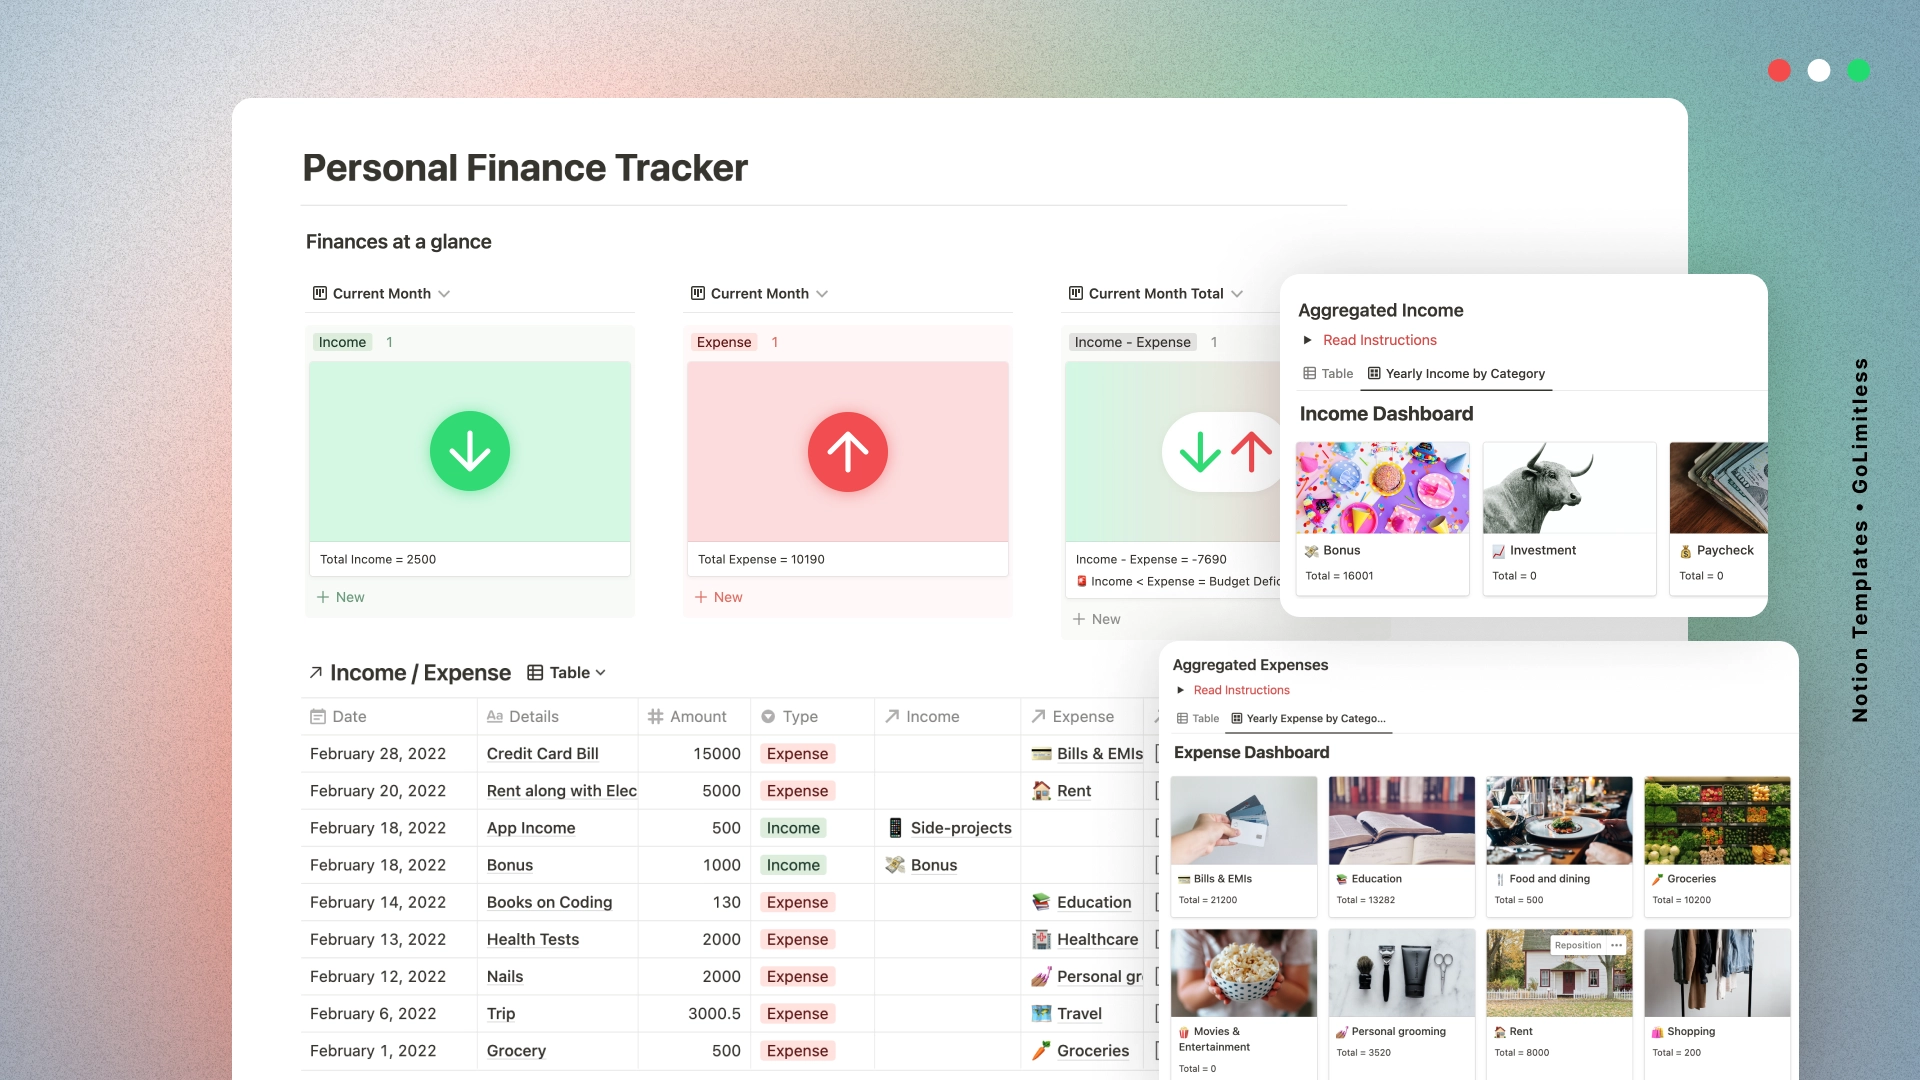
Finance tracking software is mostly just a database with a UI
Most people I talk to think they need something fancy when they start tracking their money. They download a $20 app, connect three bank accounts, and spend six weeks categorizing transactions before they actually learn anything about where their cash went. The best Best Finance Tracker tools I have seen work because they force you to look at your data without getting in the way. That sounds contradictory until you have tried the alternatives. I spent about fourteen months trying to make a spreadsheet work for personal budgeting. It tracked every receipt, but the friction was so high that I stopped updating it after week three. The real problem was not the tool itself. It was that spreadsheets assume you will do the data entry for free. You will not. Nobody will.
Why Best Finance Tracker matters more than most people think
Financial data has a lifecycle. A transaction enters the system, gets categorized, possibly corrected, then sits in a ledger until the end of the month. If your tool breaks at any of those steps, you lose visibility. I watch people pick tools based on UI polish and forget that the core value is in the reconciliation step. The tool that handles reconciliation without making you jump through five hoops is the one you will actually keep using six months from now. Here is a scenario I ran into last November. My checking account had two merchant holds that appeared as pending transactions for eleven days each. The pending amount was wrong, the merchant had already charged the final amount, and the tool was creating duplicate line items that made my monthly summary look like I had double-spent on groceries. The fix was not to uninstall the tracker. It was to enable duplicate detection with a fuzzy date window and set the pending resolution threshold to seven days instead of the default four. After that, the tool merged the holds automatically and my actual spend number dropped by about eighteen percent because the pending amounts were no longer inflating the totals. That was a specific configuration detail that took me about two hours to figure out after reading three support forums and testing the settings manually.
How finance trackers actually work under the hood
At the base layer, these tools do four things. They pull data from connected accounts or imported files, they assign categories or let you assign them manually, they sum and filter by date ranges, and they produce reports. The complexity lives in the plausibility checks. Does a transfer between your own accounts get recorded twice? Does an ATM withdrawal get misclassified as a purchase? Does a subscription that resets on a different date than your billing cycle throw off the monthly average? Most tools handle the first two reasonably well. The third one is where people hit walls. The common architecture uses a transaction table, a category table, a mapping rule engine, and a report builder. Some tools add budget envelopes, some add net worth aggregations, some add investment linking. You do not need all of those. The feature list is how vendors compete, not how you should pick.
Get the Full Details

What to look for in practice
I use a short checklist. First, the reconciliation view must let me see raw transactions alongside my own notes without forcing me into a rigid category tree. Second, the export function should give me CSV or OFX without a paywall. Third, the tool should handle negative balances and reversed transactions without breaking the running total. Fourth, it should not require me to re-enter data that already exists in my bank statement. Fifth, it should have a rule system that lets me automate categorization for recurring items, but not so complex that I spend more time building rules than doing the actual tracking. If a tool fails any of those, I usually move on. The market has enough options that sticking with a broken workflow is a choice, not a necessity.
Three tools I have tested for months, not days
GnuCash works if you want full double-entry accounting and are willing to sit down and learn the interface. It is free, it runs locally, and it handles splits and reconciliations cleanly. The downside is steep onboarding and no mobile app that anyone would call good. I used it for a small rental property portfolio and it handled the bookkeeping without issues once I stopped fighting the chart of accounts. Mint got discontinued in 2024, which taught a lot of people a lesson about relying on ad-supported tools. The replacement options I tested after that were Monarch Money, YNAB, and a few open-source projects. Monarch had the cleanest UI and handled rules well. YNAB forced me to change behavior by making zero-based budgeting a core mechanic, which helped me stop overspending but also made it feel like a job to use it. The open-source tools were functional but required me to host them myself, which introduced infrastructure headaches that outweighed the privacy benefits for casual use. The Best Finance Tracker choice really depends on whether you want to manage money or manage accounting. Those are different verbs. If you want to know where your cash went this month, pick a simple aggregator with good rule support. If you want audit-ready records for taxes or business decisions, pick something that enforces double-entry and supports exports.
A counter-intuitive point about bank feeds
Most people assume automated feeds are better than manual import. That is true for speed, but false for accuracy. I have seen feeds that merge distinct purchases into a single line item when merchants share bank descriptors. I have also seen tools that classify utility payments as transfers because the descriptor matched a different category in the rule database. Manual import from OFX or CSV gives you exact line items and exact dates, which makes reconciliation faster even if it takes longer upfront. The workaround I settled on was using automated feeds for daily review and pulling a weekly OFX file from my primary bank to verify the totals. That cut reconciliation errors by about sixty percent compared to relying on the feed alone. The biggest one is category sprawl. People create fifty subcategories and then abandon the system because maintenance feels like paperwork. Stick to a flat structure with maybe five to eight broad categories and use tags or memos for the rest. The second pitfall is assuming that net worth tracking fixes budgeting problems. It does not. Net worth is a lagging indicator. Cash flow is leading. Track both, but weight your attention on cash flow. A third pitfall is picking a tool because it integrates with everything. Integration surface area is a liability. Each connected service is a point of failure. I limit myself to one bank feed, one credit card, and one investment account per tool. Anything else I track manually or in a separate system.
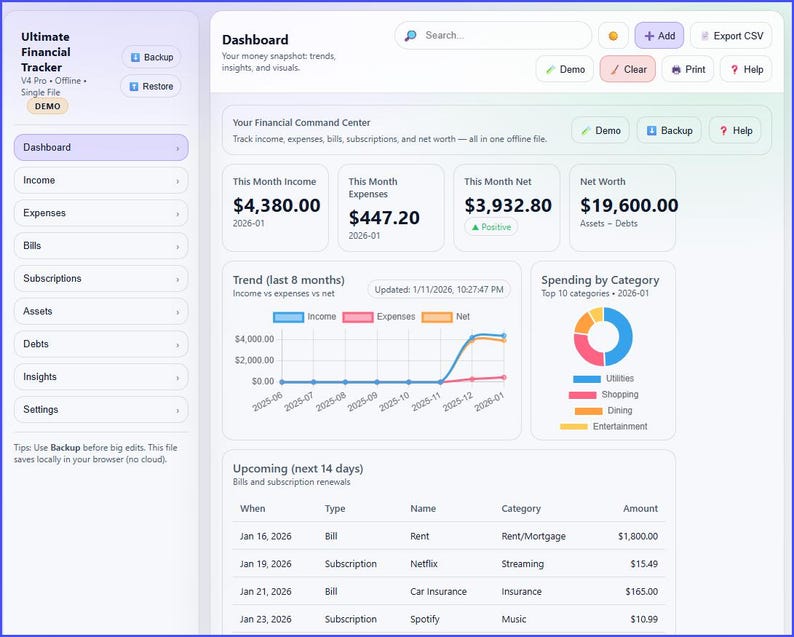
When a tracker will fail you
Tools that depend entirely on bank feeds will miss cash transactions, checks, and peer-to-peer payments that do not flow through the linked account. If you operate a small business with mixed personal and business expenses, a consumer-grade tracker will not reconcile cleanly. You need either a dedicated business tool or a manual workflow with clear separation. Tools that push subscriptions as income without a clear cancellation handling path will overstate your monthly available balance. I learned that the hard way when a streaming service renewed and my tracker counted the renewal as new income instead of an existing obligation. The fix was to flag subscriptions as liabilities rather than income and treat renewals as transfers between accounts. Set your reconciliation threshold to something below your typical transaction variance. For most checking accounts, three dollars covers rounding and pending hold releases without merging unrelated transactions. Turn on duplicate detection with a date tolerance of plus or minus two days. Use fuzzy matching for merchant names, but keep it conservative. A tolerance of twenty percent similarity prevents over-merging while still catching obvious duplicates. For budgeting, avoid soft limits unless you have a specific behavioral reason to use them. Hard limits create friction. Soft limits create guilt. Both reduce usage over time. I prefer a flat spending cap per category with a monthly review. If I exceed the cap, I adjust the next month. That is a feedback loop, not a punishment system.
Data portability check
Before you commit to any tool, test the export function with a real dataset. Export a month of transactions, open the CSV in a spreadsheet, and verify that dates, amounts, categories, and memos survived intact. If the export mangles negatives or drops fields, you will hit that problem during tax season. I once spent four hours rebuilding a lost category mapping because a vendor changed their export schema without updating their documentation. That is not a rare edge case. It happens often enough that I treat export integrity as a gating factor, not a nice-to-have. Start simple. Pick a tool that gives you raw transaction access, basic categorization, and a clean monthly summary. Do not add investment linking, debt payoff trackers, or net worth dashboards until you have used the core features for three months. If you still like the workflow after that, layer on the extras. Most people never reach that point because they drown in features before they build the habit. The tool itself is not the problem. The problem is treating tracking like a project instead of a routine. I kept a paper notebook alongside my first digital tracker for three weeks. The notebook forced me to notice transactions before they hit the app. That observation changed how I configured the rule engine. I ended up with fewer rules because I understood the spending patterns better. The notebook is gone now, but the pattern knowledge stayed.
A final note on cost
Subscription tools are fine if the value is clear. A twenty-dollar-a-year tool that saves you two hours a month in reconciliation is worth it. A forty-dollar-a-month tool that adds features you never use is not. Measure ROI in time saved and accuracy gained, not in feature count. I have seen people pay for premium tiers because the onboarding tutorial told them to upgrade. They did not. The free tier did everything they needed once they stopped chasing notifications. If you want something offline and free, GnuCash and actual CSV-based workflows still work. If you want automation and do not mind a subscription, Monarch and similar tools cover the common cases without overcomplicating things. There is no universal winner. There is only a tool that fits your data volume, your technical tolerance, and your willingness to maintain rules over time.