The Actual Process
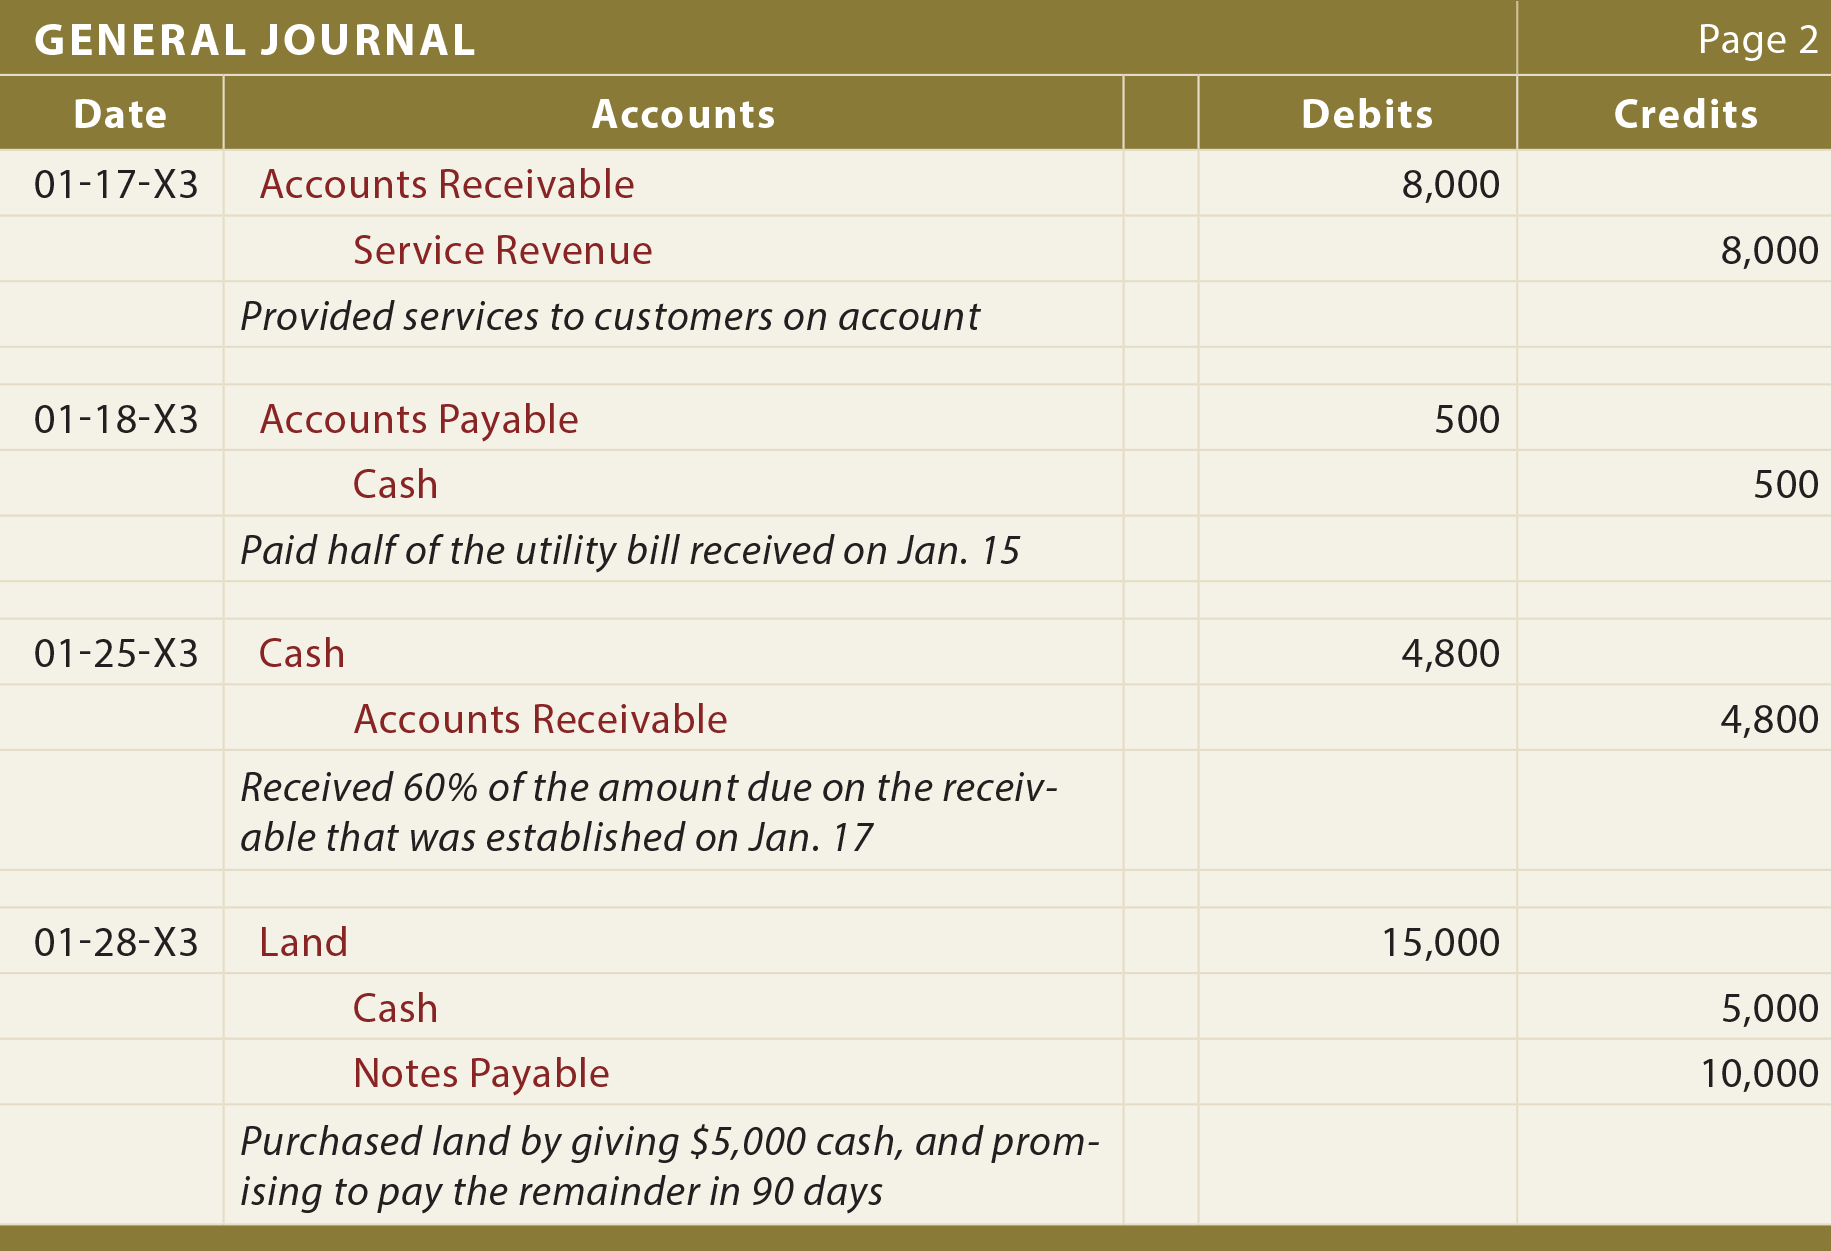
You open your spreadsheet or accounting software. You look at the source document — an invoice, a receipt, a bank statement line. You figure out which accounts are affected. You make the debit. You make the credit. They match. You move on. That is the mechanical part. The hard part is deciding what to debit and what to credit in the first place, and doing it consistently enough that your books don't fall apart three months later when someone tries to read them. I learned this the hard way. Early in my career, I was handling a client who had been self-journaling for about four years before they brought me in. Their charts of account were a mess. Revenue was stuck in a general ledger account called "Misc Income." Expenses were split across maybe six different categories with no consistent rules. When we tried to pull a P&L for a loan application, it took me roughly three weeks to figure out what was actually what. The client thought they were doing fine.
Best Way To Journal For Accounting
The single most effective thing you can do is set up a decision tree before you ever touch a journal entry. Write it down. Keep it visible. This takes about 15 minutes for a small business and will save you days of reconciliation work down the line. Here is what that looks like in practice: Step one: Classify the transaction type. Is it revenue? Expense? Asset purchase? Liability payment? Equity? Get this right first. Everything else follows from it.
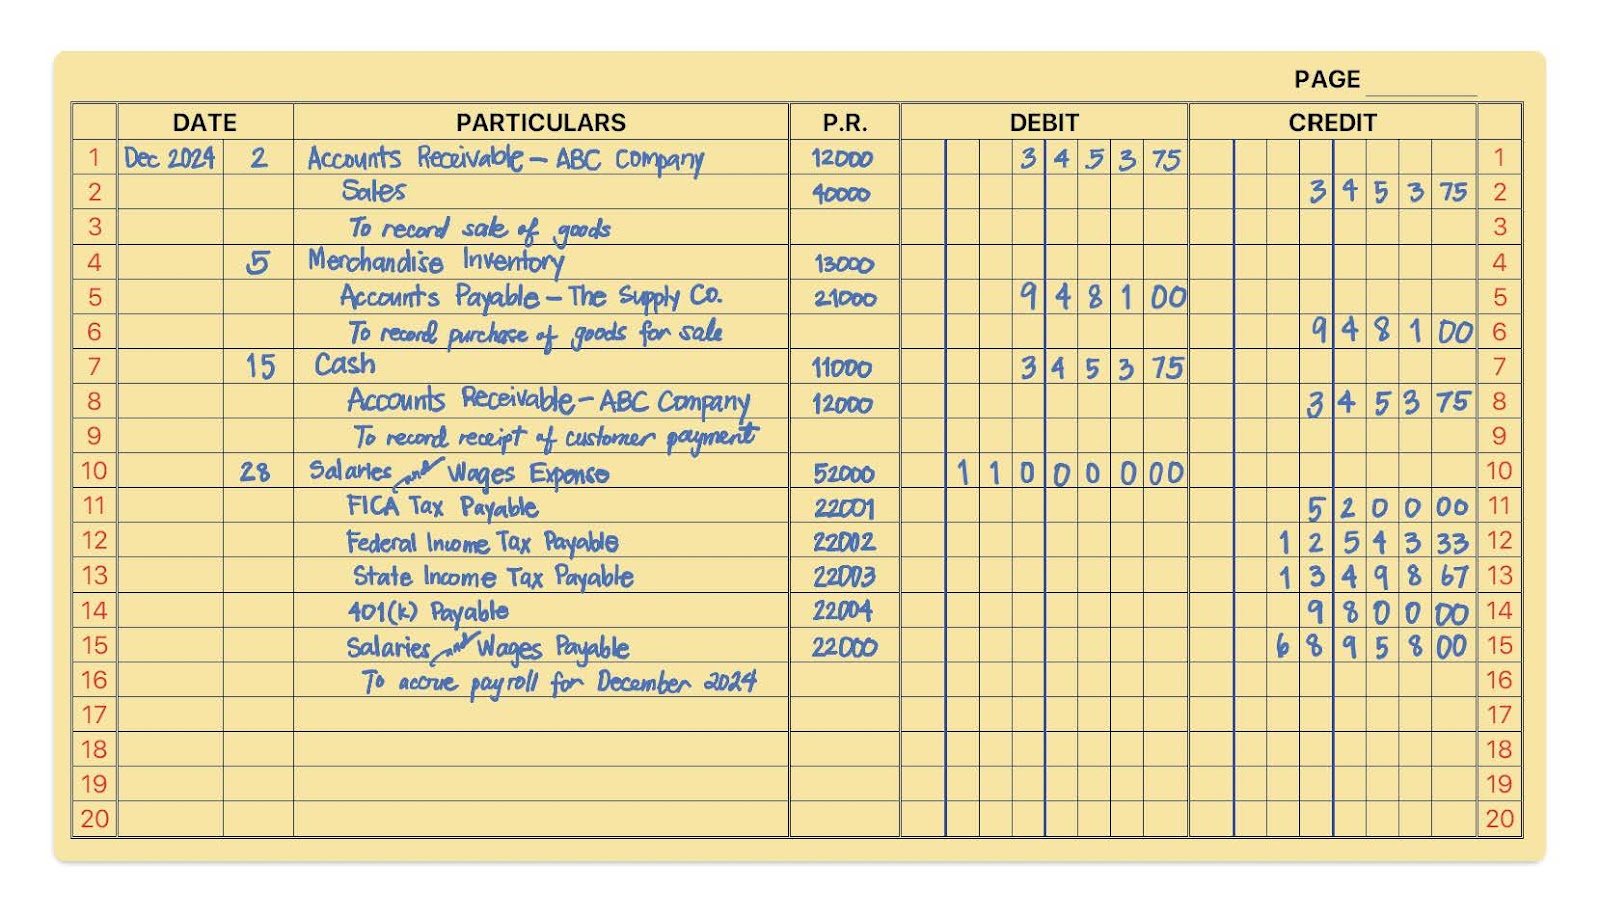
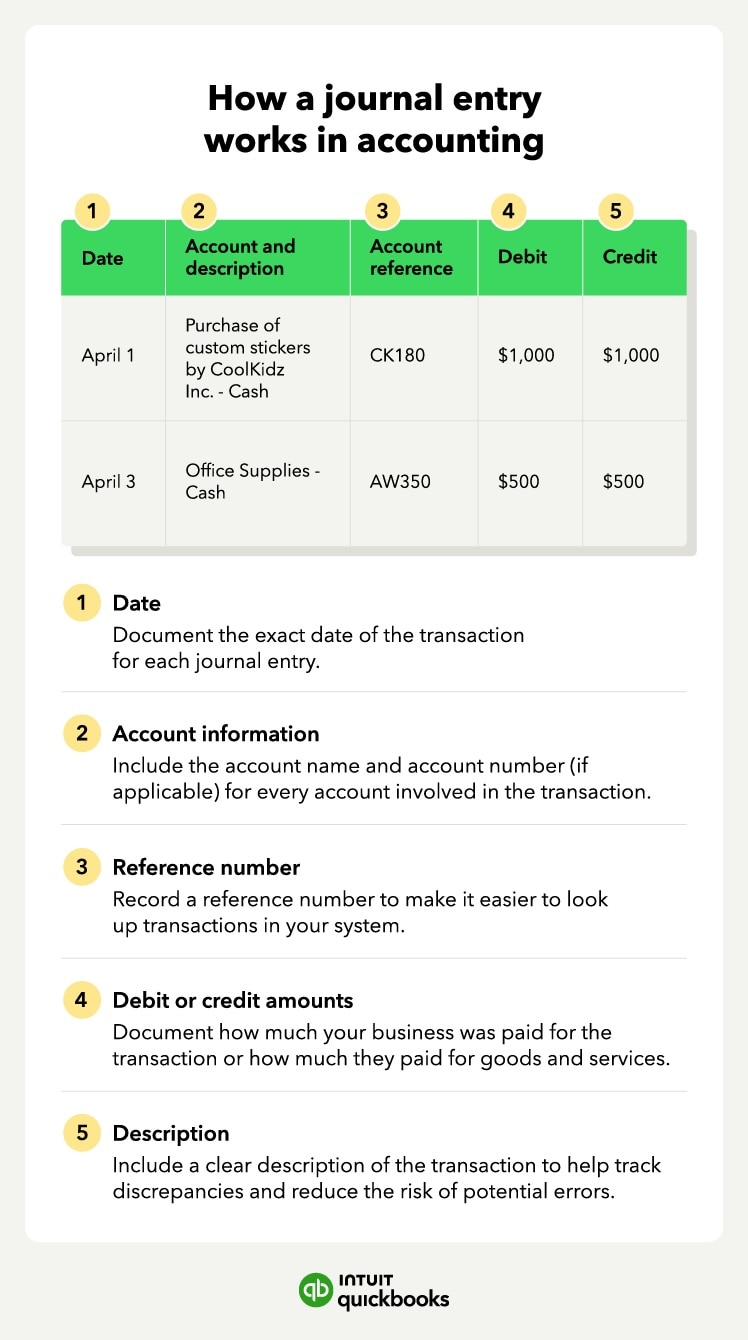
Step two: Identify the accounts involved. For revenue, is it earned from product sales or service delivery? Does it go to Accounts Receivable or directly to Cash? For expenses, does it belong in COGS or an operating expense? This distinction matters for gross margin calculations and it catches a lot of people off guard. Step three: Determine the direction. Debit or credit? A simple way to remember without relying on some mnemonic you will forget in two months: assets and expenses increase with debits. Liabilities, equity, and revenue increase with credits. That is it. Apply it mechanically. Step four: Add a description that would make sense to someone reading it six months later. "Office supplies" is weak. "Staples order #4729 - Q2 office replenishment" tells you something useful.
Get the Full Details

I once spent an entire afternoon tracking down a $4,200 journal entry that was labeled "services rendered." No date reference. No client name. No PO number. The person who wrote it had left the company eighteen months earlier. In the end, it turned out to be a recurring consulting retainer that should have been set up as an automated recurring entry. We never did find the original contract.
Common Pitfalls That Actually Matter
The biggest mistake I see is journal entries that balance for the wrong reasons. Someone puts a debit in one account and a credit in another and calls it even, but the underlying classification is wrong. The trial balance will still zero out. The financial statements will look clean on the surface. But your gross margin will be wrong, your tax position might be off, and nobody will notice until audit season or a serious bank review. Another issue is over-complicating things. A lot of people think using more sub-accounts makes their books more precise. It doesn't. It makes them harder to read and much more painful to reconcile. One well-defined expense category is better than ten poorly defined ones every time. Here is a counter-intuitive point that most beginners miss: prepayments and accruals are not optional. If you are running a cash basis setup and your business has grown past about $500,000 in annual revenue, you are likely leaving money on the table or misrepresenting your financial position by ignoring them. A $12,000 insurance premium paid in January should be spread across the coverage period, not dumped into one month. This alone can shift your net income enough to matter for tax planning or lender conversations.
Tools and How I Actually Use Them
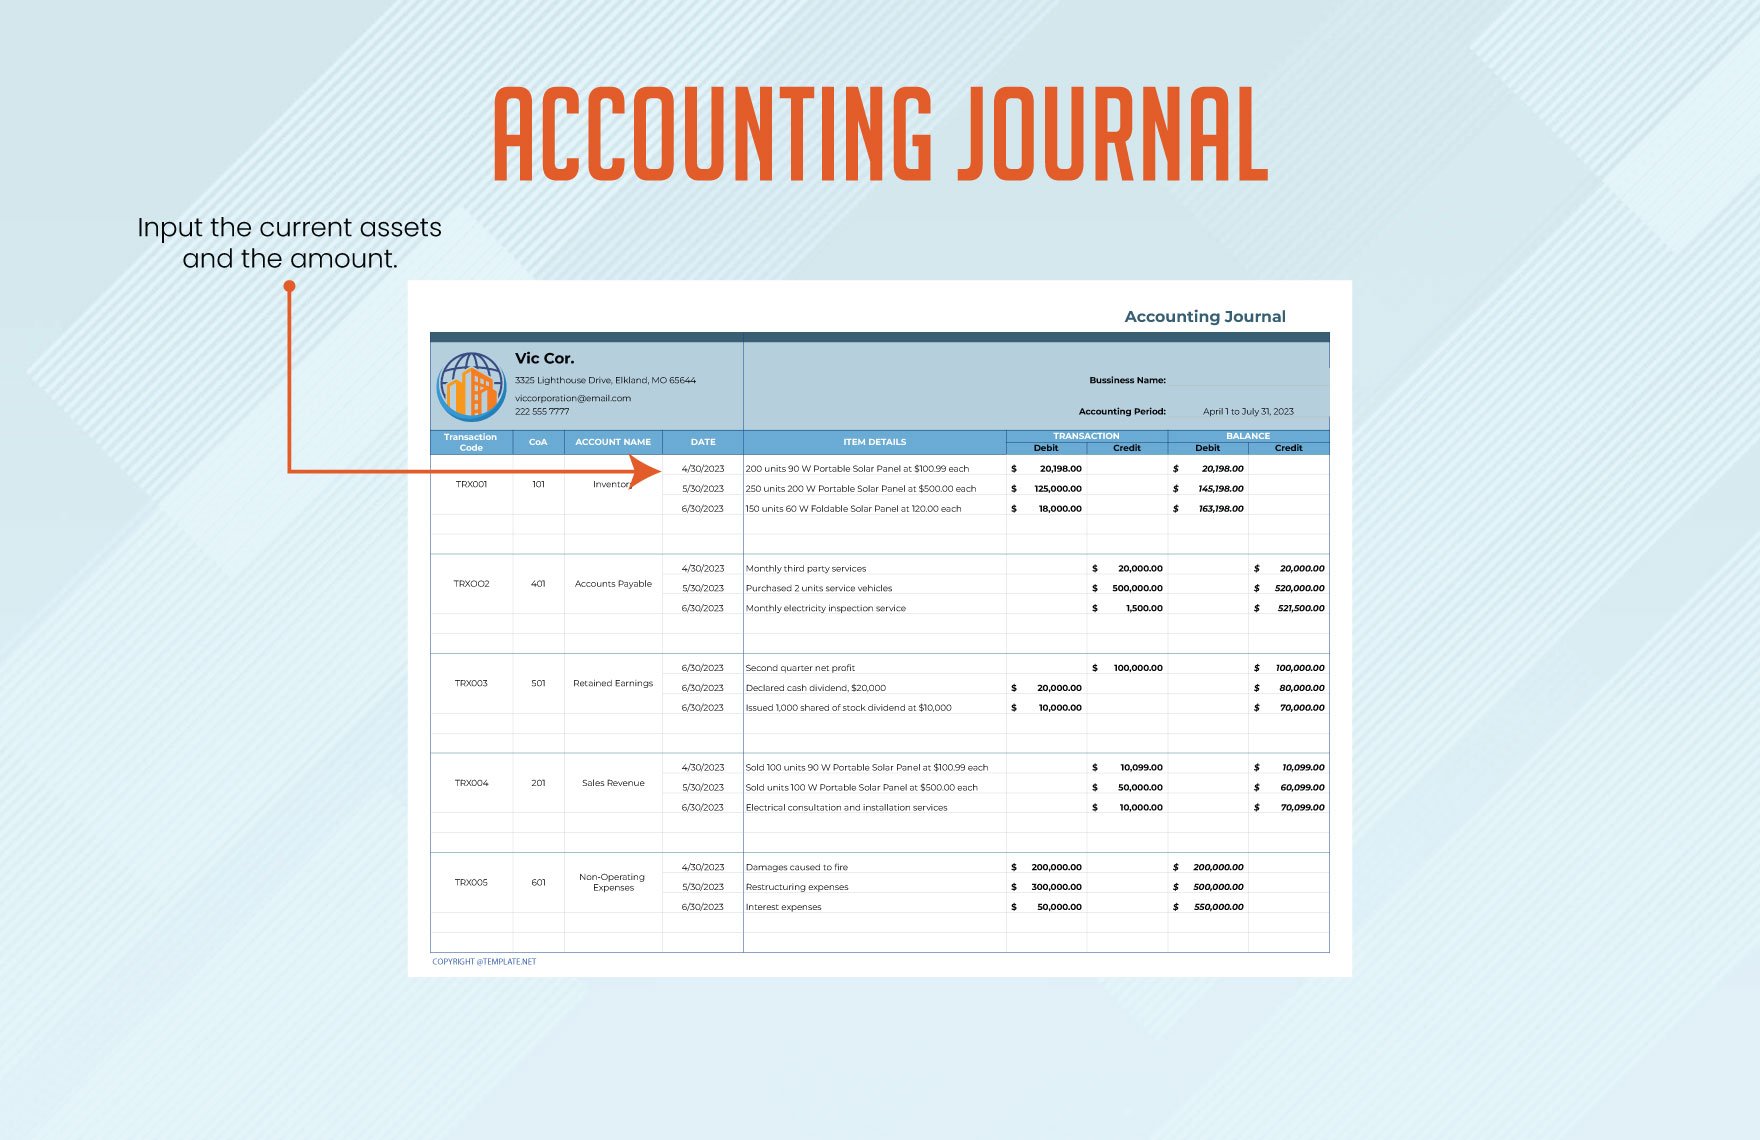
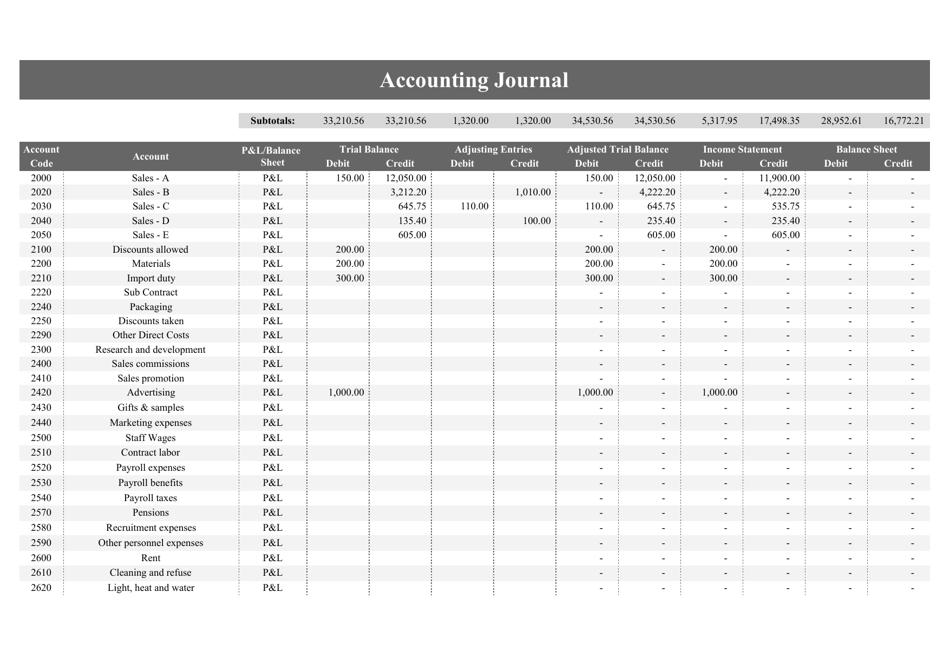
I have used QuickBooks, Xero, NetSuite, and a few custom spreadsheets that I built over the years. For small to mid-size businesses, I usually recommend starting with QuickBooks Online or Xero because the account mapping is straightforward and the reporting engine handles the drudgery for you. NetSuite is overkill unless you are dealing with multi-entity structures or complex revenue recognition rules. For the actual journaling workflow, I keep a running template that I reuse. It has columns for date, account, debit, credit, description, and supporting document reference. I fill this out weekly, not monthly. Monthly journaling is how mistakes compound. When you catch them within a week, they are usually five-minute fixes. When you catch them at quarter-end, they are sometimes day-long problems. If you need a free template, Google Sheets has a basic accounting journal template you can pull up at sheets.new and search for "journal." Not the best in the world, but functional. For anything more serious, QuickBooks has built-in journal entry functionality that auto-populates the accounts and validates debits equal credits before you can save.
When This Approach Fails
The decision-tree method breaks down when your business has transactions that don't fit clean categories. Revenue sharing agreements. Multiple performance obligations in a single contract. Inventory purchases with variable terms. If you are dealing with ASC 606 or IFRS 15 revenue recognition, a simple journal entry framework is not going to cut it. You need a dedicated revenue scheduling tool or at minimum a very careful manual process with documented assumptions for each contract. Another scenario where this gets messy is during system migrations. I had a client switch from a legacy ERP to NetSuite and we discovered that years of inconsistent journal entries meant the opening balances were wrong by roughly 18%. Fixing that required a full three-month retrospective cleanup. It cost them about $15,000 in professional fees and two months of their controller's time. Starting with clean habits from day one would have prevented all of it.
The Bottom Line
Journal entries are not complicated in theory. They are tedious in practice and easy to do carelessly. The best way to journal for accounting purposes is to be boringly consistent. Use a decision framework. Write good descriptions. Reconcile weekly. Don't add sub-accounts unless you have a documented reason for them. And for the love of whatever you respect, never write "miscellaneous" as a description unless you want a future version of yourself to hate you. There is no shortcut that replaces doing it methodically. The people who try to skip steps always end up spending more time fixing things later than they would have saved in the first place.