Worksheet Structure That Actually Works
Most people overcomplicate accounting worksheets. They build these sprawling multi-tab behemoths in Excel with conditional formatting, dynamic arrays, and vlookups chained three levels deep. Then they wonder why the thing breaks every time they add a new account or restructure the chart of accounts. The best way to worksheet for accounting isn't about fancy features. It's about maintaining a clean trial balance, posting adjustments methodically, and keeping financial statements mechanically linked without creating fragile dependency chains.
Best Way To Worksheet For Accounting
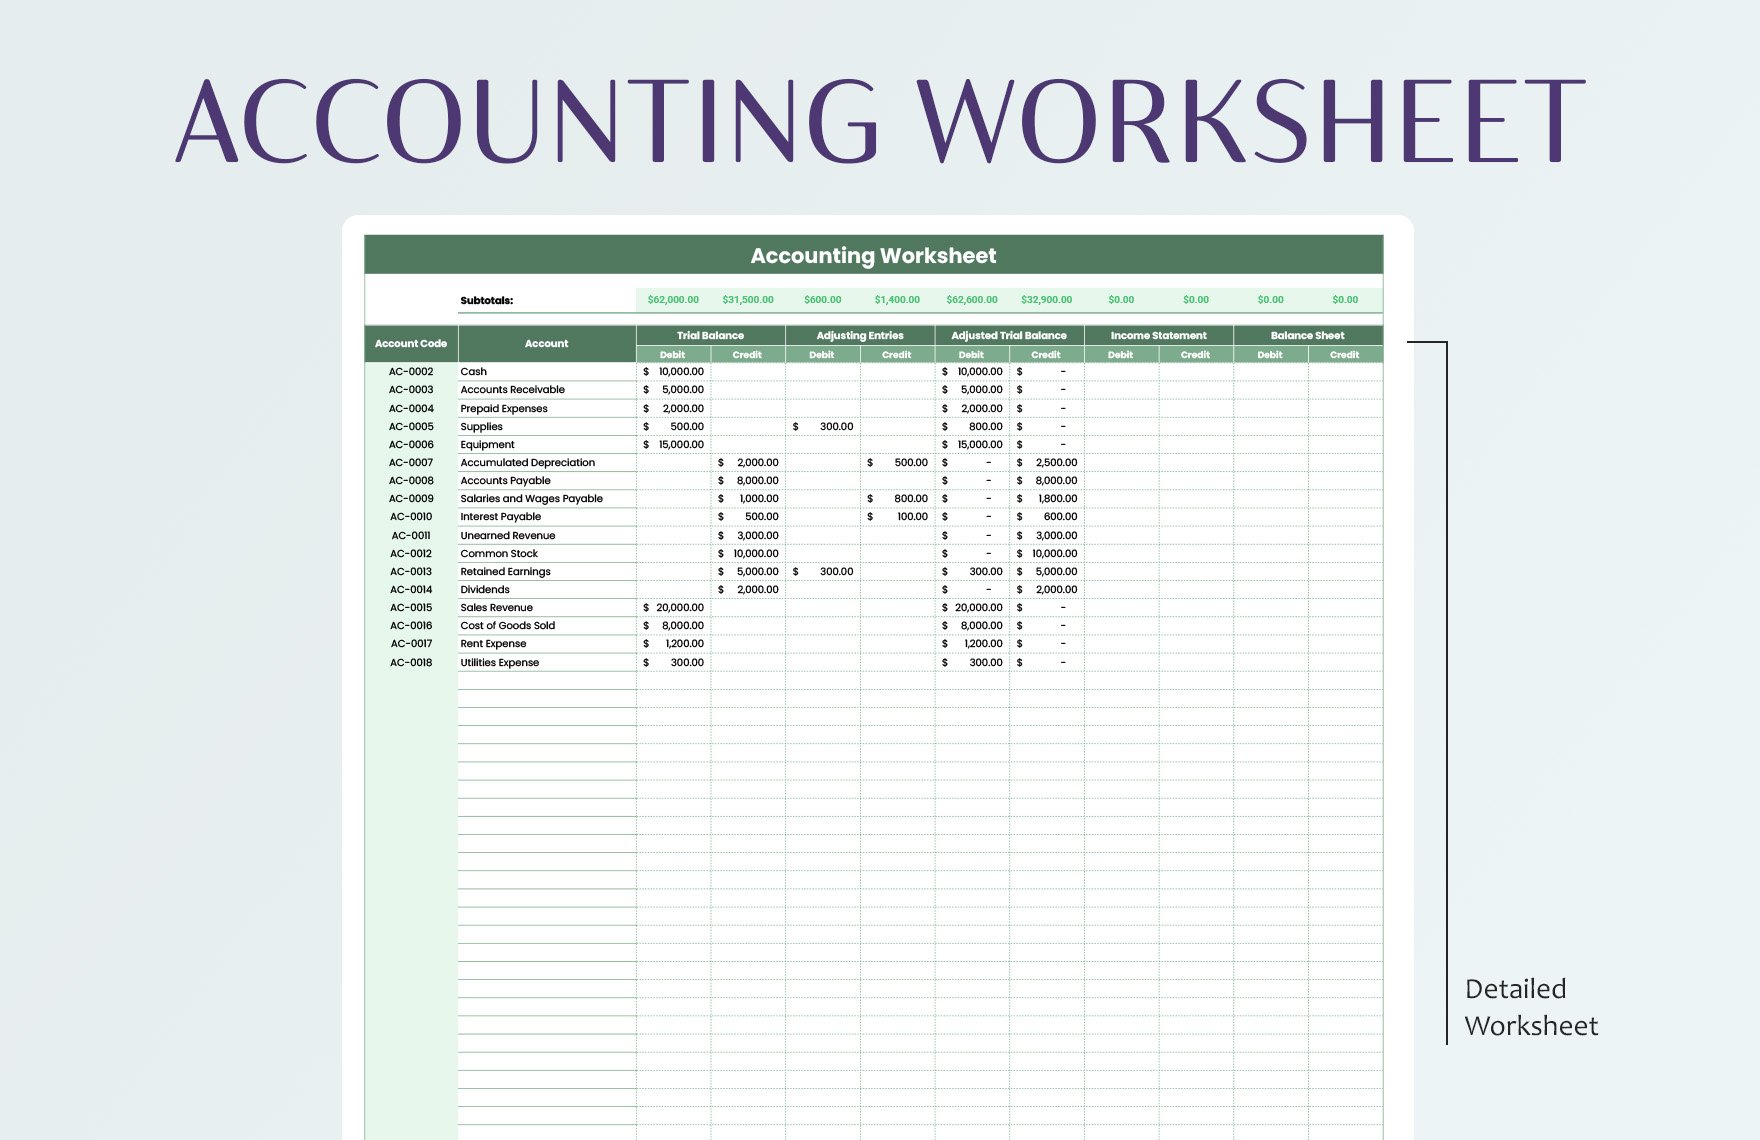
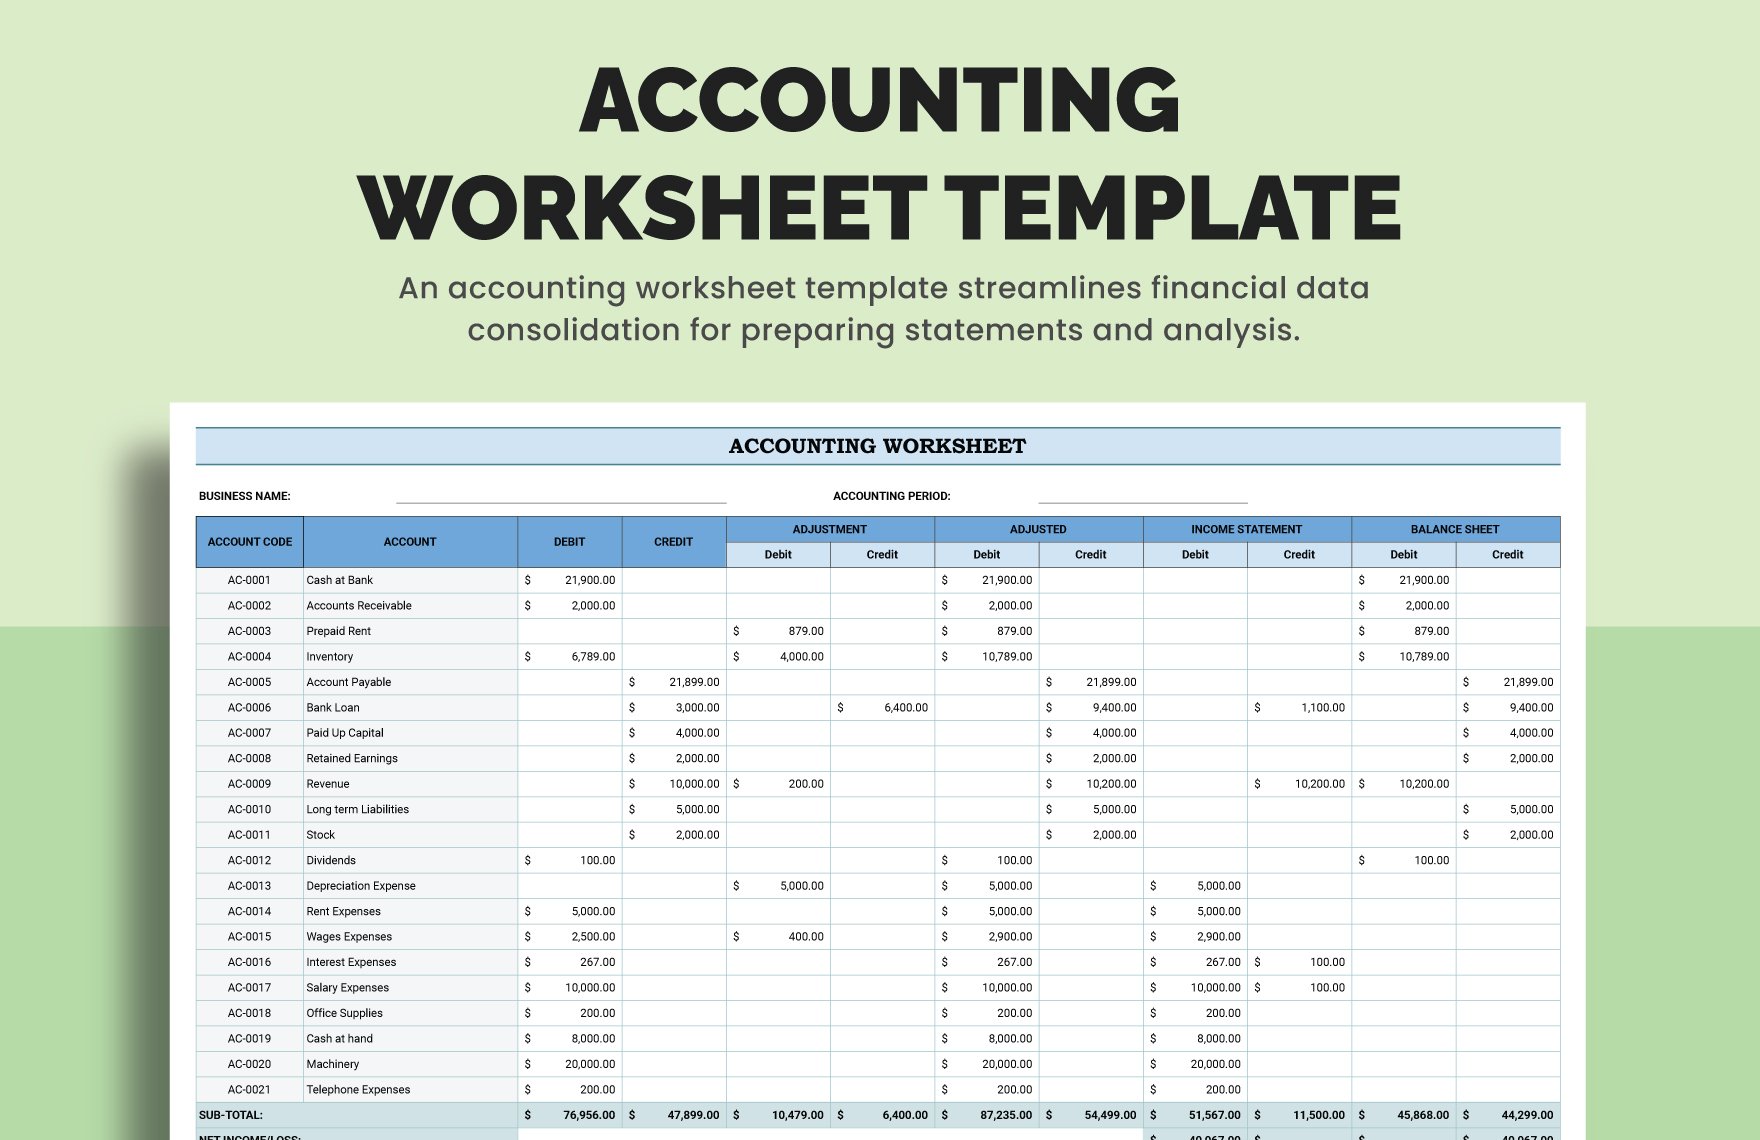
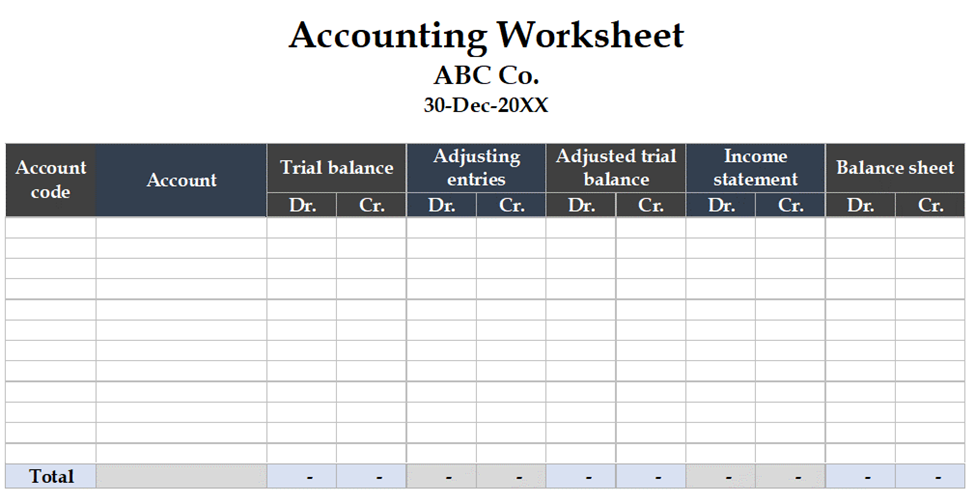
Here's what I've found works in practice. Set up five columns: Trial Balance, Adjustments, Adjusted Trial Balance, Income Statement, and Balance Sheet. That's it. Five columns. Every account in your chart of accounts goes down the first column. Debits and credits sit side by side in each section. You don't need more than that unless you're doing something genuinely unusual like segment reporting across twelve entities. Start with your unadjusted trial balance pulled directly from the general ledger. Run totals. If debits and credits don't match to the penny, stop there and fix it before moving forward. Wasting time on adjustment columns when the foundation is wrong is the most common mistake I see. For adjustments, I use a separate working schedule first rather than posting directly into the worksheet. Journal entries get documented, referenced, and numbered. Each one links back to a source document or calculation sheet. When audit season hits, having that trail means you can find any adjustment in under thirty seconds instead of digging through a month's worth of changes.
I once had a client with a complex lease portfolio—forty-seven operating leases with varying escalation clauses and renewal options. The adjustment entries alone ran sixty-two lines. When I tried to fold that into a standard worksheet, the spreadsheet became nearly unreadable. My workaround was building a dedicated lease schedule as a reference table, then pulling summary adjustment figures into the main worksheet using a simple SUMIFS formula keyed to the lease number. The worksheet stayed clean. The detail lived where it belonged, attached to the source material. The adjusted trial balance column is just the first plus the second. Income statement and balance sheet columns pull from the adjusted balances based on account type. Revenue and expense accounts flow to the income statement column. Asset, liability, and equity accounts go to the balance sheet column. Net income from the income statement column then feeds into retained earnings on the balance sheet side to force the two halves to reconcile. One thing beginners miss: always format your worksheet columns with consistent decimal alignment and avoid merging cells. Merged cells look tidy in screenshots but they destroy any chance of using auto-filters, sorting, or simple formulas later. A properly formatted but unmerged worksheet is infinitely more maintainable than a pretty one that locks you in.
Get the Full Details

Another counter-intuitive point that matters more than people realize. Don't preformat account numbers as text strings if you plan to sort or filter them numerically. Leading zeros get stripped. Account ranges become impossible to select cleanly. Format account numbers as numbers, keep them zero-padded through custom cell formatting if needed, and treat them as numeric values in your formulas. This saves hours during period close when you're pulling subsets of accounts for review. The real bottleneck in worksheet methodology isn't the mechanics. It's version control. I've watched entire month-end closes collapse because someone saved over the working file instead of archiving a copy before making changes. Name your files with a date stamp in YYYYMMDD format and keep at least three versions per close cycle: the starting balance file, the mid-adjustment file, and the final signed-off file. Takes twenty extra minutes and prevents catastrophic data loss. Downsides worth acknowledging. This five-column approach breaks down when you're dealing with multi-currency operations, intercompany eliminations across entities, or consolidation work requiring parent-subsidiary mapping. In those scenarios, a simple worksheet becomes inadequate and you need dedicated consolidation software or at minimum a multi-tab workbook with clearly separated entity sheets and elimination entries documented in their own section.
Another limitation: worksheet-based adjusting entries rely entirely on manual accuracy. There's no automated validation beyond your own review. A missed deferral, an incorrect accrual rate, or a transposed decimal will sit there looking perfectly reasonable until someone actually tests the financial statement line items against supporting documentation. Building a small reconciliation checklist alongside your worksheet—comparing each adjusted account balance back to its subledger or supporting calculation—catches most of these before they become problems. Software alternatives exist. QuickBooks, Xero, and similar platforms handle worksheet-level functions internally. But they obscure the mechanics. When something goes wrong and you need to debug why retained earnings doesn't reconcile, not understanding the underlying worksheet structure makes troubleshooting guesswork. I recommend maintaining a proper worksheet even when using accounting software, at least until you're comfortable reading and auditing the output yourself. For a downloadable template matching this approach, most accounting professionals build their own starting from a blank workbook with the five-column structure described above. Generic templates available online tend to have embedded formulas that assume specific account configurations, which creates more friction than they save during actual use.
The whole process usually takes between forty-five minutes and two hours depending on transaction volume and whether you're doing it for the first time or on autopilot. The structure itself doesn't change meaningfully from month to month once you've got the routine down. The variation comes from the number of adjustments and how much detail lives outside the worksheet in supporting schedules.