How Bi-Monthly Car Payments Actually Work
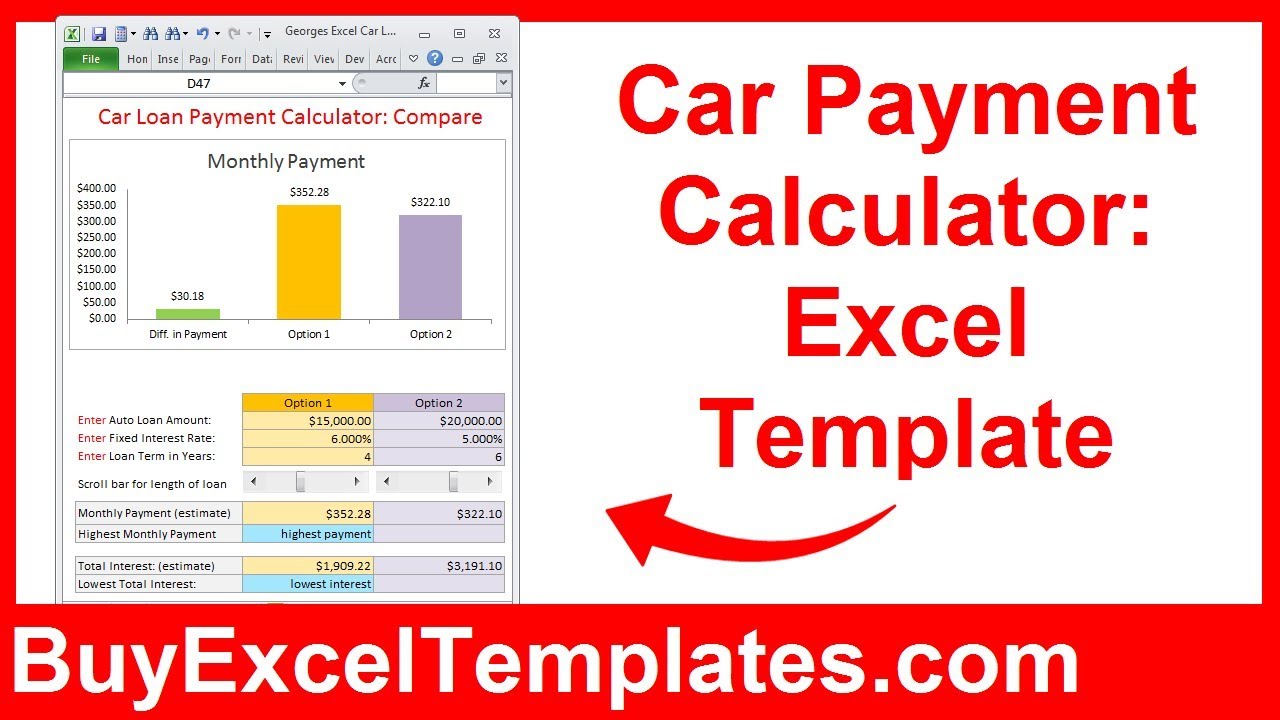
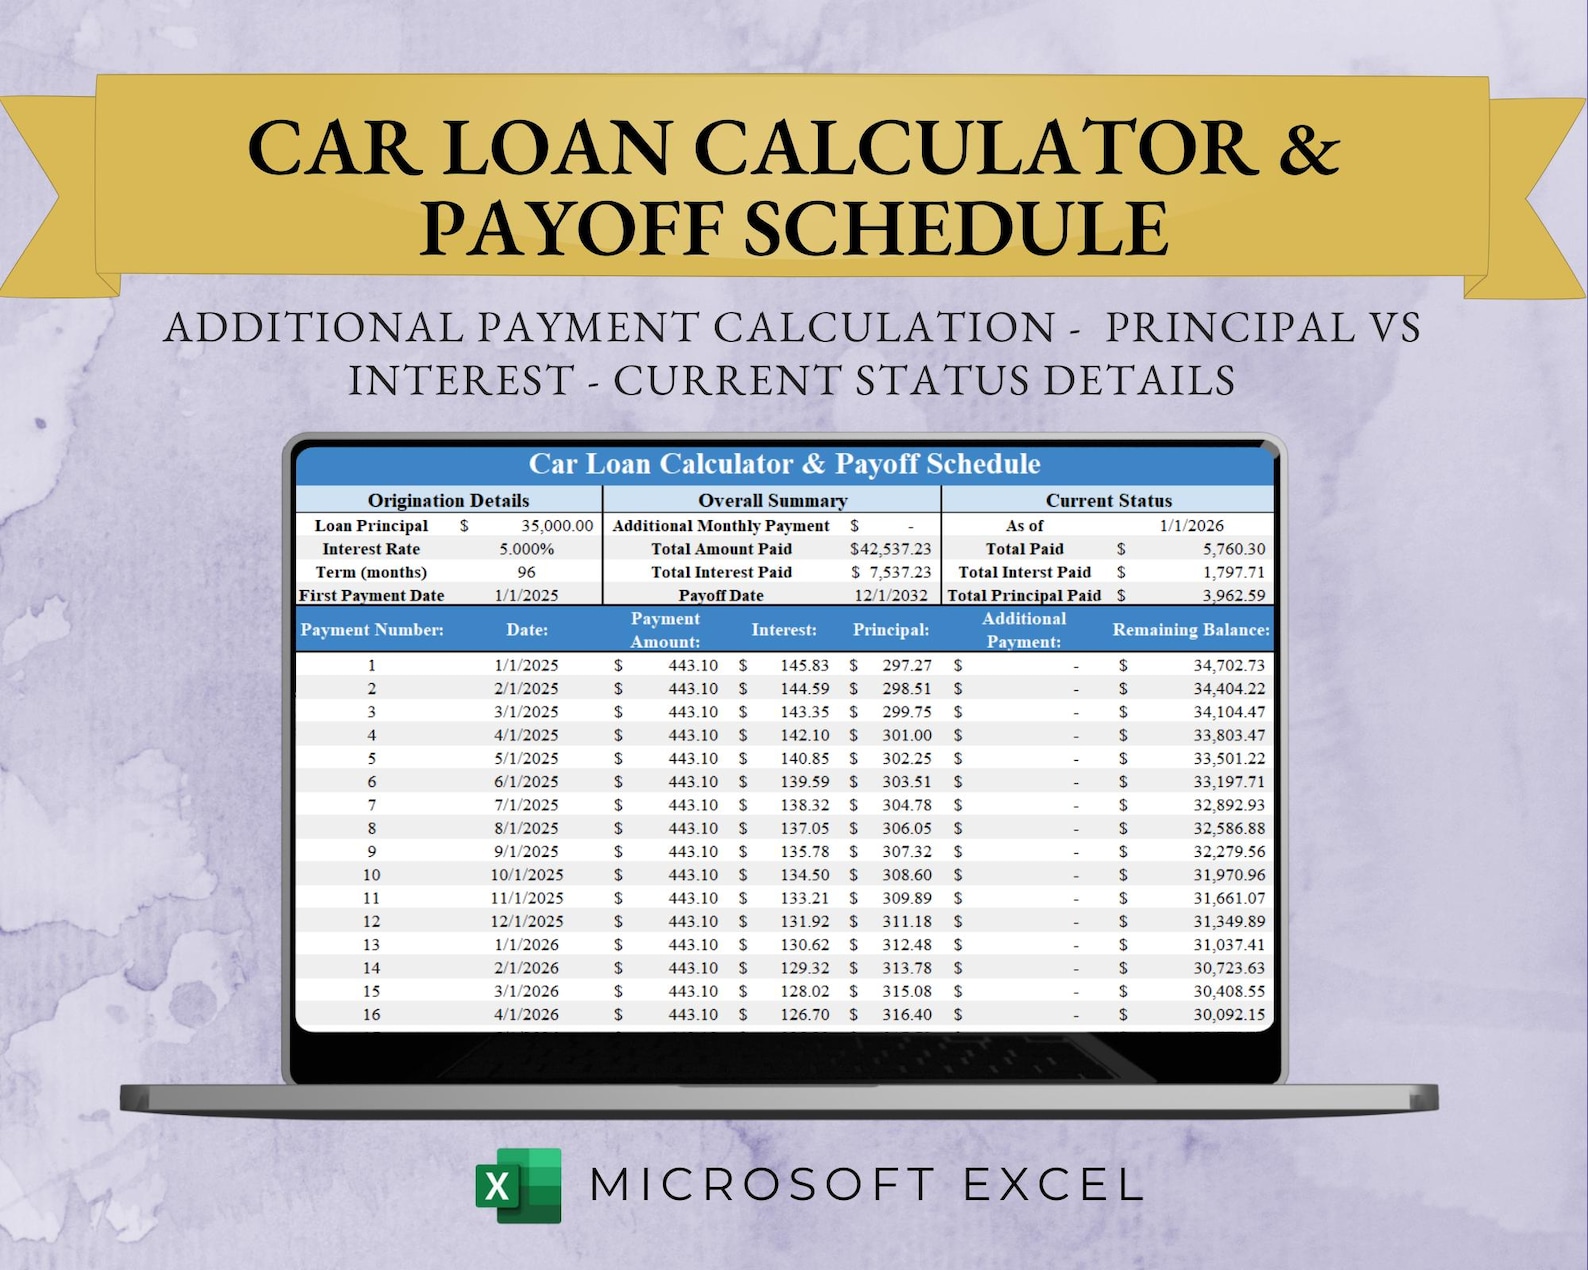
A bi-monthly car payment means paying half your monthly payment twice a month, so you make 24 payments instead of 12. That sounds like extra work for no real reason, but it's one of those things lenders quietly promote because it reduces their risk and slowly chips away at your principal faster than you'd notice. Here's the straightforward method. Take your monthly payment amount, divide it by two, and multiply the number of payments by the rate. Most lenders use a standard amortization formula, but when you switch to bi-monthly, you're effectively making one extra full payment per year. That extra payment eats into principal, which shortens the loan term and saves you interest over time. The math breaks down like this. If your car loan is $28,000 at 6.5% annual rate over 60 months, your regular monthly payment comes out to roughly $547.50. Split that in half and you pay $273.75 every two weeks. Over a year that's $6,570 going out instead of the $6,570 you'd pay on a standard schedule, but the difference is timing. Because each payment hits sooner, the average daily balance drops faster, and the total interest paid over the life of the loan decreases by maybe $400 to $700 depending on your rate and term.
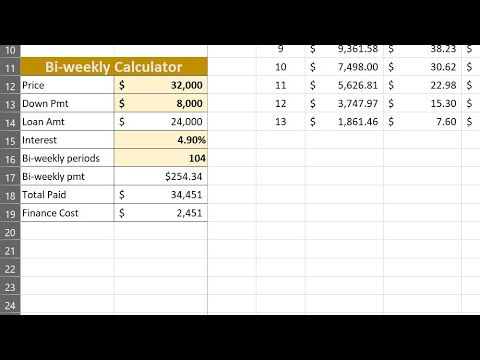
I ran into this exact scenario a few years back when I refinanced a truck loan. The lender's online calculator showed the bi-monthly option saving me $523 in interest over five years. But here's what they don't put in big letters on their website: some lenders charge a setup fee for bi-weekly payment plans, usually between $25 and $75, and a few actually add a small per-payment processing charge. I had to dig through the fine print of my promissory note to find out I was being hit with a $49 origination add-on that would eat up nearly a third of the savings in year one. If you're going to do this, check whether your loan agreement has any hidden fees attached to the payment frequency. Another thing people miss is how bi-monthly payments interact with your actual calendar. Two weeks is not exactly half a month. Some months squeeze in three payment dates instead of two, which means you end up making 26 half-payments a year rather than 24. That's even more aggressive principal reduction, but it also means your cash flow gets a little bumpy. You need to be comfortable with an extra payment hitting your account in certain months or you'll find yourself scrambling to cover it. If you want to run the numbers yourself, here's a simple formula you can drop into a spreadsheet:
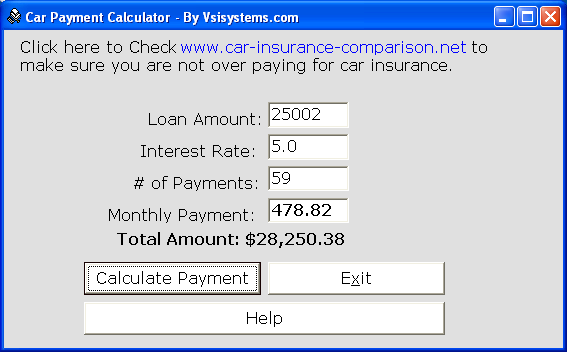
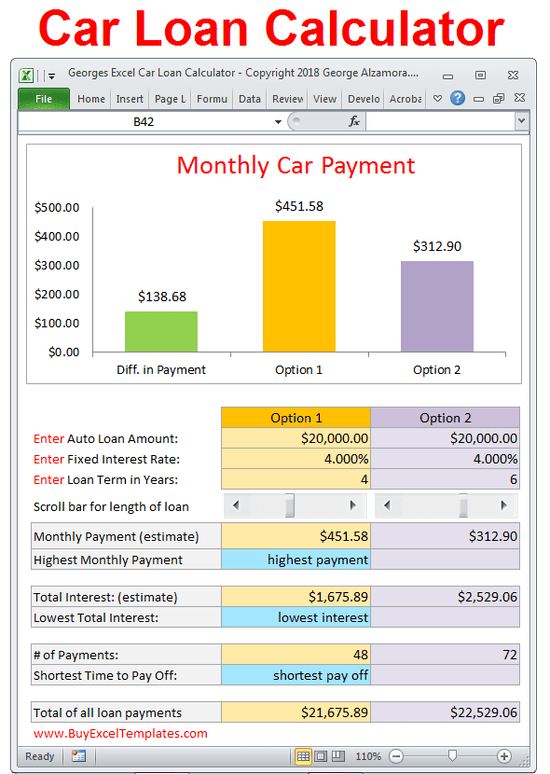
Payment = (Principal × Monthly Rate) / (1 - (1 + Monthly Rate)^-Number of Payments) Where Monthly Rate is your annual percentage rate divided by 12, and Number of Payments is your loan term in months. For the bi-monthly version, just halve that result and double the payment count. Most free online calculators will do this automatically if you search for "bi-weekly auto loan calculator." The output will show you the revised payoff date and total interest savings side by side with your original schedule. The real bottleneck with this approach isn't the math. It's commitment. Bi-monthly payments require you to stay on track for the entire loan term. Miss a payment or skip a cycle and the whole accelerated payoff plan unravels. You also need to verify with your lender that they actually apply bi-monthly payments correctly to principal, because a handful of smaller servicers will still process them as if they were standard monthly payments and waste the benefit.
Get the Full Details
Bottom line, if your budget can handle the rhythm and your lender doesn't nickel-and-dime you, it's a legitimate way to shave a few months off your loan and save a modest amount on interest. Just read the paperwork before you sign up.