How Bi-Weekly Payments Actually Work
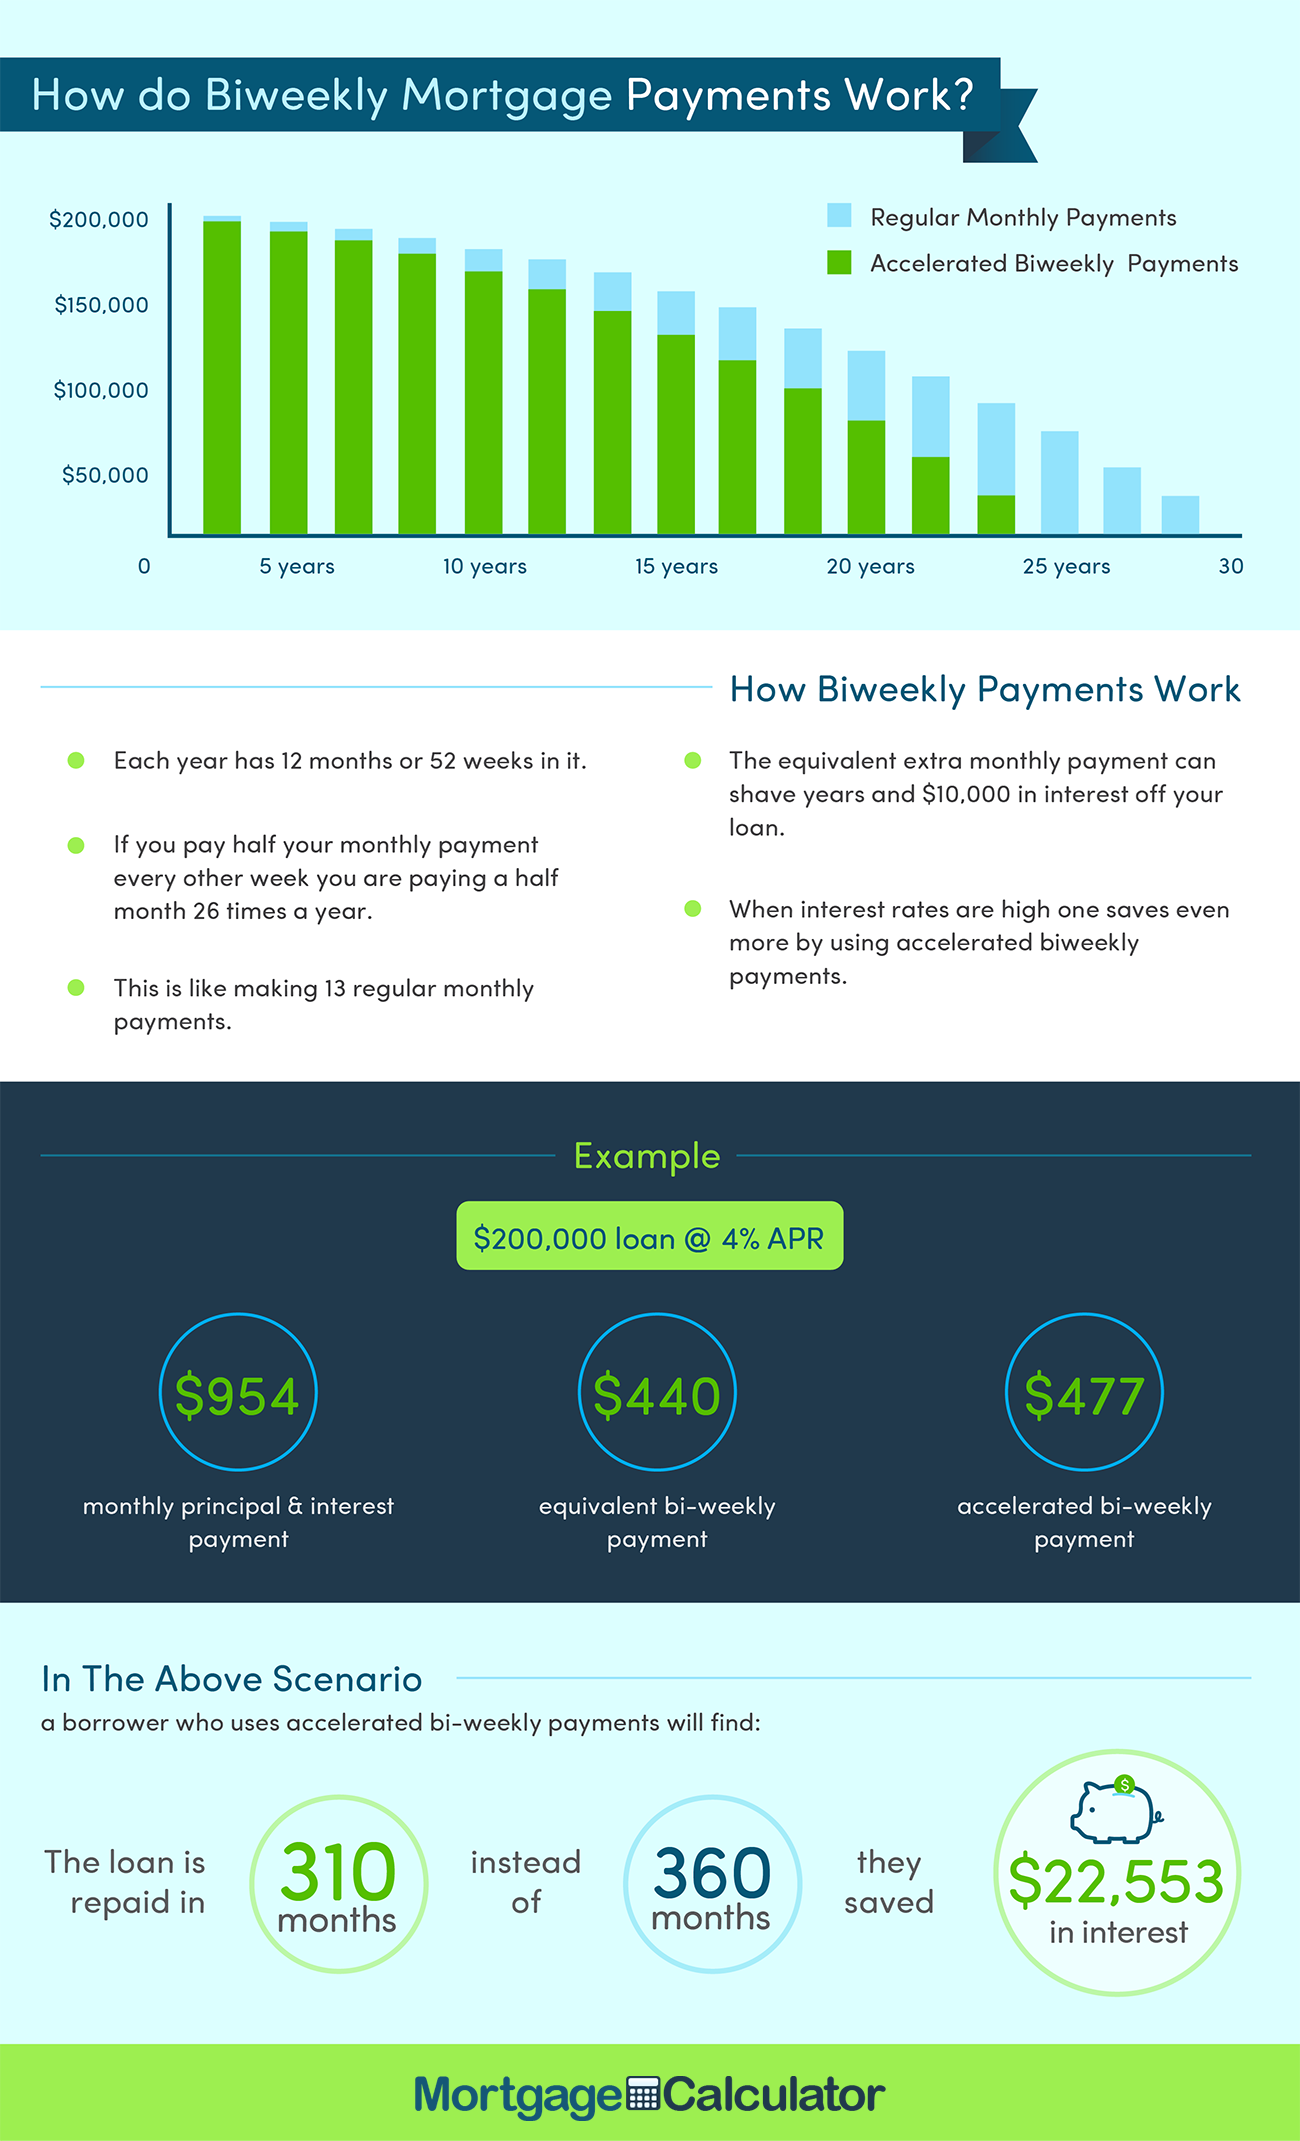
A standard mortgage takes 12 payments a year. A bi-weekly schedule means you pay every two weeks, which is 26 half-payments or 13 full monthly payments annually. That extra payment goes straight to principal, and over the life of a loan it shaves years off the term. The math is straightforward. The reality of setting it up is where people run into issues. Most people I talk to assume they can just manually pay every two weeks and call it a bi-weekly mortgage. You can do that, but if your servicer doesn't explicitly offer a bi-weekly program, you're doing manual math on your own and hoping the payment hits correctly. It usually does, but gaps happen. I've seen two cases where a borrower thought they were on a bi-weekly schedule when their servicer was actually applying the payments to a standard monthly cycle. No harm was done since the payment amounts were the same, but the interest calculation was wrong on paper and created a reconciliation headache at tax time.
Using a Bi Weekly Mortgage Calculator
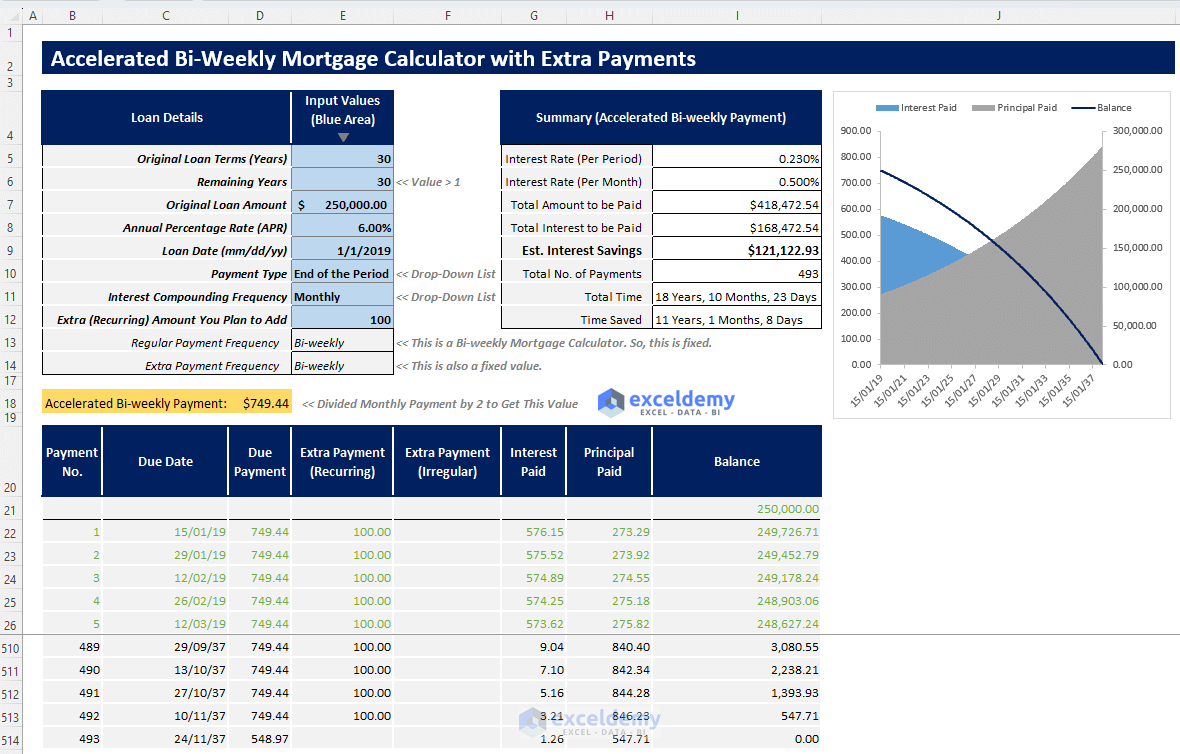
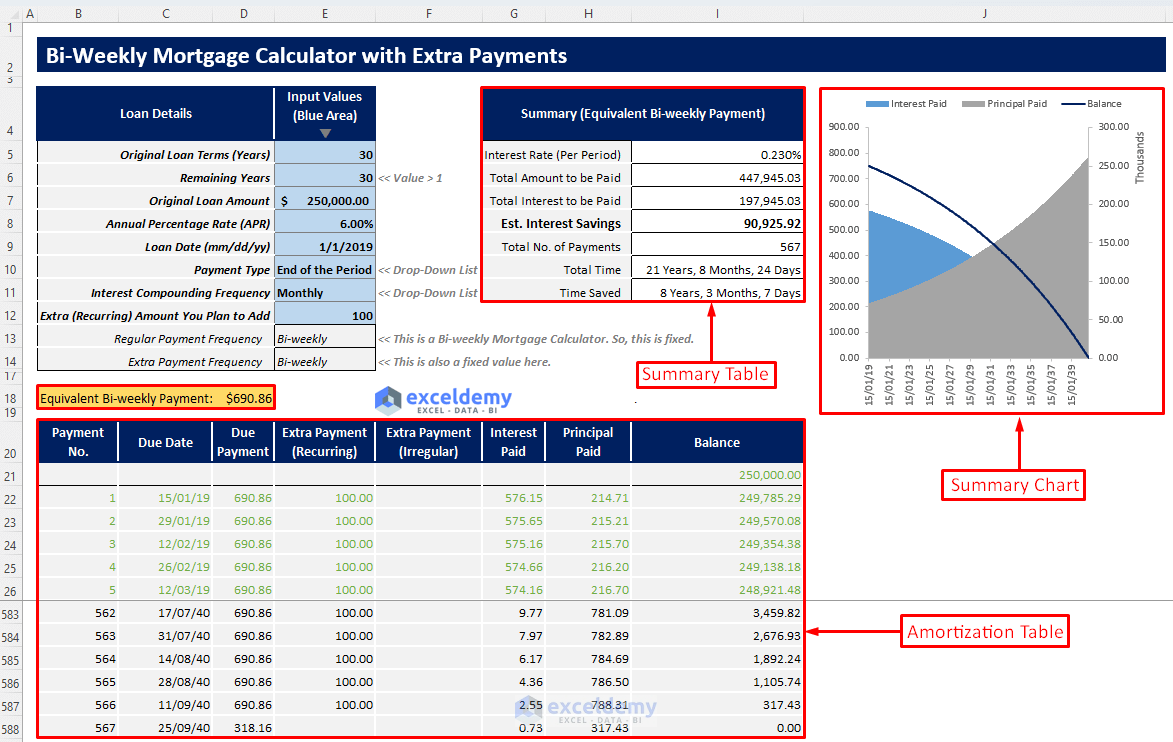
Here's the practical way to approach this. Start by inputting your current loan balance, your interest rate, and your remaining term into a Bi Weekly Mortgage Calculator. The tool will show you the bi-weekly payment amount, which is typically half your monthly payment. Then compare the total interest paid under both schedules side by side. That's the number that matters most. The reason people skip the calculator step is they think they already know the answer. They don't. The difference between paying off a 30-year loan in 24 years versus 26 years depends heavily on your specific rate and remaining balance. A calculator removes the guesswork. One thing most online calculators get wrong or don't mention clearly: not all servicers apply extra principal immediately. Some hold bi-weekly payments in a suspense account until the end of the month and then process them as a single monthly payment. This is rare but it happens, especially with smaller regional lenders. Before switching, call your servicer and ask how they handle bi-weekly payments. Get it in writing if possible. I learned this the hard way with a client who switched to bi-weekly through their online portal and discovered six months later that their payments were being lumped together. We had to recalculate the entire amortization and negotiate with the servicer to correct the record. It took about four hours of phone calls and two weeks of back-and-forth emails. Not ideal.
What the Numbers Actually Show
Take a $300,000 loan at 6.5% over 30 years. Your monthly payment is roughly $1,896. Under a bi-weekly schedule, you'd pay about $948 every two weeks. That adds up to 26 half-payments or 13 full payments per year instead of 12. On a standard calculator, this looks like it saves about 4.5 years and roughly $40,000 to $50,000 in interest depending on the exact terms. But here's the part nobody mentions casually: the actual savings depend on whether you were already making extra principal payments before switching. If your current monthly payment already includes extra principal applied toward the balance, the incremental benefit of going bi-weekly shrinks considerably. I had a borrower once who was already overpaying by $200 a month and thought switching to bi-weekly would be transformative. It cut his term by about a year and a half instead of four. The math was correct, but his expectation was inflated because he hadn't accounted for his existing overpayment behavior. Another counter-intuitive point: bi-weekly payments reduce interest faster than monthly payments not just because of the extra payment, but because of the timing. Each bi-weekly payment reduces your principal balance sooner in the compounding cycle than a monthly payment would. The effect compounds. But only if your servicer is actually crediting the payment on the date you make it. Again, that's why confirming with your servicer matters more than reading about it online.
Get the Full Details

Pitfalls and Where It Falls Apart
Bi-weekly payment programs aren't free. Many lenders charge a setup fee between $75 and $300 and a monthly servicing fee of $5 to $15. Over five years, those fees add up to $375 to $1,200, which erodes some of your interest savings. Calculate the net benefit after fees before committing. A $300,000 loan at 6.5% might look like it saves $45,000 in interest, but after $900 in fees over five years, you're down to $44,100. Still significant, but you need to see the full picture. Some borrowers also assume they can stop their automatic monthly payment and just make bi-weekly payments on their own. This is risky. If you miss a bi-weekly payment or your account doesn't have enough funds on a specific date, you could trigger a late fee or, worse, your servicer could continue processing the full monthly payment and applying it as if you were still on the standard schedule. The result is a confused payment history and no real progress toward the bi-weekly structure. The cleanest approach is to either enroll through your lender's official bi-weekly program or set up two separate automatic payments from your own account every two weeks, making sure one of them is labeled as an additional principal payment. If you go the DIY route, keep a spreadsheet. Track each payment date, the amount applied to principal, and the remaining balance. When I do this for clients, I use a simple Google Sheet with columns for payment date, bi-weekly amount, principal portion, interest portion, and remaining balance. It takes about 20 minutes to set up and saves you from having to reconstruct anything later.
Who Should and Shouldn't Use This
Bi-weekly payments work best for borrowers with a stable income who can commit to the same payment every two weeks without variation. If your income is irregular or seasonal, the fixed bi-weekly schedule can create cash flow problems during lean months. A monthly schedule gives you more flexibility to adjust timing. I've seen freelancers and commission-based workers get stuck because they couldn't make a payment on a specific bi-weekly date and ended up paying late fees for three or four months straight. If you're close to paying off your mortgage already, the benefit of switching to bi-weekly is minimal. The interest savings are front-loaded, meaning most of the benefit comes in the early years of the loan. If you have five years left on a 30-year mortgage, going bi-weekly might save you a few hundred dollars in interest and a couple of months off the term. That's not nothing, but it's not dramatic either. In those cases, making a larger lump-sum principal payment achieves the same result faster and without the administrative overhead. The most common mistake I see is people signing up for a bi-weekly program through a third-party service rather than their lender. These services often promise faster payoff and lower rates, but they're just automating the payment schedule. They don't change your interest rate or negotiate better terms with your servicer. The savings come entirely from the extra annual payment, which you could arrange yourself for free. I've had clients waste $500 to $800 on third-party bi-weekly services when they could have set it up on their own in an afternoon.