Working the Spread: What It Actually Looks Like
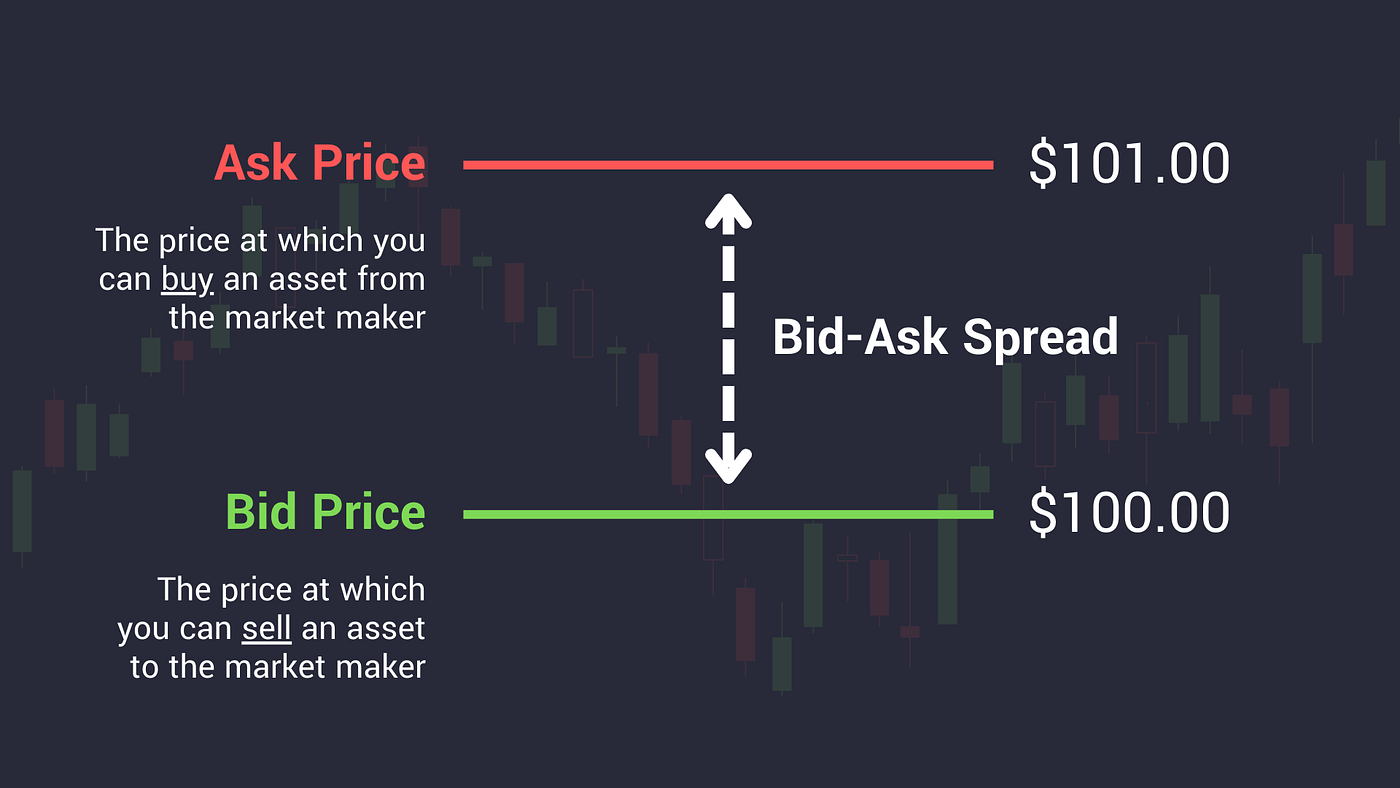
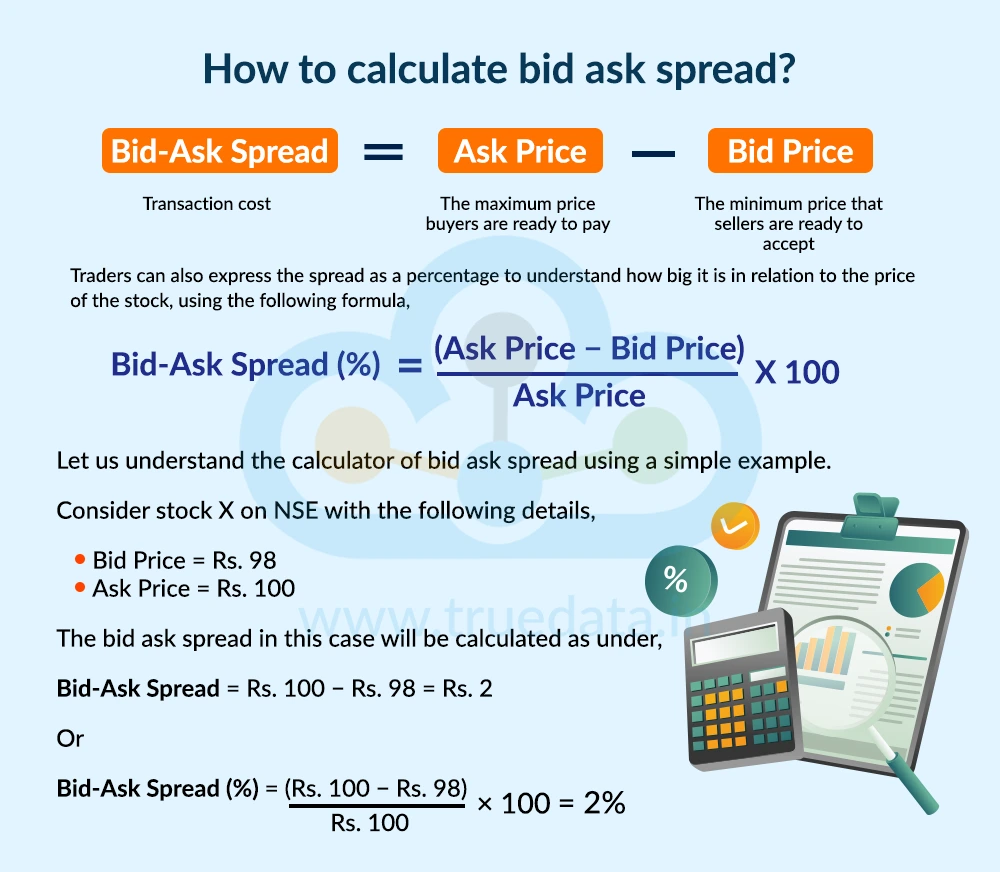
The bid-ask spread is just the gap between what someone will pay and what someone will sell for at any given moment. Most people see it as a cost. It can also be the edge itself, depending on how you approach it. I spent years watching order books across equities, futures, and crypto markets. The spread isn't static. It compresses and expands based on volatility, liquidity conditions, time of day, and even the size of orders hitting the book. The strategies that work are the ones that account for all of that instead of treating the spread as a fixed number.
Core Bid Ask Spread Trading Strategies
There are several legitimate approaches. They range from institutional-scale market making to retail-executable spread capture techniques. Passive liquidity provision is the most straightforward. You place limit orders on both sides of the book — a bid below the current price and an ask above it — and you profit from the spread when both orders fill. This is essentially what market makers do, minus the regulatory overhead. The catch is that you're taking inventory risk. If the market moves against your positions before both sides fill, you eat the loss. Spread capture is slightly more active. You're looking for moments when the spread widens abnormally relative to its historical average and you step in to provide liquidity at those wider levels. This tends to happen during earnings announcements, macro events, or periods of low participation like the first fifteen minutes after a futures market open. I found that checking the spread against a rolling 20-period standard deviation gave me a reasonable signal for when it was genuinely wide versus just normally wide.
Statistical arbitrage across correlated instruments is another angle. If two closely related assets — say, a stock and its corresponding futures contract, or two ETFs tracking the same index — temporarily diverge in their spread dynamics, you can trade the convergence. This requires low-latency execution and tight transaction cost modeling. It's not something you can casually run from a retail platform. Order flow toxicity analysis is the strategy most beginners don't consider. Instead of looking at the spread itself, you look at whether the orders moving the market are informed or uninformed. A narrow spread with heavy informed flow is dangerous. A wide spread with mostly retail flow is an opportunity. VPIN and similar metrics attempt to quantify this, though they have their own limitations.
Get the Full Details

How to Actually Execute These Strategies
Theory is cheap. Execution is where things fall apart. For spread capture, start by identifying your target instrument and pulling at least six months of tick-level or at minimum one-second snapshot data. You need to establish what normal looks like for that asset. Calculate the average spread, the standard deviation, and the correlation with volume. Most retail traders skip this step and trade based on a single wide spread they see on their screen, which is like betting the market will stay broken when it hasn't actually broken. Set your order placement rules. If you're doing passive liquidity provision, your bid should typically sit one to two ticks below the best bid and your ask one to two ticks above the best ask. Going deeper into the book reduces fill probability. Going shallower increases the chance you get run over by a market order. There's asweet spot that varies by instrument, and the only way to find it is through backtesting and then small live trials.
Position sizing matters more than people admit. A common mistake is allocating too much capital to a single spread play. The fill rate on passive quotes is inherently unpredictable. You might have three bids and three asks sitting there for twenty minutes and then get hit on one side by a large order that moves the market five ticks against you. If you're overexposed on that side, the math stops working. For statistical arbitrage approaches, you need to model transaction costs explicitly. Include the spread cost, any commission structure, and the slippage you'll face when exiting. A strategy that looks profitable on paper often turns negative once you factor in that a two-tick spread becomes a four-tick round-trip cost minimum. Some venues offer rebate structures that offset this, but those are generally available only to firms with significant volume commitments.
A Specific Problem I Ran Into and How I Handled It
During a particularly volatile session trading E-mini S&P futures, I noticed the spread would occasionally jump to six ticks instead of the normal two-to-three tick range. This happened roughly once every forty-five minutes and usually during the transition between the cash open and full futures trading activity. My initial approach was to widen my quotes proportionally, but I kept getting filled on one side and not the other, leaving me exposed. The workaround was to stop treating the spread as a simple distance metric and start watching the queue depth. When the spread widened, I'd check whether there was actually a thin book behind the best prices or if it was just a temporary quote gap. In most cases, the order book wasn't thin — there were just no visible quotes in that price range because larger players were resting their orders deeper. Once I started placing my quotes two to three ticks deeper than the displayed spread rather than adjacent to the best bid-ask, my fill asymmetry dropped significantly and my inventory exposure became manageable.
Pitfalls That Will Hurt You
The biggest trap is assuming spreads behave predictably across different market conditions. A spread that's stable during normal trading hours can widen unpredictably during news events, and if you're holding quoted positions through those windows, you can lose money fast. I've seen traders get run over on both sides of their quotes during a Federal Reserve announcement because they didn't pull their orders quickly enough. Another issue is overfitting your strategy to historical spread behavior. Markets evolve. Exchange fee structures change. New participants enter. A spread capture strategy that worked in 2022 may not work the same way now simply because the liquidity landscape shifted. You need to review and recalibrate your parameters regularly, not set them and forget them. There's also the problem of survivorship bias in backtests. Many publicly available spread strategy results don't account for the fact that many of the instruments or venues being tested have since changed their trading rules, delisted products, or modified their fee schedules. Always verify that your backtest environment matches current market conditions as closely as possible.
What This Approach Can and Cannot Do
Spread trading strategies can generate consistent returns in the right conditions, but they are not a substitute for having a edge in market structure understanding. The strategies require active monitoring, rapid decision-making, and sometimes direct market access. If you're trading from a standard retail platform with slow order routing, your effective spread will be worse than what the displayed quotes suggest, and your strategy margins shrink accordingly. These strategies also scale poorly for small accounts. The fixed costs of data feeds, platform fees, and the capital required to hold inventory through adverse moves mean that you're typically looking at accounts in the five to six figure range to make this approach viable. Below that threshold, the transaction costs and opportunity costs tend to dominate. The most sustainable approach I've seen combine spread capture with a directional bias filter. Instead of purely providing liquidity on both sides, you tilt your quoting toward the side you have a slight edge predicting. This reduces your inventory risk while still allowing you to earn the spread on the other side. It's not a perfect solution, but it's more robust than pure two-sided quoting in most market environments.