Tracking the Big Pharma Landscape
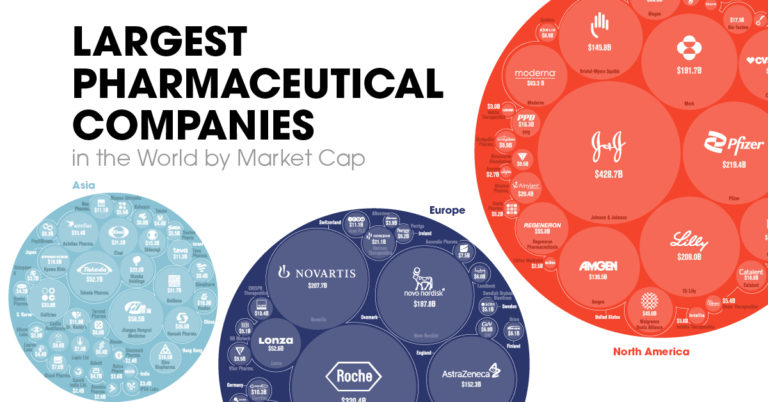
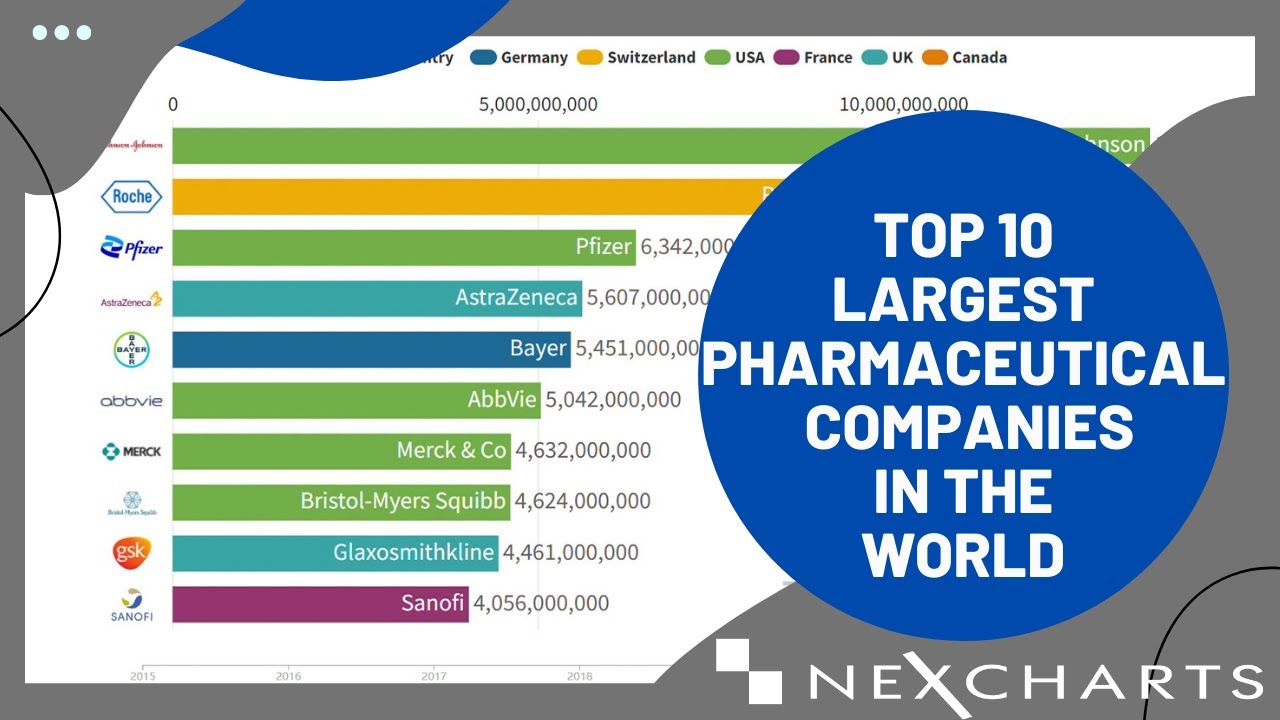
Most people ask about the biggest pharmaceutical companies because they want a quick ranking. The rankings exist, sure, but they shift every quarter based on patent expirations, clinical trial outcomes, and activity that most analysts don't track until it's already priced in. If you're looking at this from an investment angle or just trying to understand the competitive dynamics, here's what actually matters beyond the headlines. Looking at 2024 through mid-2025 data, the revenue leaders break down roughly like this. Eli Lilly and Novo Nordisk have been climbing fast, driven by GLP-1 agonists for diabetes and obesity. Pfizer, Merck & Co, Johnson & Johnson, AbbVie, Roche, Sanofi, AstraZeneca, Bristol Myers Squibb, and Amgen round out the top tier. But the order changes depending on whether you measure by annual revenue, market cap, or pipeline value. Revenue rank and market cap rank are not the same thing. A company can have huge revenue from a single blockbuster drug that's about to lose patent protection, while another with lower current revenue has a pipeline that will dominate in three years. Market cap reflects the latter more than revenue does.
What Actually Drives Rankings in This Space
Pharmaceutical company rankings are heavily influenced by patent cliffs, clinical trial results, regulatory approvals, and licensing deals. A single Phase 3 failure can drop a company dozens of places in market cap within a week. A regulatory approval from the EMA or FDA can do the opposite. I've watched this happen repeatedly. Patent expiration is the single biggest risk factor. When a patent expires, generic competition typically erodes 80 to 90 percent of revenue within two years unless the company has successfully diversified. That's why companies like Eli Lilly and Novo Nordisk are investing so aggressively in their next generation of candidates. They know the clock is ticking on their current revenue drivers. Another factor nobody talks about enough is the reimbursement environment. A drug can get FDA approval and still fail commercially if insurers and PBMs negotiate it into a low formulary tier. This is especially relevant in the US market, where the Inflation Reduction Act gave Medicare power to negotiate drug prices for the first time. That changed the calculus for companies with high-priced specialty drugs.
Common Mistakes People Make
The biggest error I see is relying on a single source for rankings. Some financial websites update their lists annually with stale data. Others use market cap without accounting for debt, which makes leveraged companies look smaller than they effectively are. I learned this the hard way when I was building a competitive analysis for a mid-cap biotech looking at acquisition targets. I had initially ranked companies purely by market capitalization and ended up with a list that completely misrepresented their actual pharmaceutical revenue generation. The fix was pulling SEC filings directly, specifically the 10-K and annual reports, and cross-referencing with FDA approval databases and clinical trial registries. It took longer, about three weeks instead of two days, but the final ranking was accurate. Don't trust aggregators. Go to the source. Company investor relations pages, SEC EDGAR, and the FDA website all have raw data that's more reliable than any third-party summary.
Get the Full Details
Pipeline Value Matters More Than Current Revenue
If you want to predict where these companies will be in five years, look at their R&D pipeline, not their current bestseller. Companies like AstraZeneca and Roche invest heavily in immuno-oncology and rare diseases. Their pipeline depth gives them optionality that pure revenue metrics don't capture. The pipeline also reveals strategic direction. A company accumulating oncology assets is betting on precision medicine and combination therapies. A company focused on Alzheimer's and neurodegeneration is making a different bet entirely. These choices determine which patent cliffs they can survive and which new markets they can capture.
The GLP-1 Disruption
GLP-1 receptor agonists like semaglutide and tirzepatide have reshaped the competitive landscape faster than almost anyone predicted. Eli Lilly and Novo Nordisk control the vast majority of this market. Other big pharma companies are scrambling to develop alternatives or enter combination therapies. This isn't a minor product line. It's a multi-hundred-billion-dollar opportunity that will determine market positioning for the next decade. The supply chain constraint is real too. Both companies have struggled to produce enough to meet demand. I spoke with a manufacturing consultant who works in this space, and they confirmed that the peptide synthesis process is notoriously difficult to scale. This is a structural bottleneck that favors companies with vertical integration and experience in biologic manufacturing.
What I Wish People Knew
Most people think big pharma is about research and development. It is, but it's equally about regulatory strategy, commercial access, and manufacturing scale. A great molecule with no path to reimbursement and no ability to manufacture at commercial scale is worth less than an adequate molecule with excellent market access. The companies that understand this best build integrated organizations. They don't just discover drugs. They navigate FDA and EMA pathways, negotiate with payers before launch, and design manufacturing processes that can be scaled. This is why vertically integrated companies like Roche and Johnson & Johnson remain dominant despite not always having the absolute best pipeline in any single therapeutic area.

Where to Find Reliable Data
For accurate and current information on the Biggest Pharmaceutical Companies In The World, I recommend starting with company SEC filings, annual reports, and investor presentations. Clinical trial data comes from ClinicalTrials.gov and the EU Clinical Trials Register. Regulatory decisions are published on the FDA and EMA websites. Industry reports from IQVIA, Evaluate Pharma, and Citron Research provide additional context, but treat those as secondary sources. The data is all publicly available. You just have to know where to look and how to interpret it. Most people don't. That's why the rankings you find on first-page search results are often wrong or outdated.