Understanding Bike In Loan Financing
A Bike In Loan is a secured loan specifically designed for purchasing a bicycle, typically offered by specialty lenders, credit unions, or bicycle retailers as part of a financing partnership. The structure is straightforward: you borrow money to buy a bike, and the bike itself serves as collateral until you pay off the balance. This is different from an unsecured personal loan because the lender has a direct claim on the asset, which is why rates tend to be lower than you'd get from a typical credit union personal loan. I've worked through several of these with customers over the years, and the main thing people get wrong is reading the annual percentage rate alone. The real cost lives in the fee structure. Some lenders charge origination fees between 1 and 3 percent of the loan amount, which on a $2,500 bike loan means an extra $25 to $75 right upfront. Others bury costs in monthly servicing fees or prepayment penalties. You need to look at the total amount repaid, not just the monthly payment and the headline rate.
Bike In Loan Application Process
The application process for a bike loan typically runs through one of three channels: directly through a bicycle dealer who has a lending partnership, through a credit union's recreational equipment loan program, or through online specialty lenders. Each path has different timelines and requirements. Dealer-partnered loans are usually the fastest route. I had a customer last year who needed a bike for a new commute job starting Monday. We submitted the application through the dealer's financing desk on Friday afternoon, got approved by Saturday morning with a soft credit pull, and picked up the bike that same day. The whole process from application to ride-out took about 36 hours. That speed comes from the dealer handling most of the paperwork and the lender having a streamlined approval workflow for standard loan amounts under $5,000. For amounts above that threshold, or if you have a thin credit file, expect the process to stretch to 5 to 7 business days. You'll need proof of income, a valid ID, your current address verification, and sometimes a down payment of 10 to 20 percent depending on the lender's risk model. Credit unions tend to be more flexible with borderline credit scores, while online specialty lenders often require a minimum score of 620 or higher for their best rates.
How the Loan Structure Actually Works
Here's where people don't pay attention. Bike In Loan products usually come as fixed-rate installment loans with terms ranging from 12 to 60 months. The monthly payment is calculated using a standard amortization schedule, meaning early payments are mostly interest and principal pays down slowly at first. On a $3,000 loan at 8.5 percent over 36 months, you're looking at roughly $97 per month, but the first six months of that total about $155 in interest charges. If you pay it off early in month 12, you've already paid most of the interest cost and won't save much by prepaying. This is the counter-intuitive part that lenders don't advertise: shortening the term on a bike loan rarely saves you meaningful money unless you're paying below 6 percent interest. At higher rates, you're better off keeping the loan at the original term and investing the difference elsewhere, or simply making no extra payments and accepting the interest cost as the price of liquidity. I've seen customers aggressively prepay 10 percent APR bike loans only to realize later they were carrying higher-interest credit card debt that would have cost far more over time. The collateral aspect matters more than most borrowers expect. Since the bike is secured against the loan, the lender will typically require you to maintain insurance on the bicycle for the duration of the loan term. This isn't optional. If you cancel the insurance or let it lapse, the lender can force-place insurance at rates that are significantly higher than what you'd pay on your own, and those forced-place premiums get added directly to your loan balance. I had a borrower who forgot to renew his policy and ended up paying $180 in forced-place insurance over four months. That was roughly equivalent to 18 percent annualized on top of the loan rate.
Get the Full Details

When a Bike In Loan Makes Sense and When It Doesn't
A bike loan is worth considering when you need a quality bicycle above $1,500 and paying cash would leave you financially exposed. Splitting the cost over 24 to 36 months preserves your emergency fund and keeps your cash flow stable. This is especially relevant for commuting bikes and adventure touring bicycles where a solid machine runs $2,000 to $4,000. It does not make sense when you can get a 0 percent promotional offer through a retailer's partner program. I've seen several major bike shops run 12-month no-interest deals on bikes over $1,000. If you qualify and pay it off within the promotional window, you're effectively getting an interest-free loan. The trap is missing the payoff deadline. A standard bike loan will retroactively charge interest from the purchase date if you don't clear the balance on time during a promotional period, and that retroactive interest can wipe out any savings you thought you were getting. Always confirm whether the promo is deferment of interest or true zero percent, and set a calendar reminder for two weeks before the promotional period ends. Another scenario where a bike loan is a bad fit is when your credit score is below 580. You'll get offered rates in the 15 to 22 percent range, which makes the total cost of the loan nearly double the sticker price of the bicycle. In those cases, saving up and buying a used bike or taking a slower path to build credit first is the financially rational choice.
Documents and Requirements You'll Actually Need
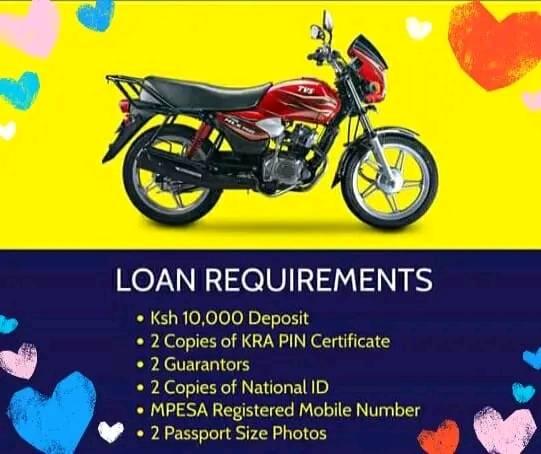
Most lenders ask for the same core documents: government-issued photo ID, recent pay stubs or tax returns covering the last 30 to 90 days, and a bank statement showing consistent income. A few lenders also request a debt-to-income ratio calculation, which means you'll need to list your existing monthly obligations like car payments, student loans, and credit card minimums. If your DTI is above 43 percent, approval becomes less likely and the rate will reflect the higher risk. One edge case that trips people up: if you're self-employed, lenders often want two years of tax returns rather than just recent invoices. I had a freelance graphic designer who made good monthly income but couldn't show two full years of self-employment tax returns because he'd switched from W-2 to freelance just 14 months earlier. He got declined by two lenders before a credit union approved him based on his W-2 history from the previous employer and a letter from his accountant confirming current earnings. If you're in that situation, go directly to a credit union rather than applying to multiple online lenders, since each hard inquiry will hurt your chances further.
Common Mistakes That Cost People Money
First, accepting the dealer's recommended insurance package without comparing it to your own policy. Many dealers bundle comprehensive bike insurance into the loan closure at marked-up rates. Call your own insurance provider first and ask if they'll cover a financed bicycle. You might save $30 to $60 per month. Second, skipping the check for a gap coverage clause. If your bike is stolen or totaled and you still owe money on the loan, standard collision or theft insurance should cover the remaining balance. But some policies have a gap exclusion that leaves you responsible for the difference between what the insurer pays and what you owe. Read the policy wording carefully before the loan closes. Third, not comparing at least three lenders before committing. Online lenders, credit unions, and dealer-financed programs can differ by 3 to 5 percentage points on the same loan amount for the same borrower profile. That gap translates to hundreds of dollars over the life of the loan. Spend 20 minutes running prequalification checks, which are soft pulls and don't affect your credit score, before making a final decision.
Bike In Loan Alternatives to Consider
If a traditional bike loan doesn't work for your situation, there are other paths. A retail installment contract through the dealer often has similar terms but can be more flexible with documentation. Some major bicycle manufacturers offer their own financing programs with competitive rates for qualified buyers. If you already have a credit card with a low APR or a balance transfer offer, putting the bike purchase on that and paying it down systematically can be cheaper than a dedicated loan, though you need to be disciplined about not adding new charges to the card. Crowdfunding or a friends-and-family loan at a modest interest rate can work for larger purchases if you have people willing to support your goal. It's not for everyone, but I've seen it used successfully for expedition-length touring setups that run $5,000 or more, where traditional lender terms were either unavailable or prohibitively expensive. The bottom line is that a Bike In Loan is a practical tool for the right buyer, but it requires the same due diligence as any secured credit product. Read the terms, compare offers, and understand exactly what happens if you miss a payment or need to pay off early. The lenders aren't trying to trap you, but they also aren't looking out for your best interest. That part is on you.