Figure Out What You Actually Pay Each Month for a Bike Loan
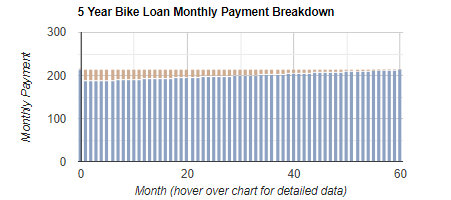
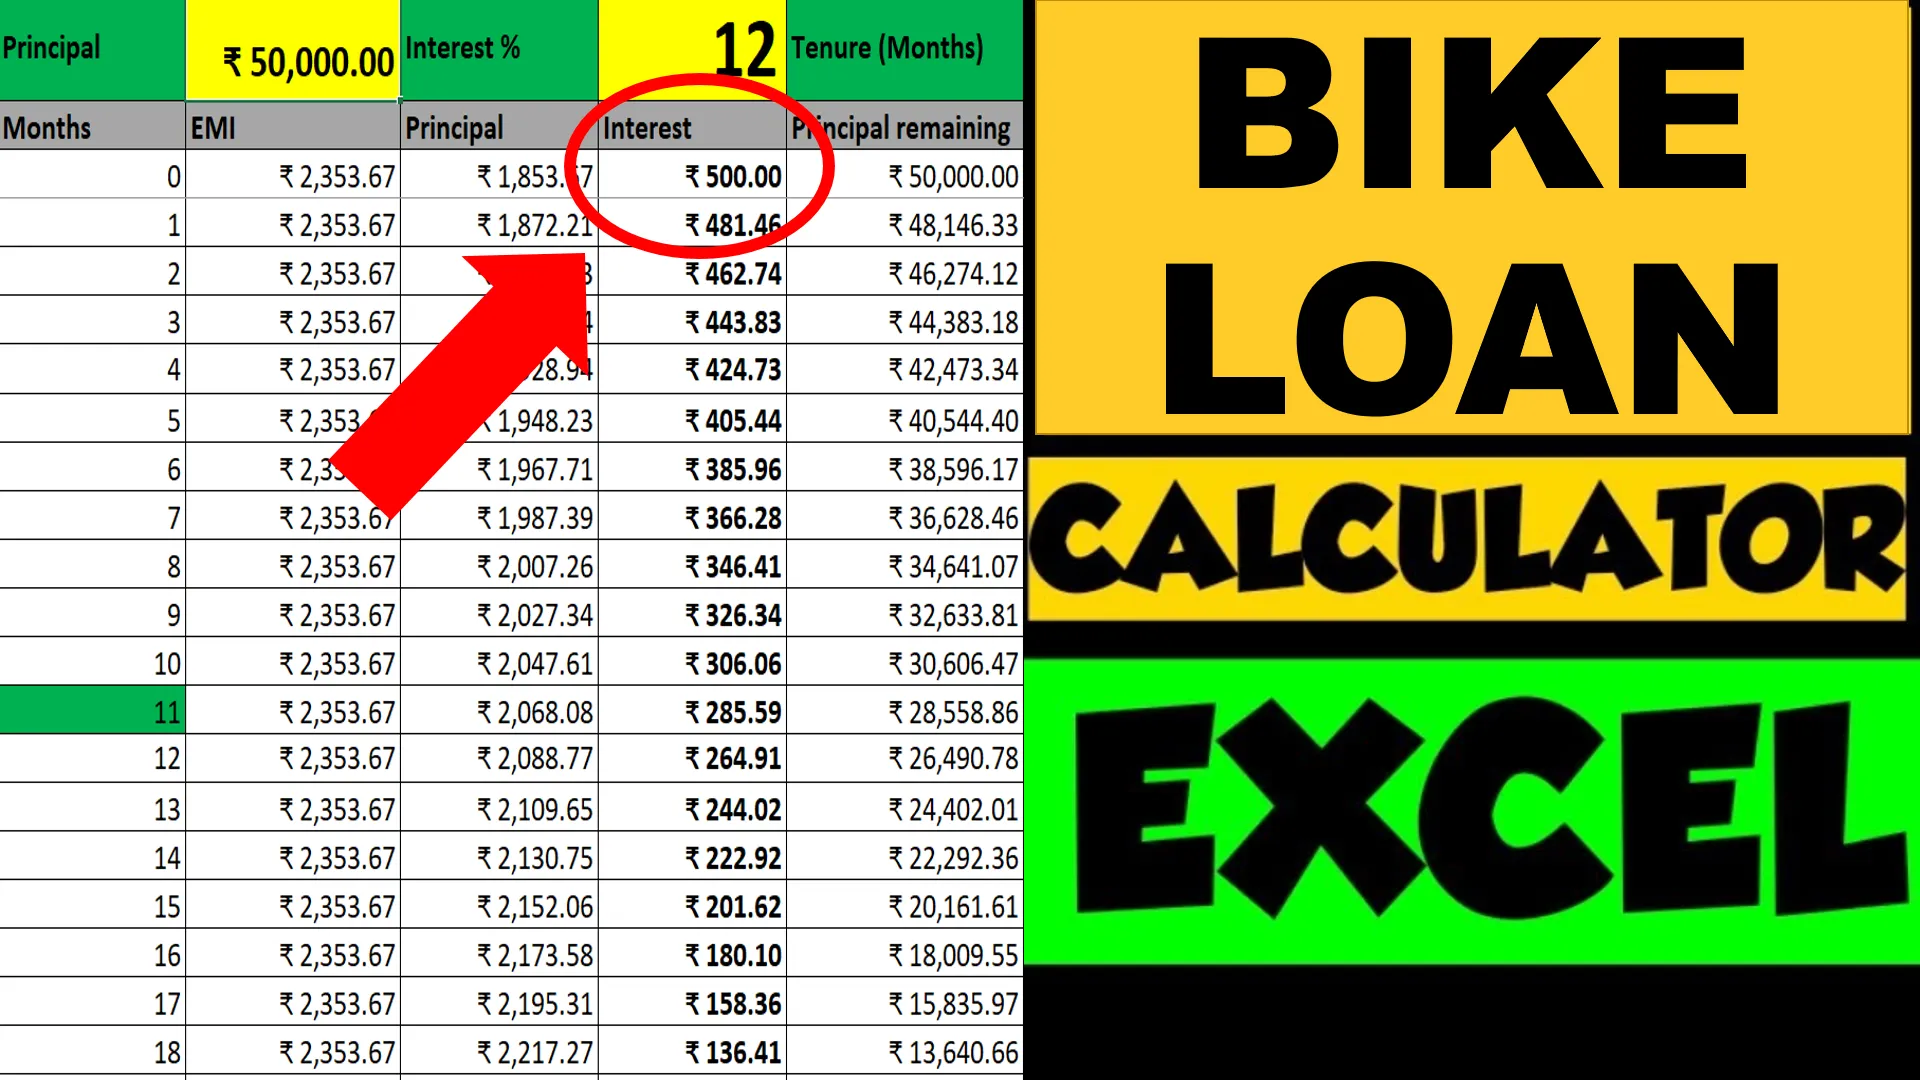
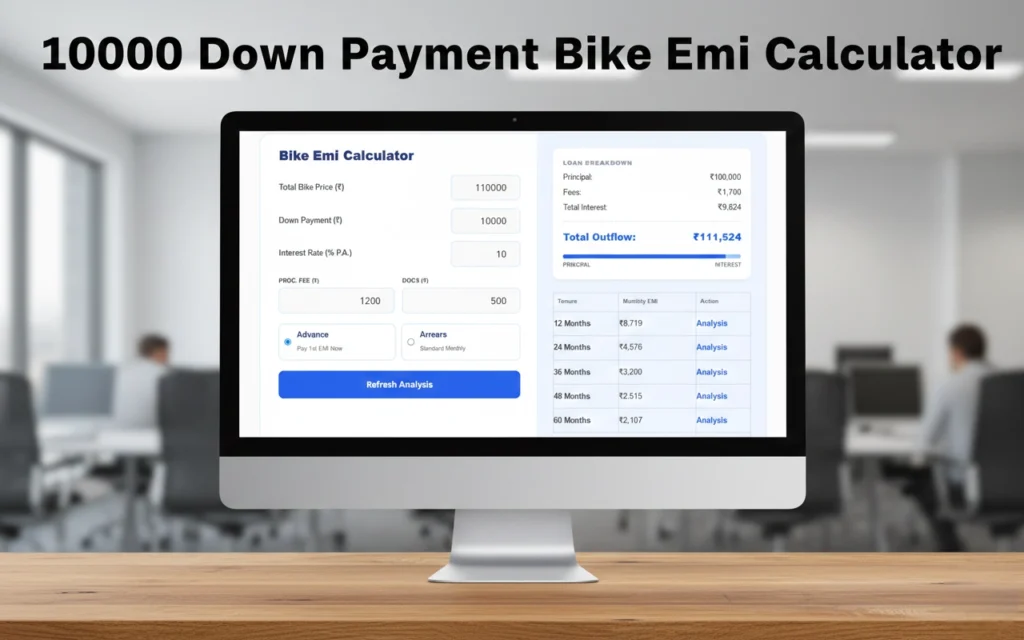
Most people buying a bike on finance sit down with a Spreadsheet and plug in numbers that don't quite match what the dealership quotes them. The gap usually comes from how interest compounds, whether fees are baked into the principal, and whether the lender uses a 360-day or 365-day year for daily accrual. I ran into this exact problem when helping someone compare offers from three lenders for a mid-range motorcycle. One quote looked cheaper on paper because the monthly payment was lower, but the lender was rolling a $400 processing fee into the loan balance AND charging pre-computed interest. That single detail added nearly $1,200 to the total cost over three years compared to the lender with the slightly higher stated rate but simple interest amortization.The core calculation itself is straightforward. Take your loan amount, divide by the number of payments, then add the periodic interest charge. But the periodic interest charge is where people get tripped up. The standard amortization formula is M = P × r(1+r)^n ÷ ((1+r)^n - 1), where P is the principal, r is your monthly interest rate (annual rate divided by 12), and n is the total number of monthly payments. This assumes a standard reducing-balance loan where each payment first covers that month's accrued interest, and the remainder chips away at the principal. Every payment after that shifts more toward principal and less toward interest, which is why the total interest paid over the life of the loan matters more than the rate alone. A Bike Payment Calculator takes the manual work out of comparing scenarios. You enter the bike price, your down payment, the loan term, and the annual interest rate, and it spits out the monthly figure plus the total interest you'll pay. The real value shows up when you start sliding the term length. A five-year loan on a $8,000 motorcycle at 7.5% annual interest gives a monthly payment around $160. Stretch it to six years and the payment drops to about $135, but you'll pay roughly $800 more in total interest. That tradeoff isn't obvious without running the numbers side by side. I found that the most useful thing a good calculator lets you do is compare multiple loans simultaneously. I kept one tab open with a dealer-financed option at 0% for 24 months but requiring full insurance, and another tab with a credit union loan at 5.9% for 48 months. The 0% deal looked better until I factored in that the required comprehensive coverage cost me about $35 a month extra, which erased the savings after month ten. Without a calculator running both scenarios in parallel, I would have taken the flashy 0% offer and regretted it later.
There are also edge cases that most generic calculators handle poorly. Some lenders use add-on interest instead of reducing-balance interest, which means the interest is calculated on the full original principal for the entire term regardless of how much you've already paid down. On a $5,000 loan at 10% for three years, add-on interest costs you $1,500 total, which translates to an effective annual rate closer to 18.5% even though the sticker says 10%. A proper Bike Payment Calculator should let you toggle between amortizing and add-on interest, but many free online versions don't. I ended up writing my own small script in Python that handled both methods so I could present side-by-side numbers to buyers without getting burned by the effective rate trick. The other common pitfall involves negative equity. If you trade in a bike that still has a loan balance higher than its current market value, the dealer rolls that shortfall into the new loan. Say you owe $3,200 on a bike worth $2,400 on the used market. That $800 gap gets added to your new loan amount, and you're now paying interest on money that wasn't even part of the new purchase price. I've seen this create loops where someone trades in once a year and ends up owing more than the current bike is worth on every single transaction. Running the trade-in shortfall through the calculator before signing anything usually reveals the trap early enough to walk away. If you're looking for something practical to work with, I built a simple calculator that handles both amortizing and add-on interest, factors in trade-in equity shortfalls, and shows the effective APR so you can compare loans on equal footing. It runs locally in your browser with no data sent anywhere, which matters because you're plugging in your actual income and debt figures. Download it and use it alongside whatever quotes the dealers give you. The numbers won't lie, and neither will the comparison.
What Most People Miss About Bike Financing
The monthly payment is almost never the right number to focus on. Total cost of ownership for the loan matters far more. A shorter term with a higher payment often saves thousands in interest compared to stretching it out for a lower monthly figure that looks comfortable on a tight budget. I tell buyers to calculate the total interest line first, then work backward to see if the payment fits their monthly cash flow. If it doesn't, either reduce the loan amount by increasing the down payment or extend the term only if the interest savings from a shorter rate beat the cost of the extra months. Prepayment penalties are another thing to check before signing. Some lenders charge a fee if you pay off the loan early or make extra payments toward the principal. This is relatively common with dealer-arranged financing, where the lender makes money on the interest spread and wants to protect it. If the penalty is structured as a percentage of remaining principal, paying off half the loan in month twelve could cost you a few hundred dollars in fees that wipe out the interest savings you were trying to capture. Look for loans with no prepayment penalty or a declining penalty schedule that drops to zero after a certain period. Insurance costs tied to the financed amount also shift with every trade-in. Lenders require gap insurance or comprehensive coverage that matches the outstanding loan balance, not the current market value of the bike. When you owe $6,000 on a bike worth $4,500, your insurance premium is based on covering that $6,000 gap. As you pay down the loan, the coverage requirement drops, but not always in sync with your actual equity. Check your policy annually to make sure you're not overpaying for coverage on a loan balance that no longer exists.
Get the Full Details

When a Calculator Won't Help
These tools assume the numbers you feed them are accurate. They can't account for variable-rate loans that adjust after an introductory period, hidden maintenance reserves that some dealers add to the loan, or promotional deals that require you to buy accessories or extended warranties to qualify for the advertised rate. If a dealer says "0% for 36 months" but requires a $1,200 accessory package you didn't ask for, the effective cost is higher than the calculator will show unless you factor that into the principal. Always read the contract before running the numbers through any tool. For very large loans or complex financing structures involving multiple trades or lease-to-own arrangements, the standard amortization formulas break down and you'd need a financial advisor or a more specialized tool. The calculator I put together works well for straightforward bike purchases between $2,000 and $25,000 with standard installment loans from credit unions, banks, or dealer financing. Beyond that range, the assumptions about rates and terms start to diverge from what lenders actually offer, and the output loses precision. The best approach is to use the calculator as a screening tool, not a final answer. Run the numbers, compare the results against the actual loan documents, and flag any discrepancies before you sign. Most of the money people lose on bike financing comes from not reading what they signed, not from bad math on the calculator side.