Understanding Books of Accounts: A Practical Guide
What Are Books of Accounts and Why Do They Matter?
Books of accounts are the formal records a business maintains to track every financial transaction. This includes purchase registers, sales ledgers, cash books, bank statements, and supporting vouchers. They are not optional paperwork. They are the backbone of any audit, tax filing, or internal review.
I once spent three days tracing a missing inventory discrepancy only to realize a supplier invoice was logged in the purchases register with the wrong date. The total was off by roughly twelve percent for that quarter. One wrong cell in an Excel register caused the whole thing to unravel. This is the kind of problem that shows up when books are not maintained consistently from day one.
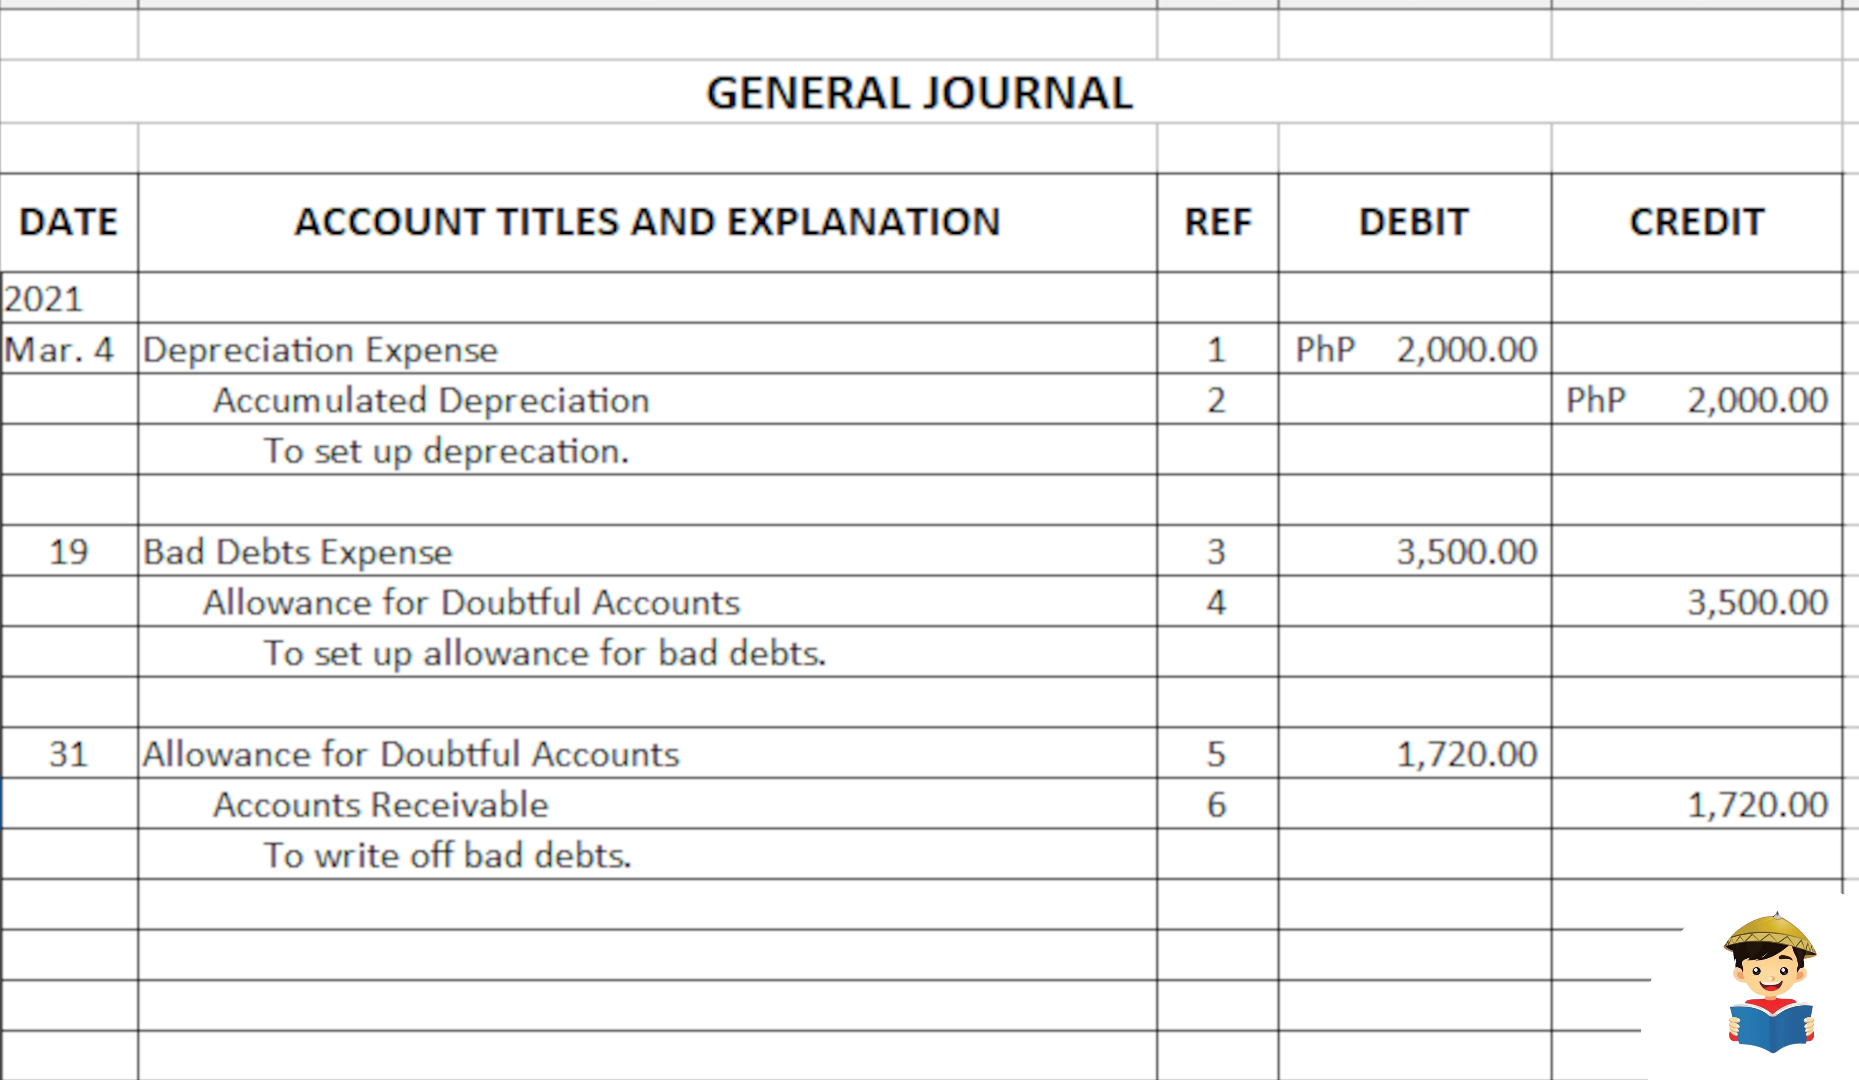
A solid Books of Accounts Sample gives you a starting structure. It defines how transactions flow, how entries are organized, and what supporting documents must accompany each record. You can adapt it to your business size and industry. But the structure should follow recognized accounting standards. In many jurisdictions, this means aligning with the applicable financial reporting framework, such as Ind AS, full GAAP, or a simplified basis for small businesses.
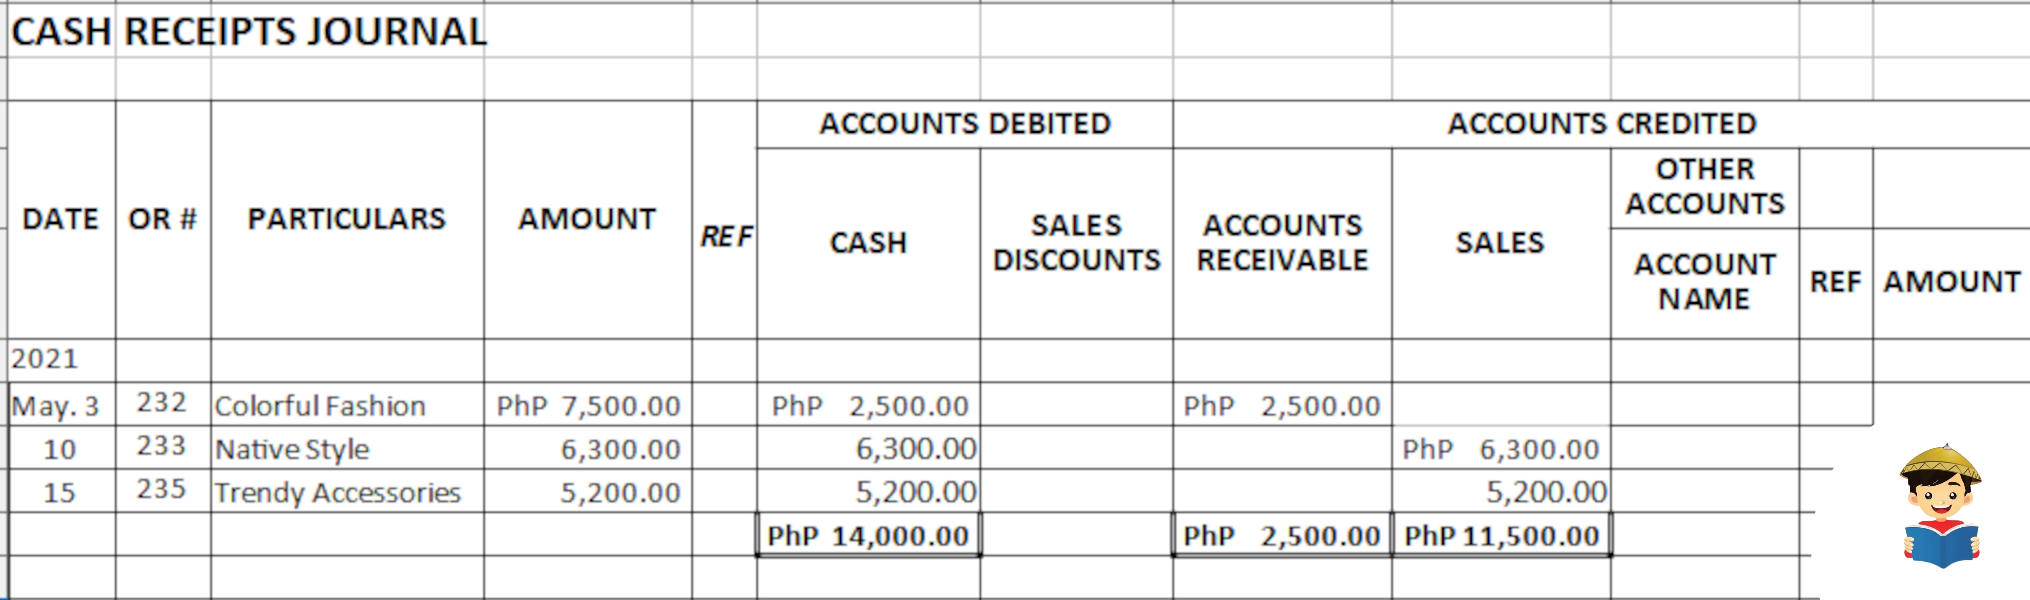
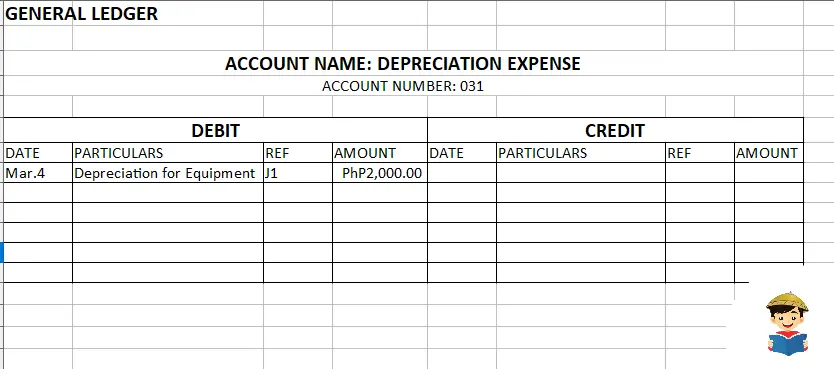
Bir Books Of Accounts Sample frameworks typically include a general ledger, subsidiary ledgers, a cash book, a bank reconciliation register, and supporting voucher logs. Each one serves a specific purpose. The general ledger aggregates all accounts. Subsidiary ledgers handle detailed transactions like accounts receivable or payable. The cash book records daily receipts and payments. Bank reconciliations catch timing differences and errors between your records and the bank statement.
Core Components of a Functional Book of Accounts
A working set of books covers both recording and verification. Here are the essential pieces.
-
Chart of Accounts: A coded list of every account you use. Revenue, expenses, assets, liabilities, and equity. This is where most beginners make mistakes. Account codes should be logical and consistent. I have seen businesses use generic names like "Miscellaneous Expense" for dozens of lines, then struggle to find anything during an audit.
-
Daily Transaction Log: Every invoice, receipt, and payment recorded on the day it occurs. Delays create reconciliation problems later.
-
Purchase Register: All purchases with vendor details, dates, amounts, tax, and document references.
-
Sales Register: All sales with customer details, dates, amounts, tax, and document references.
-
Cash Book: Records of all cash inflows and outflows.
-
Bank Book: Records of all bank transactions.
-
Journal Entries: Non-routine or adjusting entries that do not fit into standard registers.
-
Supporting Vouchers: Physical or digital copies of invoices, receipts, and approvals. These are what auditors check first.
How to Set Up Your Books: A Step-by-Step Approach
Start with the chart of accounts. Build it around your actual business activities. Do not copy a template blindly. If you run a service business, you do not need a raw materials inventory account. If you handle goods, you need stock records.
Next, choose your recording method. Manual books work for very small operations, but they are slow and error-prone. Most businesses benefit from accounting software. I recommend starting with a cloud-based solution that supports multi-user access and audit trails. This cuts monthly closing time significantly compared to manual spreadsheets. In my experience, moving from a basic Excel register to proper software usually reduces the time spent on monthly reconciliation from several hours down to about thirty minutes.
Then establish a routine. Daily entries for cash and bank transactions. Weekly entries for invoices. Monthly reconciliation of all accounts. Quarterly review of ledger balances. Annual close with audit adjustments.
Here is a concrete example. A medium-sized trading company in India maintained a manual register for purchases and a separate Excel sheet for sales. When they compiled accounts for assessment, the two files did not match. The difference was around eighty-five thousand rupees for that year. The fix involved rebuilding the entire register set in Tally with proper voucher linking. The transition took about a week, but it eliminated the discrepancy permanently.
Common Mistakes and How to Avoid Them
The most frequent issue is inconsistent recording. Some transactions go into one system, others into another. This creates duplication or omission. Use a single source of truth. Every entry should be recorded once in one place.
Another common problem is poor voucher management. Auditors require proof for every entry. If you cannot produce the invoice or receipt, the entry may be disallowed. Keep digital scans and physical copies organized by date and reference number.
Tax compliance is the third major trap. GST, TDS, and other taxes require specific treatment in your books. Miscalculating tax amounts or misfiling entries leads to penalties. Verify tax rates and sections before finalizing each entry.
I learned about the third issue the hard way. A client had been recording TDS deductions in the expense register but not maintaining a separate TDS liability account. When the annual return was filed, the numbers were off by a significant margin. The correction required backdating entries across twelve months of data. It took roughly two weeks of work. A dedicated TDS ledger from the start would have prevented this entirely.
When Standard Templates Fall Short
Not every business fits a one-size-fits-all template. Manufacturing concerns need production cost sheets. Service firms need project-wise tracking. E-commerce businesses need platform-wise reconciliation. A generic sample provides structure, but you must adapt it to your specific operations.
If your business involves multiple entities, inter-company transactions, or foreign currency, the books become more complex. In those cases, consider using a tool that supports consolidation and multi-currency handling. Manual spreadsheets struggle with this beyond a basic level.
Key Takeaways
Books of accounts are fundamental to business compliance and clarity. Start with a clear chart of accounts. Record transactions consistently and daily. Maintain supporting vouchers. Use appropriate software rather than relying solely on spreadsheets. Reconcile monthly. Review quarterly. The structure you build now saves significant time and stress later.
A
Bir Books Of Accounts Sample gives you a framework to begin with. Adapt it carefully. Test it with a few months of real data. Adjust as needed. The goal is accuracy, completeness, and audit readiness at all times.