What actually happens when you switch from monthly to biweekly mortgage payments
Most people think biweekly payments just mean paying half your monthly amount every two weeks. It seems straightforward on paper. The math is simple enough that even a basic spreadsheet can handle it. But the reality of how these payments interact with your loan terms, interest calculations, and servicing systems is a lot messier than the brochures suggest. I spent about four years working loan servicing operations before moving to the advisory side. We saw hundreds of borrowers try to switch to biweekly schedules, and roughly half of them ran into issues they didn't expect. The main problem isn't the concept itself. It's the gap between how the theory works and how actual mortgage servicers implement it.
How a Biweekly Amortization Calculator actually works
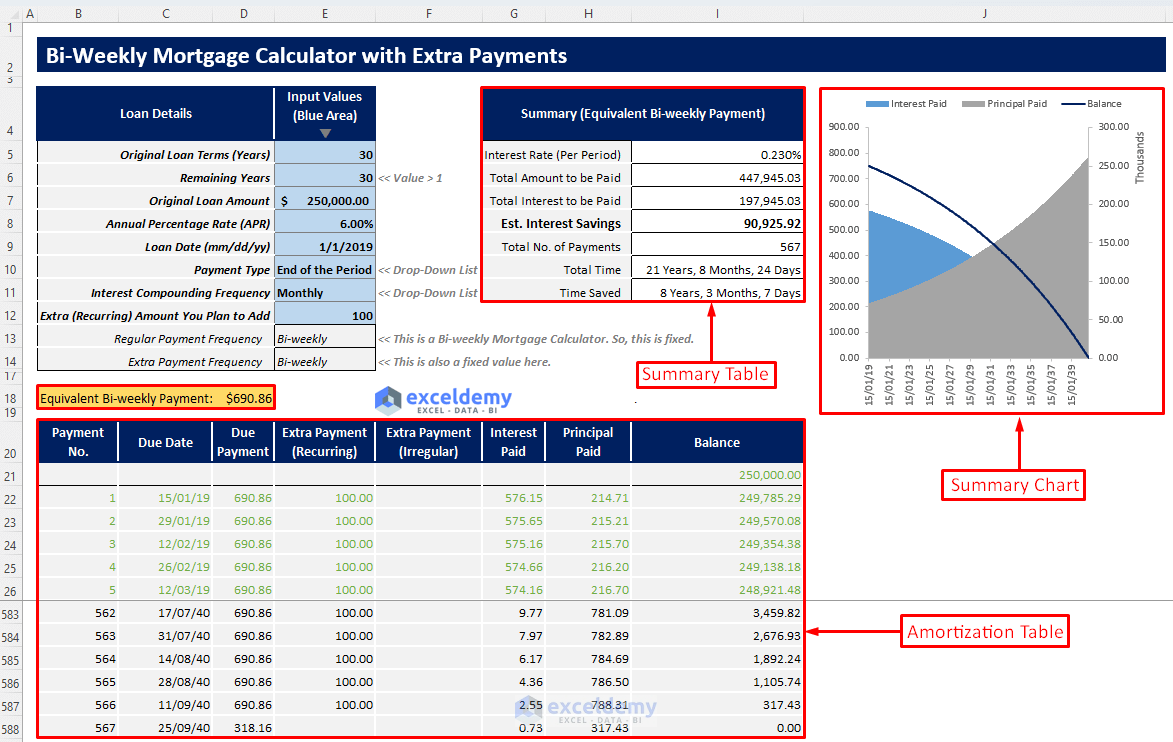
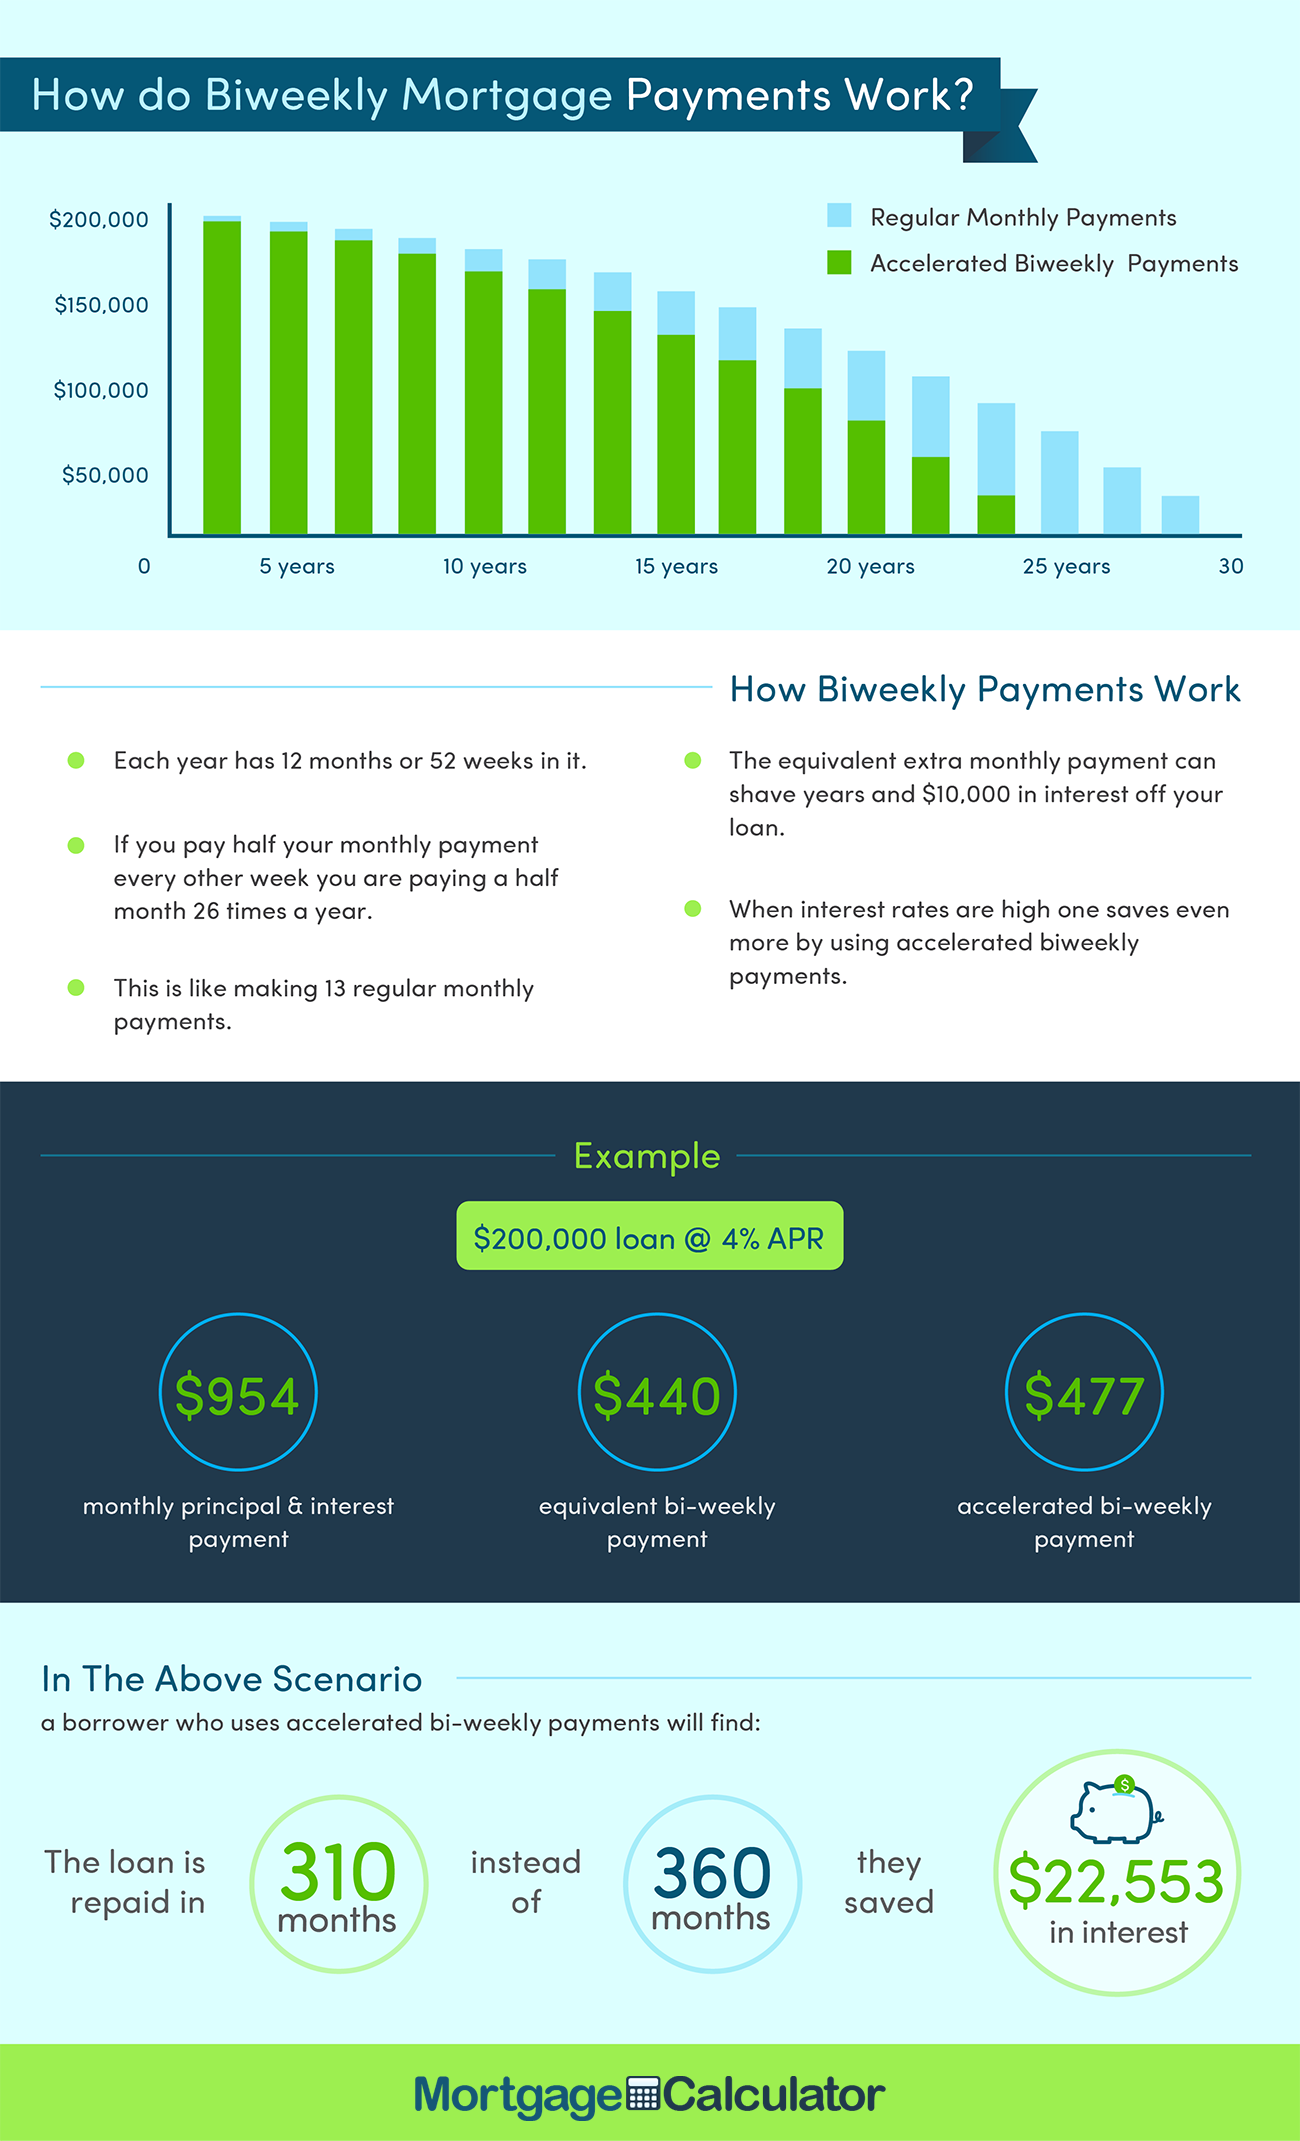
A biweekly amortization calculator takes your loan details — principal balance, annual interest rate, and remaining term — and then divides your standard monthly payment in half. Instead of sending one large payment every thirty days, you send a smaller one every fourteen. The key difference is that over a full year, you end up making twenty-six half-payments instead of twelve full payments. That's equivalent to thirteen monthly payments. One extra payment per year goes straight toward reducing your principal balance. Here's where the practical calculation gets interesting. Most mortgages calculate interest using a daily balance method. Your interest accrues daily based on your outstanding principal. When you pay monthly, that balance sits untouched for thirty days before you reduce it. With biweekly payments, you're chopping down the principal roughly every two weeks instead of every month. Over the life of a thirty-year loan at 6.5 percent, switching to biweekly can save anywhere from eight to fifteen thousand dollars in total interest and shave about four to seven years off your payoff timeline. The exact numbers depend on your starting rate, your balance, and whether your servicer actually applies the extra payment correctly. Let me walk through a quick example. Say you have a $300,000 mortgage at 6.5 percent with thirty years remaining. Your monthly payment comes to roughly $1,896. If you switch to a true biweekly schedule, you're paying about $948 every two weeks. Twenty-six payments of $948 equals $24,648 per year, which is the same as thirteen monthly payments instead of twelve. On a standard amortization schedule, this single change reduces your total interest paid by approximately twelve thousand dollars and shortens your loan term by about five years. The math checks out cleanly in any spreadsheet. The execution is where things get complicated.
The formula the calculator uses is basically this: take your annual interest rate, divide it by 365 to get your daily periodic rate, multiply that by your current principal balance to find the daily accrued interest, and then subtract each biweekly payment from the balance after applying that day's interest. You repeat this process for each payment date. The compound effect of reducing the principal more frequently means less interest accrues between payment dates. Over time, that compounds into significant savings. Any decent Biweekly Amortization Calculator will show you the full projected schedule, including how much principal you'll save and when you'll own the home outright. I built my own version of this calculator early on because the commercial tools I was using kept giving inconsistent results. The issue was that most online calculators assumed a 360-day year for their interest computations, which is standard in commercial lending but doesn't match how residential mortgages are actually serviced in the United States. Residential loans use a 365-day actual year. Getting that wrong throws off your projected savings by several hundred dollars over the life of the loan. Once I switched to exact daily accrual calculations, the numbers aligned with what our servicing system was actually showing borrowers.
Get the Full Details

The problems nobody warns you about
The biggest issue I ran into repeatedly was that not all mortgage servicers handle biweekly payments the way the calculations assume. Some servicers will accept your biweekly payment, but they'll process it as if it's just a partial monthly payment. They don't apply it to the principal the way a true biweekly schedule would. Instead, they hold it until your regular monthly due date arrives and then combine it with your next scheduled payment. In those cases, you're not actually accelerating anything. You're just splitting your payment into awkward halves that create accounting headaches for everyone involved. I dealt with this on a specific file back in 2018. A borrower came to us after trying a third-party biweekly program for two years and accumulating thousands in fees without seeing any reduction in her payoff date. When I pulled her statements, the servicer had been treating every biweekly deposit as a prepayment credit rather than applying it against the principal balance immediately. The fix was straightforward once I identified it. I had the borrower switch to making an additional full monthly payment each year manually. Instead of splitting her payment into twenty-six chunks, she kept her normal twelve monthly payments on schedule and sent one extra payment directly toward principal every December. The result was identical to what a proper biweekly schedule would have produced, but without the fee structure or the servicer confusion. It took me about twenty minutes to explain the workaround and set up the payment calendar. The borrower saved herself another two years of unnecessary service charges. Another edge case that comes up constantly involves adjustable-rate mortgages and loans with prepayment penalties. If your mortgage has a prepayment penalty clause — common on jumbo loans and some refinance deals — your servicer might charge you a fee every time you pay down principal faster than the scheduled amount. A biweekly schedule triggers that penalty on nearly every payment. I've seen borrowers lose more in prepayment penalties than they saved in interest. The calculator output will never show you that cost because it has no way of knowing your loan agreement's specific terms. You have to read your own note and disclosure documents to find out.
There's also the timing problem. Fourteen days is not exactly half of thirty days. Over a twelve-month period, the mismatch between a biweekly calendar and the Gregorian calendar means your payment dates drift. Some months you'll make two payments, some months three. If your servicer isn't set up to handle variable payment frequencies, you'll get error messages, late notices, or payments that get misapplied. I've watched entire biweekly programs fail because a servicer's automated system couldn't reconcile the irregular payment schedule. The borrower ended up with three payments in a single billing cycle, got flagged as overpaying, and the system reversed one payment back to their escrow account. It took six weeks and three phone calls to sort out.
When biweekly payments make sense and when they don't
The strategy works best for borrowers who have a stable income stream, typically salaried employees who get paid biweekly themselves. The alignment between your cash flow and your payment schedule eliminates the friction of remembering to make an extra payment each year. If you're already structured to receive money every two weeks, automating a biweekly mortgage payment feels natural. You're essentially just redirecting half of each paycheck instead of waiting to accumulate a full month's payment in one lump sum. It works less well for self-employed borrowers, commission-based workers, or anyone whose income varies significantly from month to month. The rigid fourteen-day cycle doesn't accommodate irregular cash flow. You might be fine one cycle and then scrape together the payment the next. For these situations, setting up a separate automatic transfer to an escrow-style account each month and then making one additional principal payment annually achieves the same result without the scheduling rigidity. There's also a behavioral component worth considering. Some people find comfort in the frequent small payments because it creates a psychological sense of progress. Others find the constant recurring charge stressful or confusing when their statements don't match the expected pattern. I once had a client who stopped his biweekly payments after eight months because he kept getting confused by his own bank statements. The extra transactions made his account look like it was overdrawn even when it wasn't. He switched back to monthly payments with an automatic extra annual principal payment instead. Simpler, fewer moving parts, same financial outcome.

Practical steps if you want to try this
Start by pulling your loan documents. Look for the prepayment penalty clause and the interest calculation method. Is your loan serviced on a 30/360 basis or actual/365? This detail matters for accuracy. Next, run your numbers through a Biweekly Amortization Calculator that uses daily interest accrual, not the simplified version most free online tools provide. Compare the projected savings against any fees the biweekly program charges. Some programs charge upfront enrollment fees of five hundred to two thousand dollars plus monthly service fees of ten to twenty-five dollars. Those costs eat into your savings significantly, especially in the first few years. If your servicer supports biweekly payments natively, ask them in writing how they process the payments. Get confirmation that each biweekly payment reduces your principal immediately and doesn't sit in a holding account until your regular due date. I always recommend getting this in writing because verbal assurances from customer service representatives don't hold up when the system actually processes the payments. One borrower I worked with got a detailed email confirmation from her servicer saying biweekly payments would be applied to principal within one business day. Three months later, her statements showed the payments were being held for forty-five days. The written promise meant nothing against the actual system behavior. For most people, the simplest and most reliable approach is to keep your monthly payment schedule exactly as it is and set up an automatic additional principal payment once per year. Choose a date when you know you'll have the funds — maybe when you receive a tax refund or a bonus. This method avoids all the servicer compatibility issues, eliminates the risk of prepayment penalty triggers on individual payments, and produces the same principal reduction and interest savings as a properly executed biweekly schedule. The extra payment is a single transaction instead of twenty-six, which means one thing to track and one thing to potentially mess up.
The fundamental trade-off here is convenience versus control. True biweekly payments through a servicer or program remove the mental burden of remembering to make an extra payment each year. But they introduce dependency on external systems that often fail to handle the schedule correctly. The manual extra-payment method gives you direct control over every transaction and eliminates the risk of your servicer mishandling the payments. The downside is that you have to remember to make that thirteenth payment each year. Missing it is easy if you're not organized about it. I tend to recommend the manual approach because the outcomes are predictable and you control the timing. The savings are the same either way. The only real difference is whether you're trusting a third-party system to do what the math says should happen.