How Biweekly Payments Actually Change Your Loan
Most people think making biweekly payments is just a neat trick to pay off their car loan faster. It's not really a trick. It's math. You split your monthly payment in half and pay every two weeks instead of once a month. That works out to 26 half-payments a year, which is the same as 13 full payments. One extra payment, every single year, whether you notice it or not. The reason this matters is because interest on car loans compounds daily. When you pay more often, the principal drops faster, and you stop paying interest on money you already owed. Over a typical five-year auto loan, that extra payment can shave anywhere from six months to a full year off the term, depending on your rate and how much you're borrowing. On a $25,000 loan at 6.5% over 60 months, you'd save roughly $1,200 to $1,500 in total interest and finish the loan around month 52 instead of month 60. Not nothing.
Using a Biweekly Car Loan Calculator
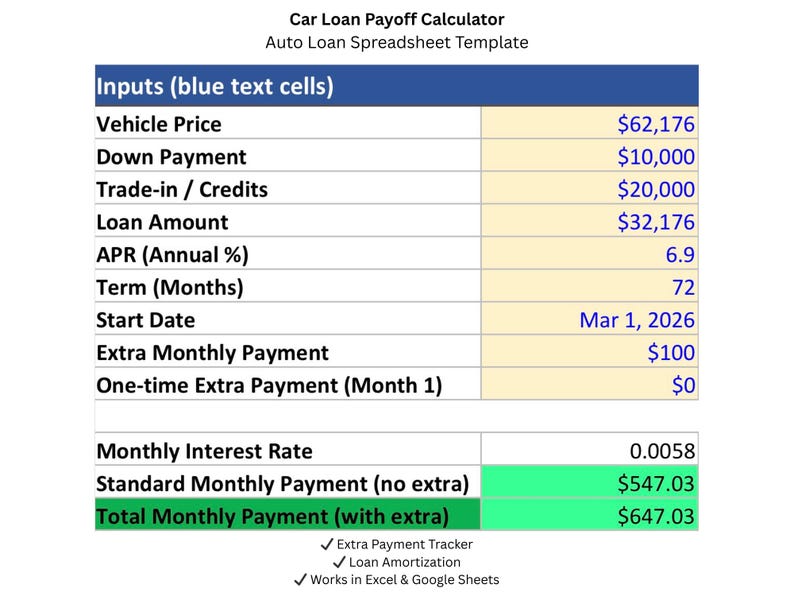
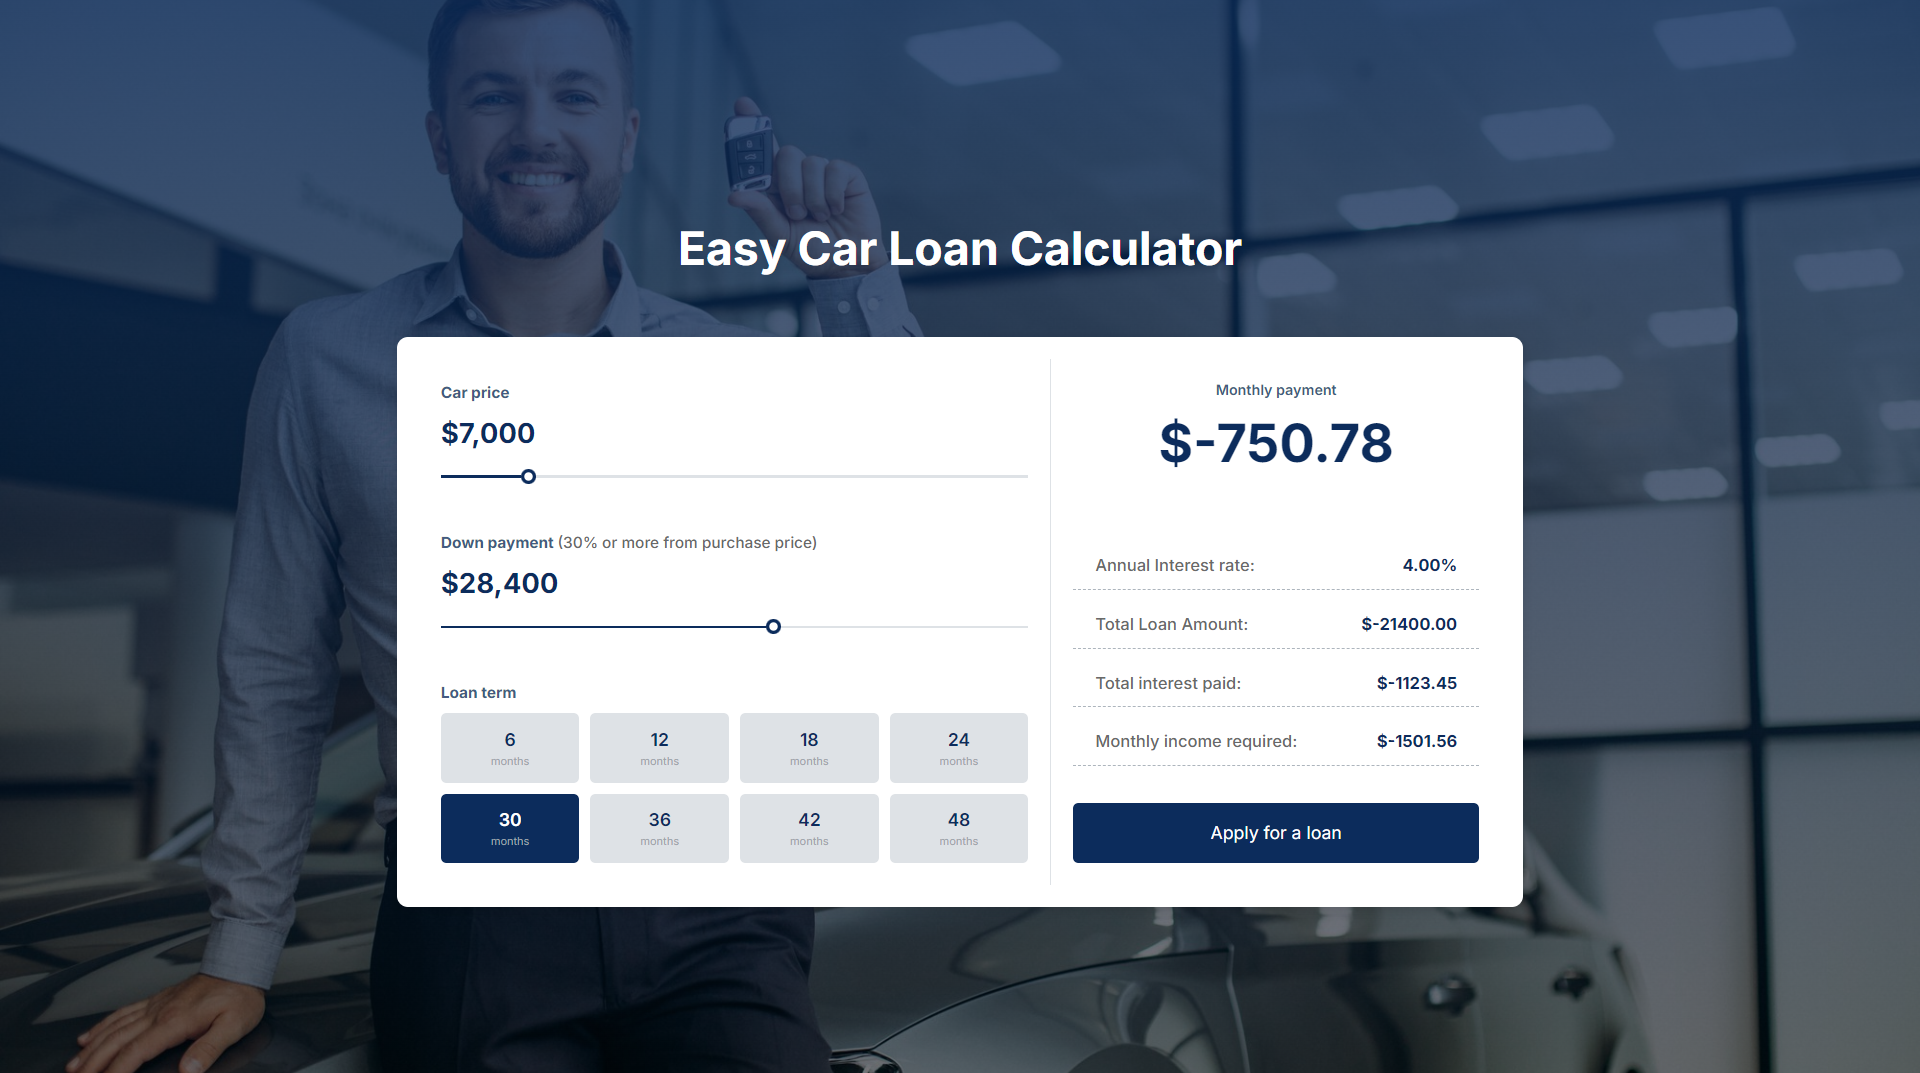
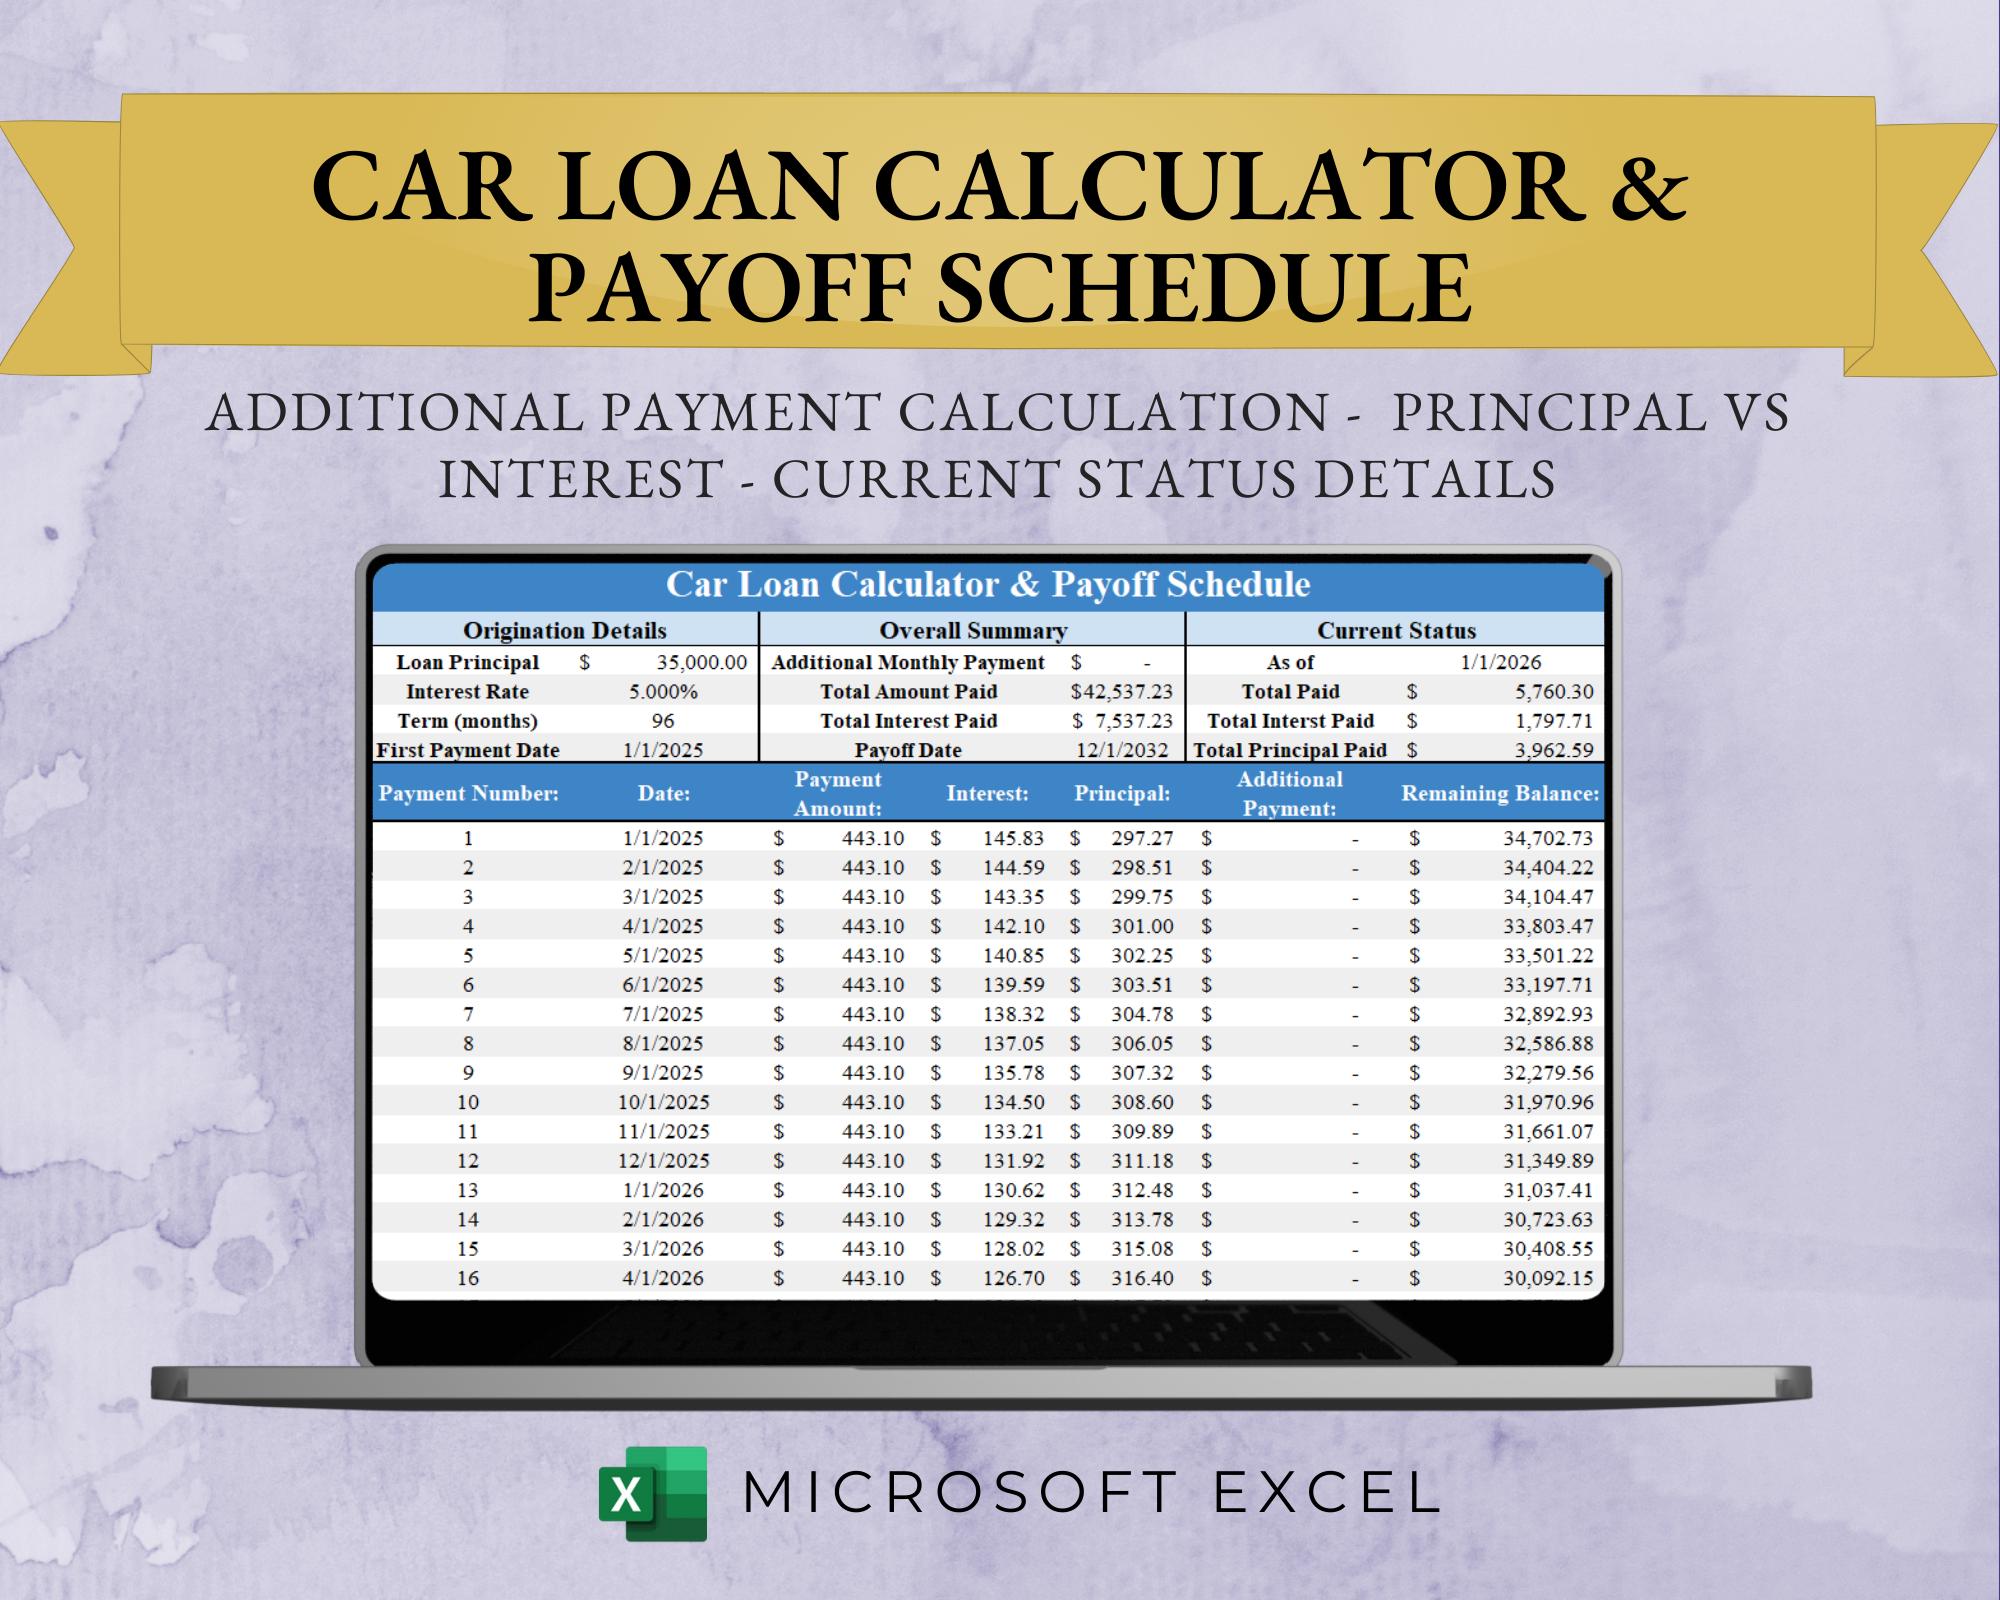
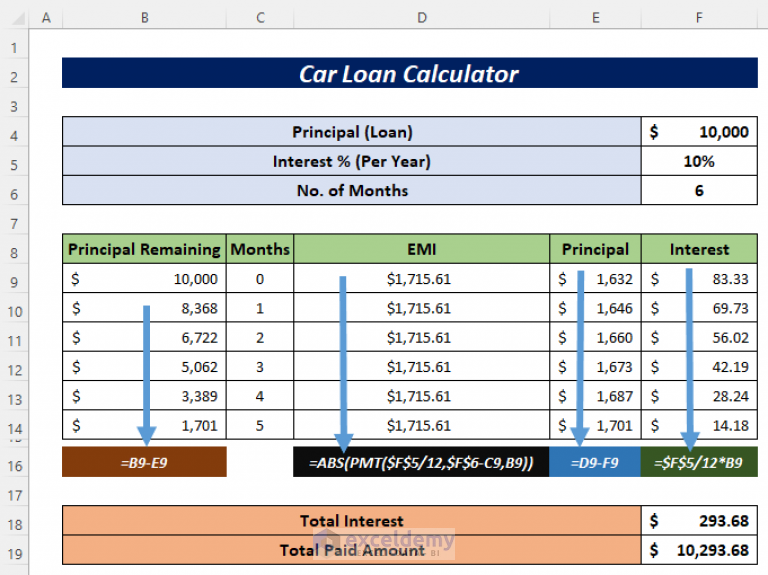
A Biweekly Car Loan Calculator does exactly what you'd do by hand, only without the spreadsheet headaches. You plug in the loan amount, the interest rate, and the original term. The tool breaks your monthly payment in half and rebuilds the amortization schedule on a biweekly basis. It shows you the new payoff date and the interest savings. Some also let you compare scenarios side by side so you can see what happens if you round up or make a voluntary extra payment occasionally. I keep one open in my browser whenever someone brings up this topic at work. The free tools on financial sites are decent for quick estimates. I usually use one, then cross-check with a quick Excel build to catch rounding differences. The built-in calculators on lender portals tend to be more accurate because they pull from the actual loan servicing system. That's the version I trust for real decisions.
Why the Math Works the Way It Does
Auto loan interest is calculated using a daily periodic rate. You take the annual percentage rate and divide it by 365. Each day the lender multiplies that rate by your outstanding balance to figure out how much interest accrued. When you make a payment, it first covers the accrued interest, then the rest goes to principal. Pay more often and your principal gets whacked sooner. Less principal means less interest every day after that. Here's the part most people miss. Biweekly payments don't automatically get you thirteen payments. If your lender structures things, they might still only process payments on certain dates. I ran into this last year with a fleet vehicle loan. The borrower was convinced the biweekly schedule meant his payments would land every two weeks on the same weekday. Instead, the servicer's system aligned everything to calendar months and the payment dates drifted. He ended up making fourteen payments in year one anyway, which he hadn't planned for. Cash flow caught him off guard. The workaround was to switch to a straight biweekly autopay through the lender, where the schedule was locked in and the system actually honored it. It took about ten minutes to set up and solved the drift problem entirely.
Get the Full Details
Common Pitfalls and What They Cost You
The biggest mistake I see is assuming every lender supports true biweekly processing. Some will take the payment, but they apply it monthly. That means your accelerated payoff disappears and you're left with a confusing statement. A few lenders call this an accelerated biweekly plan. They'll collect the biweekly amount but only apply it to principal at the end of the month. You still get the benefit of having less cash available, but the interest calculation doesn't reflect the true daily reduction. It's a subtle difference, and it matters if you're comparing offers. Another issue is prepayment penalties. They're rare on auto loans now, but they still exist, especially with subprime lenders and some credit unions. Before you switch to a biweekly schedule, check your loan documents for a clause about partial or early payments. I found one in a used car loan from a regional lender where any payment under a certain threshold triggered a $25 administrative fee. Over a year, that erased most of the interest savings. The fix was simple: I grouped the biweekly payments into two larger monthly amounts and sent those instead. The payoff timeline shifted slightly, but the math stayed favorable and the fees disappeared.
When This Strategy Fails Completely
Biweekly payments aren't a magic bullet. If your loan has a balloon payment at the end, the schedule gets messy. The calculator might show you a clean payoff date, but the balloon sits there waiting. If your rate is below 4%, the savings from biweekly payments are marginal. On a $15,000 loan at 3.5% over 48 months, you'd save maybe $180 in interest. That's not dramatic. Sometimes it's better to just invest the difference and let compound growth work for you. There's also the edge case where your payment is already tight. Biweekly requires you to come up with half your monthly payment every two weeks. That's roughly 2,150 times a year. If you're living paycheck to paycheck, the rhythm can stress your cash flow even if the total annual cost is the same. I'd recommend running the numbers through a Biweekly Car Loan Calculator first and checking whether the half-payment amount fits your actual deposit schedule. If your pay comes monthly and your rent is due on the first, shifting to every two weeks will bounce around your budget like a pinball.
Practical Steps to Set It Up
Start with your current loan terms. Get the principal balance, the annual rate, the monthly payment, and the remaining term. Run it through a calculator and note the projected savings. Then call your lender and ask three questions: Do you support biweekly payment schedules natively? How do you apply partial payments? Are there any fees for accelerated payoff plans? Write down the answers. If they say yes to native support and no to fees, set up the autopay. If they drag their feet, ask to speak with the servicing department. The front line reps often don't know the answer and will transfer you anyway. Once the schedule is active, monitor the first two cycles. Check that the payment dates are actually every fourteen days and that the principal reduction is visible on your statements. If the statements look normal, you're set. If they don't, document everything and switch strategies. There are plenty of other ways to accelerate payoff, like making one extra payment per year on your birthday or setting up a round-up automation. Those approaches sidestep the scheduling problem entirely.
A Note on Accuracy
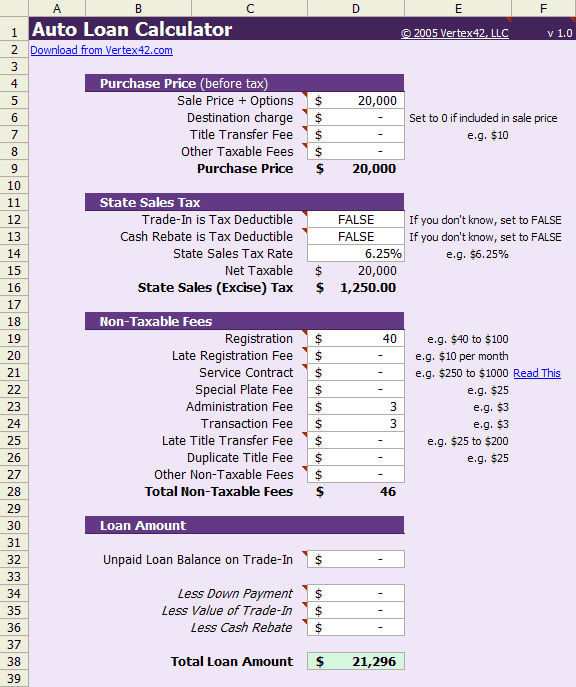
Calculator results are estimates. They assume you never miss a payment and the rate stays fixed. Real loans have things like late fees, payment holidays, and occasional rate adjustments on adjustable products. If your loan is fixed and you make every payment on time, the calculator output will be close. If your loan has any variability, treat the numbers as directional rather than precise. I usually build a small buffer of two or three months into my expectations. That keeps me from planning around a number that might shift if something goes wrong.