Why people switch to biweekly payments
Most lenders will happily keep you on a monthly schedule. That is their preference, not your obligation. The concept is simple enough that you do not need a fancy tool to grasp it. Take your regular monthly payment, divide by 26, and pay half every two weeks. You end up making 26 half-payments a year, which equals 13 full payments instead of 12. One extra payment goes toward principal every year without you really noticing it.
The payoff is predictable. On a 30-year loan at 6.5%, switching to biweekly can shave roughly 4 to 5 years off the term and save somewhere between 20,000 and 28,000 in interest over the life of the loan, depending on your balance. The math does not lie. What often surprises people is how aggressive the amortization curve becomes in the first few years when you start paying down principal faster.
The mechanics behind the numbers
A standard mortgage amortization schedule assumes 12 equal payments. Each payment covers interest accrued that month plus a small chunk of principal. Early in the loan, the interest portion dominates. When you introduce biweekly payments, you reduce the principal faster, which reduces the interest calculated on the next cycle, which frees up more of each payment to eat into principal. The snowball is real but it is not magical. It is just compound math happening on a tighter timeline.
Biweekly Mortgage Payment Calculator
The calculator itself is the part people get wrong. A basic one will take your current balance, rate, and remaining term, then show you the new payment amount and the projected payoff date. Some will also generate a side-by-side comparison table. What most cheap calculators omit is how your servicer actually applies the payment. That omission matters a lot.
I spent years working with loan servicing platforms before moving to the advisory side, and I have seen this exact mistake repeatedly. People run a generic biweekly calculation, get a number, send it to their servicer, and assume the schedule updates automatically. It almost never does. Servicers are optimized for monthly workflows. They do not always treat a 26-payment schedule as anything other than two partial monthly payments. If you do not force the structure through your own records, the servicer may simply lump your payments together and apply them monthly, erasing the benefit entirely.
The workaround I used was to set up automatic biweekly withdrawals through my bank to a separate account I controlled, then manually submit the payment on the exact due date with a memo line that said "Biweekly payment per borrower request." I kept a spreadsheet with the actual payment dates, applied amounts, and residual principal after every cycle. When the statement came back and the servicer had rolled two biweekly payments into one monthly bucket, I flagged it immediately. Within six months most servicers adjust their internal schedules if you push hard enough early on. After that they tend to just follow along.
What a proper calculation requires
You need five inputs. Current principal balance. Interest rate. Remaining term in months. The date of your next scheduled payment. And the payment frequency you want, which in this case is every two weeks. From there you compute the biweekly amount by taking the standard monthly payment and dividing by two. Then you project the new amortization by running a schedule that applies each half-payment to the accrued interest for that period and drops the remainder to principal.
Here is a concrete example. Say you owe $320,000 at 6.75% with 28 years remaining. Your monthly payment comes to about $2,078. Divide by two and your biweekly payment is $1,039. Under the new schedule you make a payment every 14 days. After year one you will have made 26 payments totaling $27,014 instead of the $24,936 you would have paid monthly. The extra $2,078 goes straight to principal in year one, not spread out over a year as regular monthly payments do. That front-loaded principal reduction is what compresses the term.
A
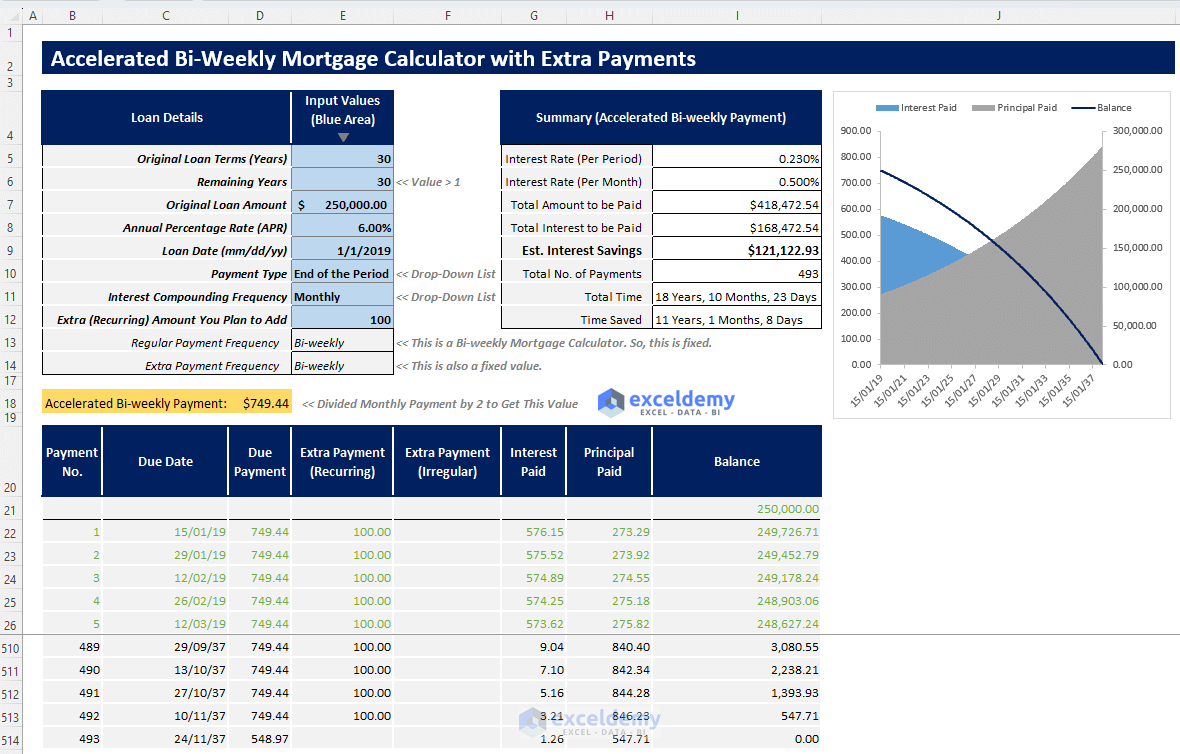
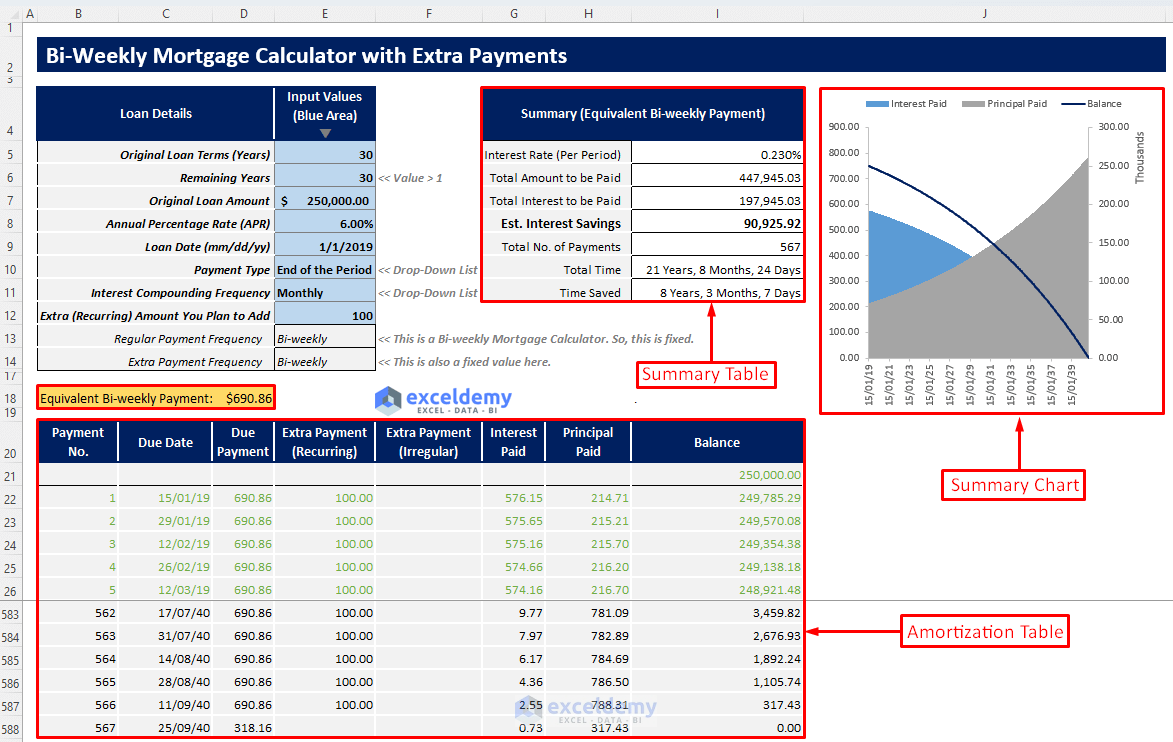
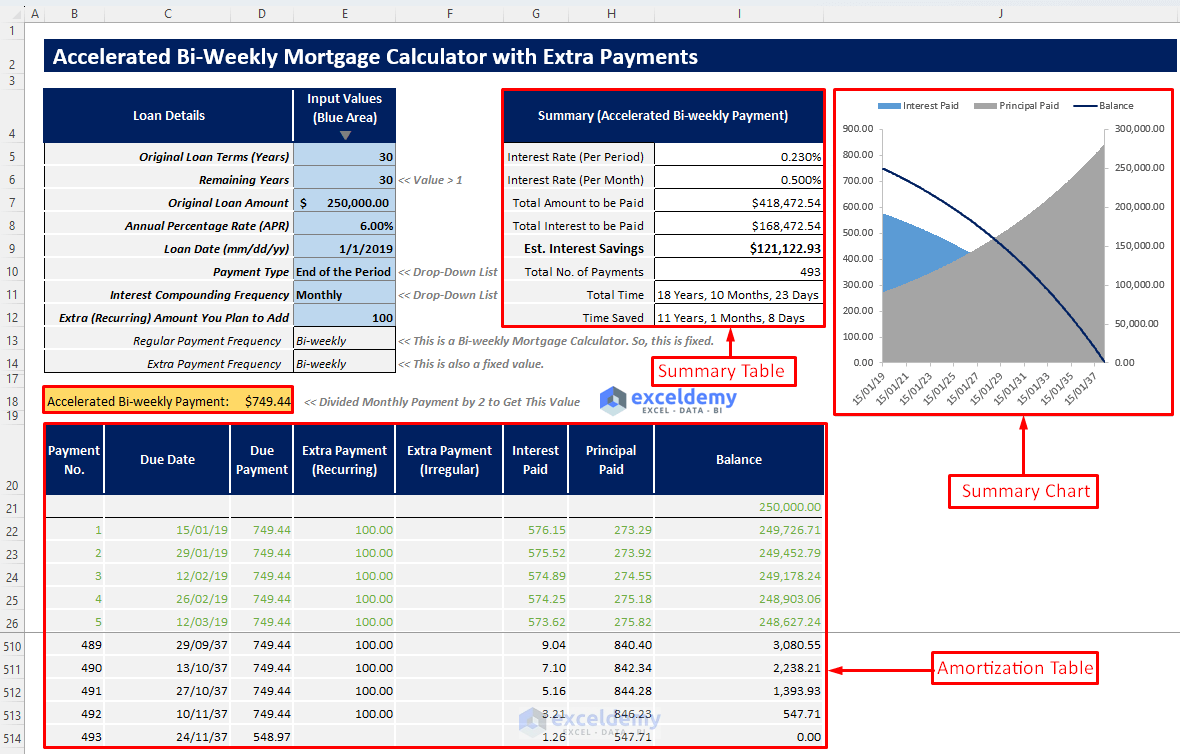
Biweekly Mortgage Payment Calculator should show you the accelerated payoff date, total interest under both schedules, and the cumulative principal paid each year. If it only shows the monthly payment split in half without projecting the new amortization, it is not doing its job.
Edge cases that break the simple model
Escrows change everything. If your monthly payment includes property taxes and insurance held in an escrow account, halving the total payment halves the escrow contribution too. That can create a shortfall if the servicer expects a full monthly escrow amount each cycle. I ran into this with a client who switched without adjusting the escrow holdback. The servicer started billing her for the shortfall every quarter because her tax bill jumped unexpectedly. She lost about $400 in unplanned payments in the first year alone. The fix was to contact the servicer and request that the escrow portion continue at the full monthly rate while only the principal and interest component ran on a biweekly cadence. Most servicers will do this if you ask. Many do not volunteer it.
Another trap is ARMs. If you have an adjustable-rate mortgage, the interest rate changes at set intervals, and your payment adjusts with it. A biweekly calculator that assumes a fixed rate will give you a misleading projection once the cap hits. I would recommend running the biweekly schedule only for the initial fixed period of an ARM, then recalculating after each adjustment. The savings from the biweekly cadence still exist during that window, but the total interest estimate shifts significantly once the rate moves.
Prepayment penalties matter too. Some loans, especially older ones or certain non-QM products, carry a yield-spread premium or prepayment fee if you pay down principal faster than a set threshold. I encountered a jumbo loan with a 3% penalty on any principal payment exceeding 20% of the original balance in the first two years. Switching to biweekly pushed that threshold easily. The borrower ended up paying nearly $18,000 in penalties that wiped out most of the interest savings. Always read the prepayment clause before you change payment frequency.
How to set it up without losing money to fees
Not all servicers offer biweekly programs, and the ones that do sometimes charge a setup fee or a monthly maintenance fee of $10 to $25. Over seven years that adds up to $840 to $2,100, which is meaningful when you are trying to save interest. I found the cheaper path was to self-administer the schedule through my own banking platform. You set up recurring biweekly transfers from your checking to a sub-account, then instruct your servicer to accept the payment on the exact date. The key is consistency. Miss two cycles and the whole advantage evaporates because the servicer resets to their default monthly rhythm.
Some borrowers try to game the system by paying slightly more than half each cycle, hoping to reach the equivalent of a thirteenth payment early. This works in theory but creates a reconciliation headache. If you deviate from the exact half, you need a tracking tool that can handle variable amounts, not just a static calculator. I built a simple spreadsheet that let me input the actual payment each cycle, recalculate the remaining balance, and project the new payoff date dynamically. It took me about an hour to set up and saved me from misallocating payments for three years.
When biweekly does not make sense
Refinancing is the obvious one. If you are within two years of paying off your loan, the interest savings from an accelerated schedule are negligible. On a balance under $50,000 with five years remaining, you might save a couple thousand dollars at most, and the administrative friction outweighs the gain.
Then there is cash flow fragility. Biweekly requires you to commit to a payment every 14 days, regardless of when your paycheck arrives. If you are monthly paid, you have to manage the gap yourself. I worked with a borrower whose income was irregular, and the rigid biweekly schedule caused three bounced payments in a single year. Late fees and the stress of catching up erased any benefit. For those situations, making one extra payment per year on a standard monthly schedule achieves the same mathematical result without the scheduling complexity.
Building your own calculator if you need control
A proper tool takes your current balance, rate, remaining months, and next payment date, then iterates day by day or period by period to show principal, interest, and remaining balance after each payment. The formula is straightforward:
Interest for the period equals remaining balance multiplied by the periodic rate. The periodic rate is your annual rate divided by 26 for biweekly. The principal portion equals your biweekly payment minus that interest. Subtract the principal portion from the balance and repeat.
I prefer using a spreadsheet with data validation so you can toggle between scenarios without rewriting formulas. Adding a conditional column that flags when your cumulative principal paid exceeds any prepayment penalty threshold is useful. One client found his penalty window by layering a simple conditional format in green and red. It took five minutes and prevented an $11,000 mistake.
The reason most people never build their own is that they assume a ready-made tool will cover it. A generic online calculator will not account for escrow timing mismatches, penalty windows, or the difference between your actual pay schedule and the theoretical 26-payment cycle. The gap between a rough estimate and an accurate projection is where people lose money, not in the core formula.