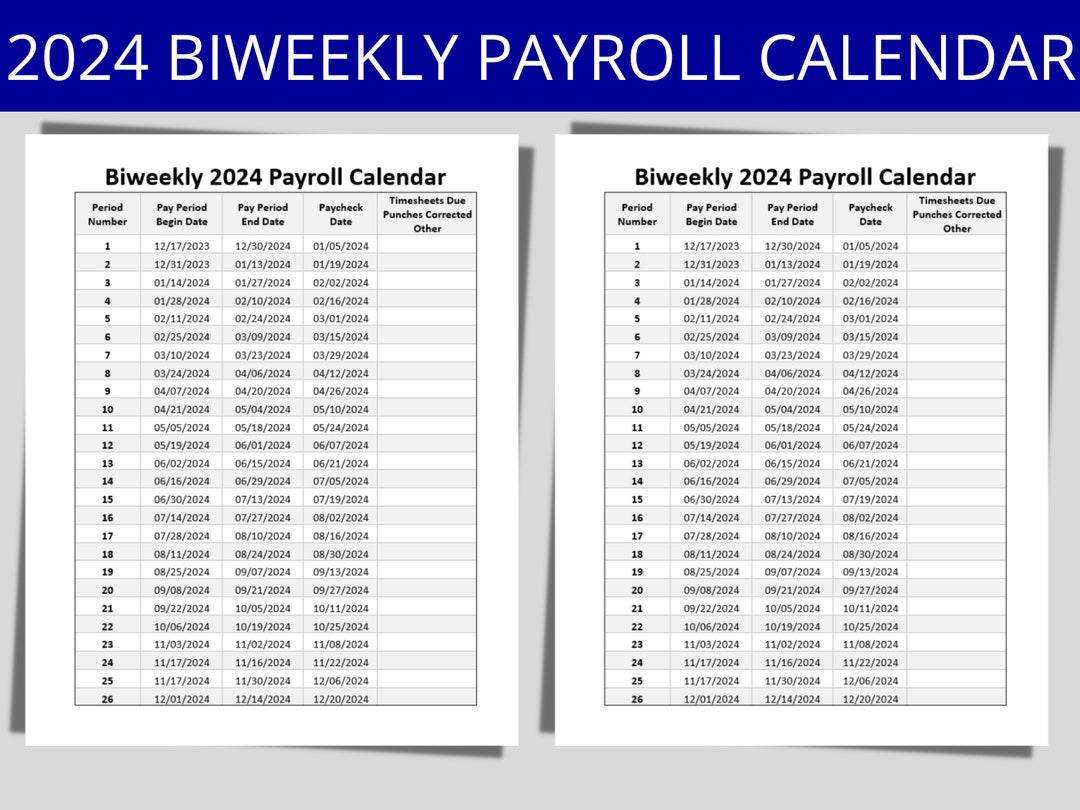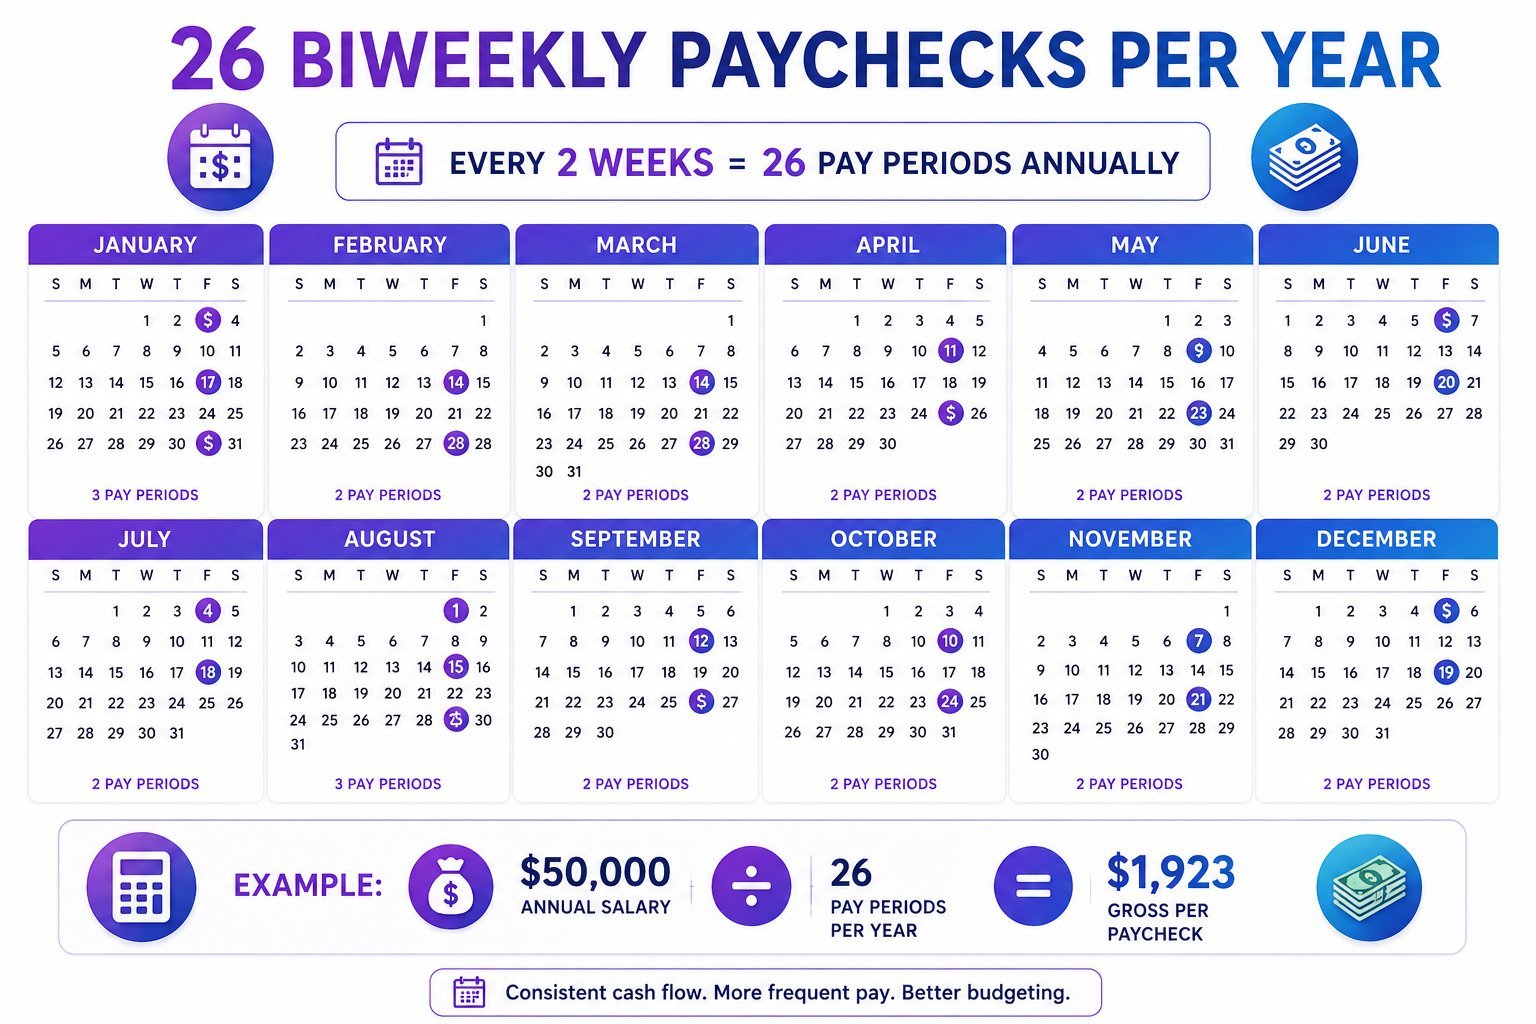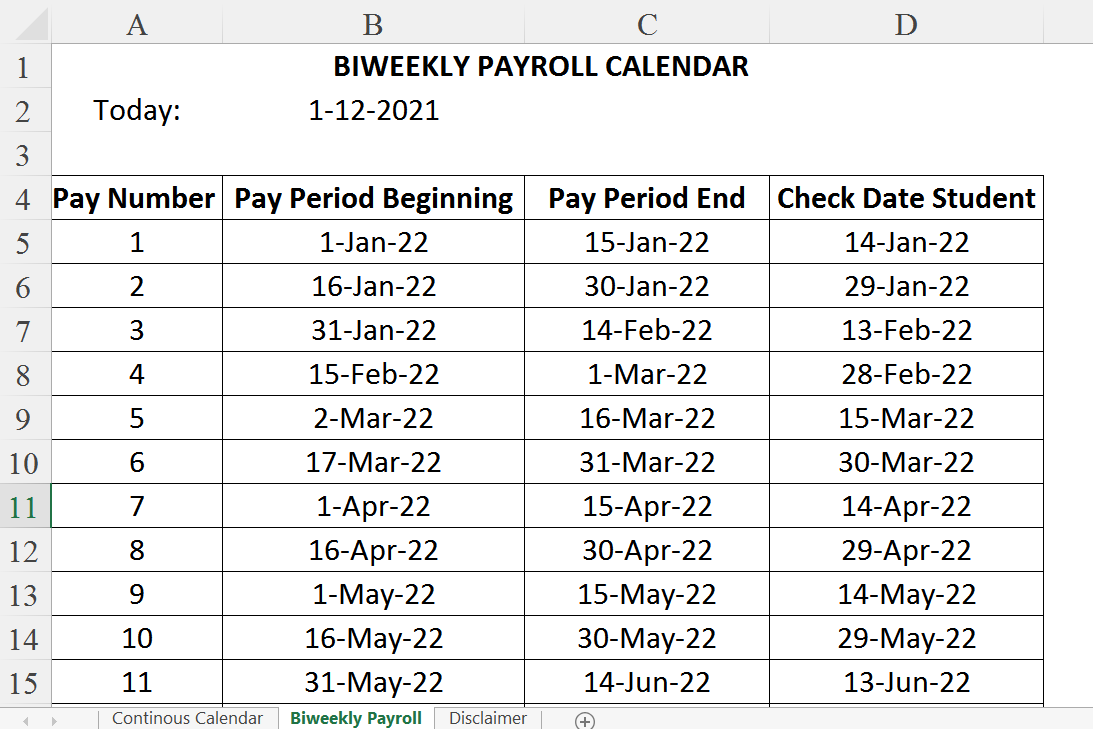
Understanding How Biweekly Payments Work
Biweekly payments are straightforward in theory but messy in practice. You pay every two weeks instead of monthly. That means 26 half-payments a year, which equals 13 full monthly payments. Most people miss that extra payment detail until they're deep into a mortgage and wondering where their money went. I dealt with this when advising a client who'd refinanced into a biweekly schedule. She assumed her payments would stay the same. They didn't. The lender split her monthly amount by two and set it to auto-deduct every other Friday. What she didn't realize is that because the calendar doesn't divide evenly into two-week chunks, she'd actually get two extra payments every few years. That sounds great until you see the prepayment penalties eat into the savings.
Biweekly Payments In A Year
Here's the math that actually matters. If your monthly payment is $1,200, a biweekly schedule means $600 every two weeks. Over 52 weeks, that's 26 payments of $600, totaling $15,600 annually. Compare that to $14,400 in monthly payments. The extra $1,200 goes straight to principal. On a 30-year loan at 6.5%, that difference shaves roughly seven years off the term and saves about $90,000 in interest over the life of the loan. Not bad for doing nothing differently except paying more frequently. The trap is assuming all lenders treat this the same way. I've seen three different calculation methods across major servicers. Some use a 26-pay model. Others calculate based on 52 weeks divided into payment periods that don't always land on the same day of the month. One lender I worked with recalculated the payment amount every year based on the remaining balance, which threw off my client's budgeting for six months before anyone caught it.
Setting It Up Properly
If you're doing this through your lender, start by asking for the exact terms in writing. I can't stress that enough. Verbal confirmations don't hold up when the statement comes out wrong. Get the payment schedule, the total annual amount, and a written acknowledgment of how prepayment penalties (if any) will be handled. Most servicers won't disclose the penalty clause upfront because they know you won't read past the first page. For those managing it independently, the approach is cleaner but requires discipline. Calculate your monthly payment, divide by two, and set up automatic transfers from your checking account on a consistent schedule. I use a standing order every other Friday at 8 AM. The consistency matters because missing a payment and trying to make it up later creates a cascade effect. I had a borrower who missed one biweekly payment, then tried to double up the next cycle. The lender applied the overpayment as a credit rather than to principal, which meant the borrower paid interest on money that should have already reduced the balance. The workaround I recommend is simple: set up two separate automatic payments if your banking platform allows it. One for even weeks, one for odd weeks. This eliminates the manual adjustment risk entirely. It also means if one payment fails due to insufficient funds, you catch it immediately rather than discovering it three weeks later when the next payment also bounces.
Get the Full Details
What People Get Wrong
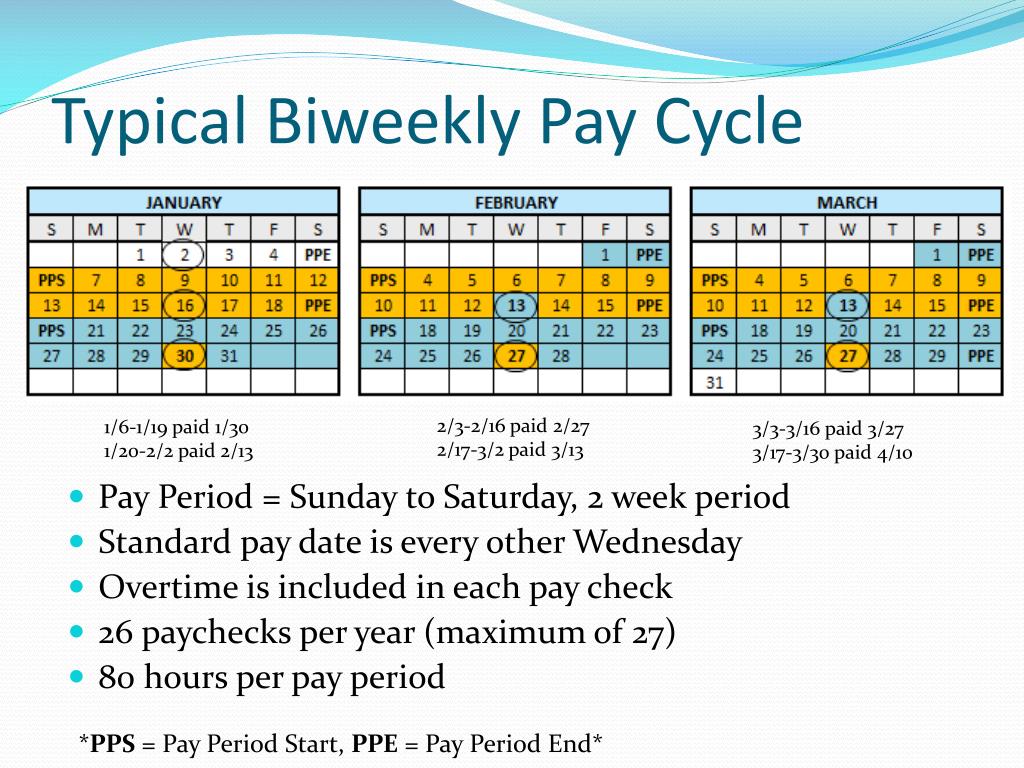
The biggest mistake I see is assuming biweekly payments automatically accelerate your payoff. They don't if you're not actually paying extra. Some servicers interpret "biweekly" as simply splitting your monthly payment in half without adding the thirteenth payment. You'd be paying the same total annually but with half the cash flow pressure. That's useful for budgeting but doesn't save you anything on interest. Another common issue is the timing mismatch between your pay schedule and the payment schedule. If you're paid monthly on the 15th but your biweekly payment falls on a Friday that's three weeks after your paycheck, you're working with negative float for part of the cycle. I've watched people drain their emergency fund trying to bridge that gap. The fix is either shifting your payment date manually or negotiating with the lender to align it with your pay period. Most lenders will accommodate this once — it's easier for them than dealing with repeated NSF fees. There's also the tax angle that nobody talks about. Property tax and escrow payments are typically bundled into your monthly mortgage statement. When you switch to biweekly, those escrow components don't adjust automatically. Your escrow shortage or surplus calculations become unreliable for the first year because the servicer is still projecting based on monthly cash flows. Budget an extra two months of escrow analysis before you lock in the schedule permanently.
When It Doesn't Make Sense
Biweekly payments aren't universal. If you're on an adjustable-rate mortgage with a cap that resets soon, the extra principal won't help you much if the rate jumps anyway. Same situation if you have high-interest debt elsewhere — credit cards at 22% will eat any mortgage savings in a year. Pay the card down first. The math is brutal but honest. I also don't recommend this for borrowers whose income is variable. Commission-based salespeople, freelancers, and seasonal workers should avoid it unless they have a six-month cash reserve. A missed biweekly payment during a lean quarter creates compounding problems that monthly payments wouldn't cause. The frequency itself becomes the liability. There's a scenario where biweekly payments actively hurt your financial position. If your lender charges a setup fee exceeding $500 and you plan to sell within three years, the break-even point never arrives. I ran the numbers for a client who paid a $750 initiation fee and moved within 18 months. The interest savings were approximately $320. She lost $430 by switching. Don't skip the fee disclosure. It's always buried in section 4 or 5 of the agreement.