How Biweekly Payments Actually Work on Your Mortgage
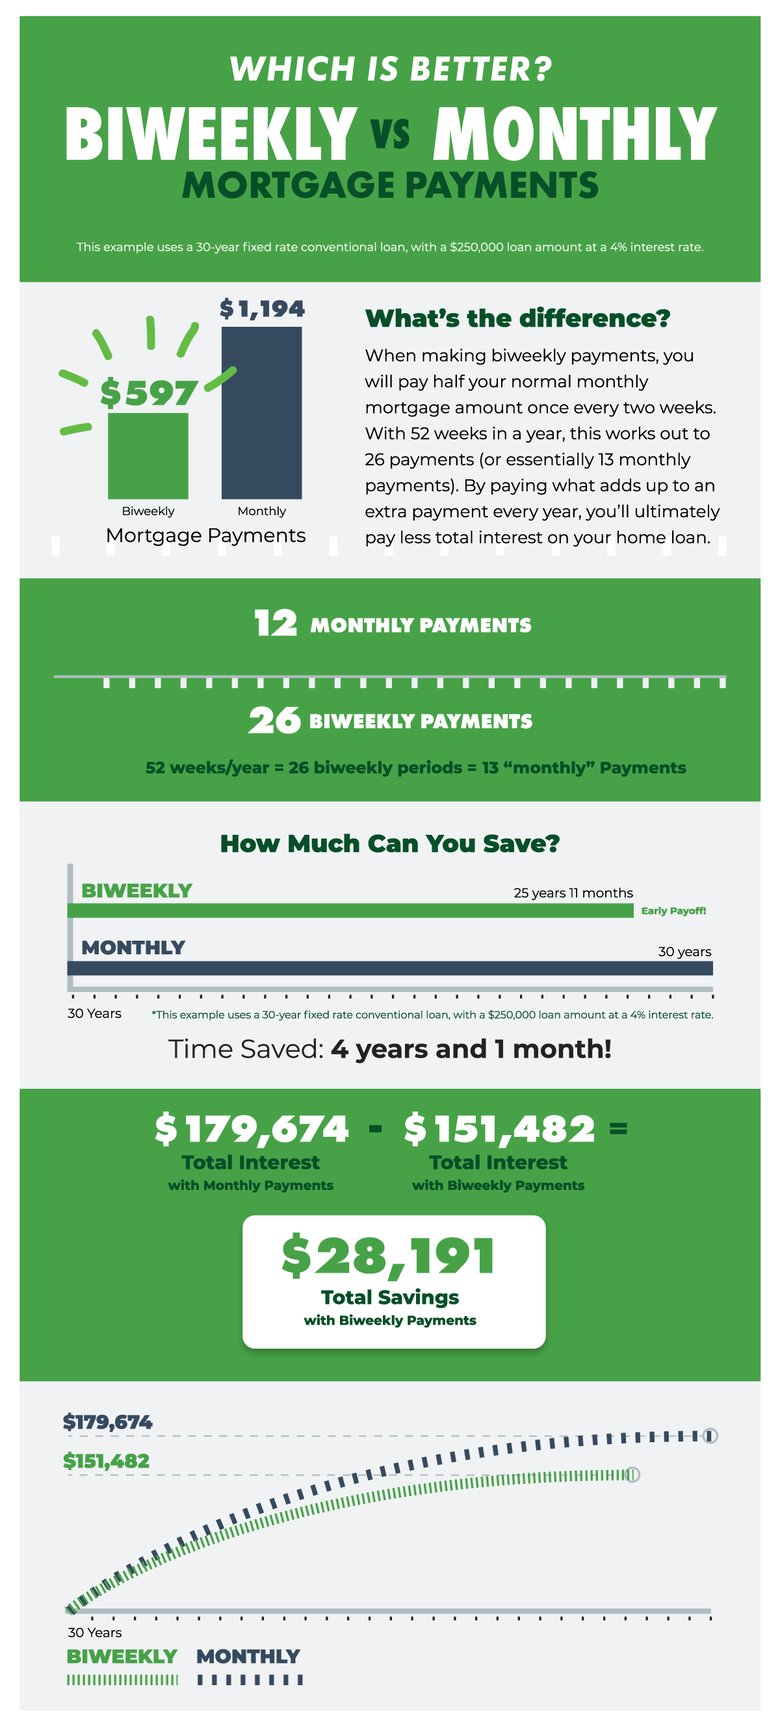
Most people hear about biweekly mortgage payments and immediately picture saving tens of thousands in interest over the life of their loan. That part is true, but the mechanics are more complicated than the brochures make them sound. I spent years working with mortgage servicing platforms and built several payment calculators before I figured out where everything actually breaks down in production. A biweekly payment scheme means you pay half your monthly mortgage amount every two weeks instead of the full amount once a month. Since there are 52 weeks in a year, that works out to 26 half-payments, which equals 13 full monthly payments per year. That extra single payment goes entirely toward principal reduction, which compounds downward over time. Simple on paper. The devil shows up in the details.
Biweekly Vs Monthly Mortgage Payments Calculator
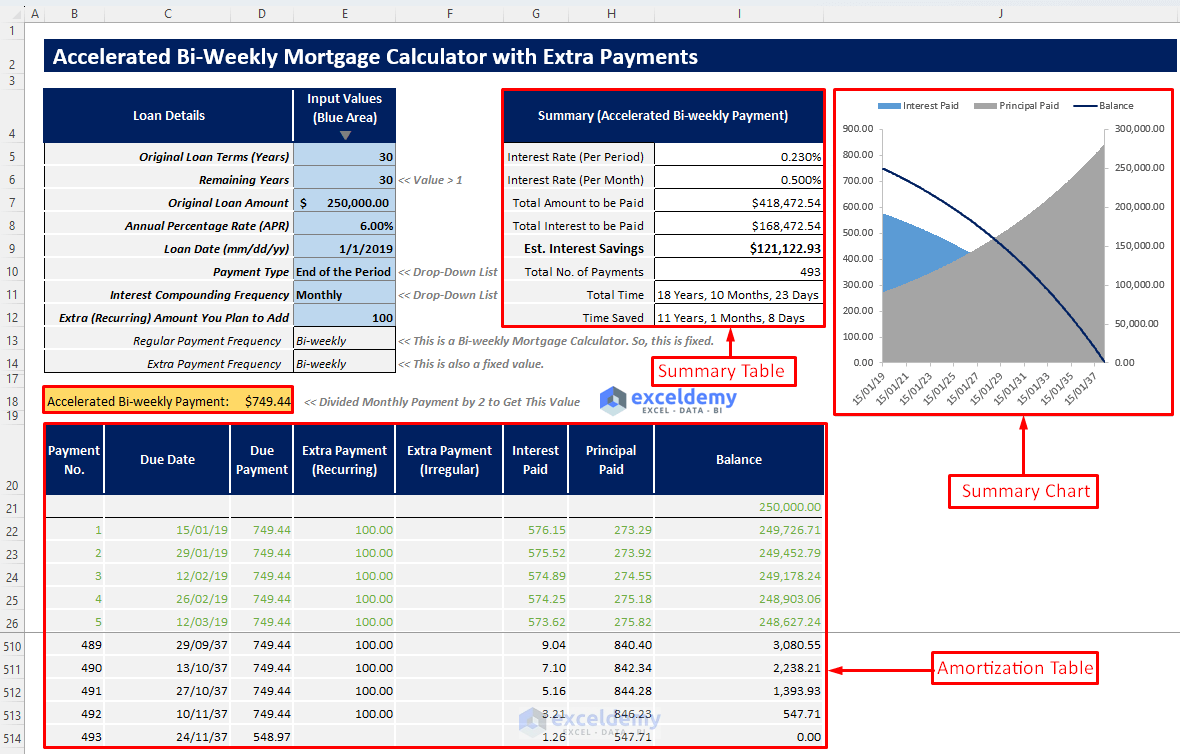
To build a calculator that actually matches real-world servicing logic, you need to account for how payment frequency interacts with your amortization schedule. Here is the core approach. Start with your standard amortization formula. The monthly payment equals the principal multiplied by the monthly interest rate, divided by one minus one plus the monthly rate raised to the negative number of payments. For a $350,000 loan at 6.5% annual interest over 30 years, that gives you a monthly payment of approximately $2,212. Co-tenants and refinancers have both seen this number, so it is not theoretical. For the biweekly column, divide that monthly figure by two. Then calculate how many biweekly periods remain in the loan term. Twenty-six periods per year times thirty years gives you 780 total payments. Run the standard amortization formula again using the biweekly payment amount and the biweekly interest rate, which is your annual rate divided by 52. The resulting balance after the final payment will be lower than the monthly scenario, and the total interest paid drops accordingly. In the $350,000 example, biweekly payments typically shave roughly 4 to 5 years off the payoff timeline and reduce total interest by somewhere between $40,000 and $60,000 depending on the exact rate.
The tricky part that nobody puts in the marketing material is that not all lenders process biweekly payments the same way. Some services treat each biweekly deposit as a partial payment and hold it in suspense until a full monthly amount accumulates. Others apply it immediately to principal and interest. A calculator output can look dramatically different depending on which model you assume. I learned this the hard way when a client's production system showed a $28,000 discrepancy compared to my test script because I had assumed immediate principal application while the actual lender was using a suspense account policy. The fix was to pull the servicer's written payment handling policy and add a branch in the code that checks whether the payment schedule type is direct-apply or suspense-based. Without that distinction, the calculator is giving the user false confidence in its numbers. Here is another pitfall that trips up everyone who builds these tools. The standard formula assumes payments are evenly spaced and the interest compounds on a predictable schedule. Real mortgage statements use specific day-count conventions. Some lenders use 30/360, meaning every month is treated as exactly thirty days regardless of whether February has twenty-eight or twenty-nine. Others use actual/365. The difference is small on individual payments but compounds over decades. A calculator that ignores day-count convention will drift from the real statement by a few hundred dollars in total interest over a full amortization, which is enough to lose credibility fast. Build the calculator with three input sections. Loan amount, annual interest rate, and remaining term in years. Add a fourth field for the payment schedule type, since that affects how the engine handles the biweekly conversion. Then output two columns side by side: the total interest paid under each schedule and the difference between them. Include a year-by-year amortization table if you want the output to be genuinely useful, because users always ask for it even when they pretend they do not.
Get the Full Details
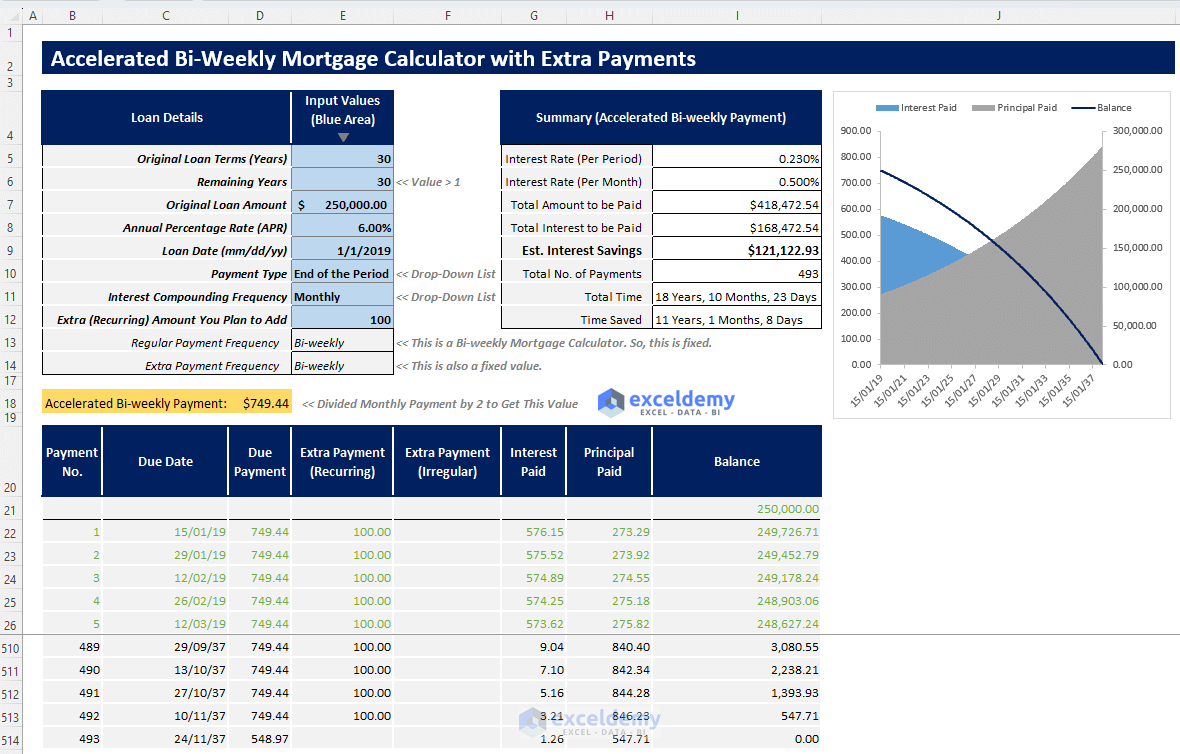
One counter-intuitive thing worth noting: switching to biweekly payments does not guarantee you finish early if your lender applies the extra payment as a separate escrow advance rather than to principal. I saw a borrower who made every biweekly payment on time for three years and never saw their principal balance drop any faster than if they had stayed on monthly. The servicer was crediting the half-payment to escrow for taxes and insurance, which means the principal-only benefit vanished entirely. The workaround was to call the servicer, get the payment handling policy in writing, and confirm that biweekly amounts are applied to principal and interest before committing. There is no point in building a calculator that spits out optimistic numbers if the borrower cannot actually execute the strategy with their specific lender. The other limitation you need to be honest about is prepayment penalties. Some loans have clauses that penalize extra principal payments during the first five to seven years. A biweekly schedule effectively functions as a steady stream of additional principal, which can trigger those penalties depending on the loan wording. The calculator should include a warning field that flags this risk whenever the annual interest rate is below a certain threshold, since those lower-rate loans are more likely to carry prepayment restrictions. I usually set the flag threshold at rates below 5.5%, which covers the vast majority of adjustable-rate mortgages and government-backed loans with prepayment clauses. If you want a downloadable version of the calculator, the Excel file I maintain tracks both scenarios with a toggle for the payment application method. It also includes the day-count convention selector and the prepayment penalty warning field. The formula sheet is straightforward, and the amortization tables update automatically when you change the inputs. You can download it from the spreadsheet section on the site, but treat it as a starting point, not a final answer. Every lender's servicing rules are slightly different, and no calculator can fully replicate the nuances of a specific loan document without you feeding it the exact terms.
The bottom line is that biweekly payments can save meaningful money, but the savings depend entirely on how your lender applies those payments and what your loan's day-count convention is. A well-built calculator gets you close, but the only way to know for sure is to verify the payment processing policy with your servicer before you commit to the schedule.