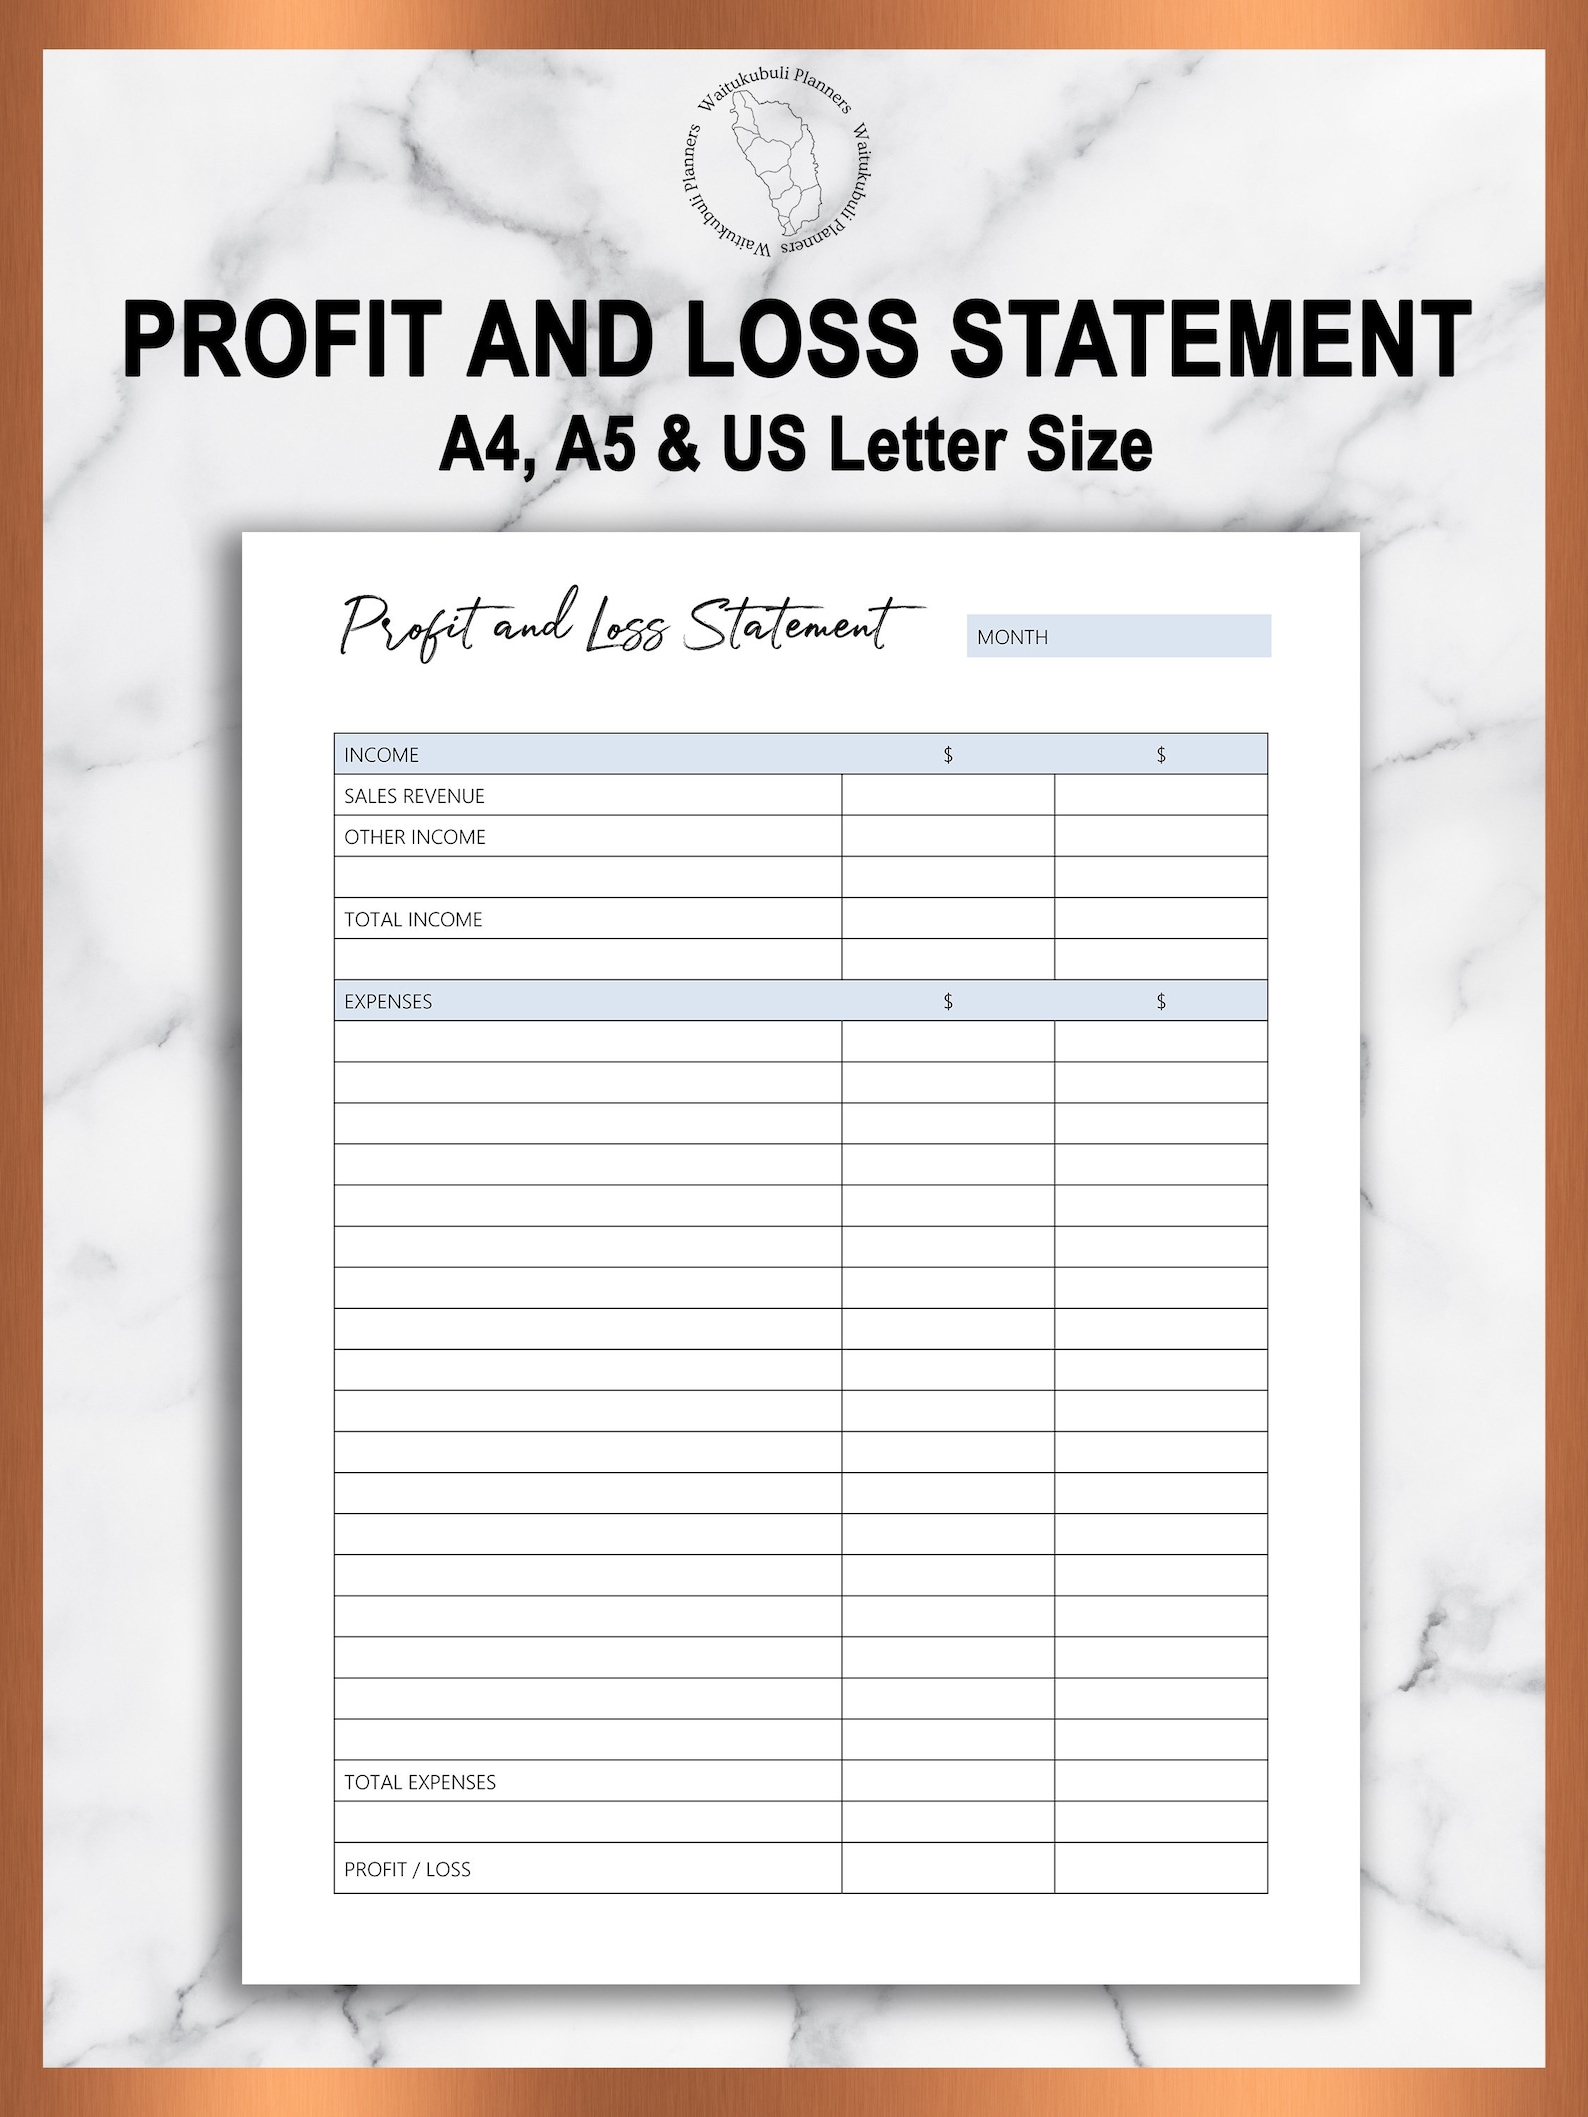
What a Blank Profit and Loss Statement Actually Is
A blank profit and loss statement is just a template with no pre-filled numbers. It's the starting point you use before you enter any revenue, costs, or expenses for a given period. Some people call it a P&L template, a profit and loss form, or an income statement sheet. Same thing. It's an accounting document that tracks income against expenses over time to show whether a business made money or lost money in that window. I've seen a lot of templates online that claim to be ready to use. Most of them are either too simple or loaded with assumptions you didn't ask for. The real value of a blank one is that you build it exactly how your business works, without someone else's categories forcing you into a shape that doesn't fit.
Download a Blank Profit And Loss Statement
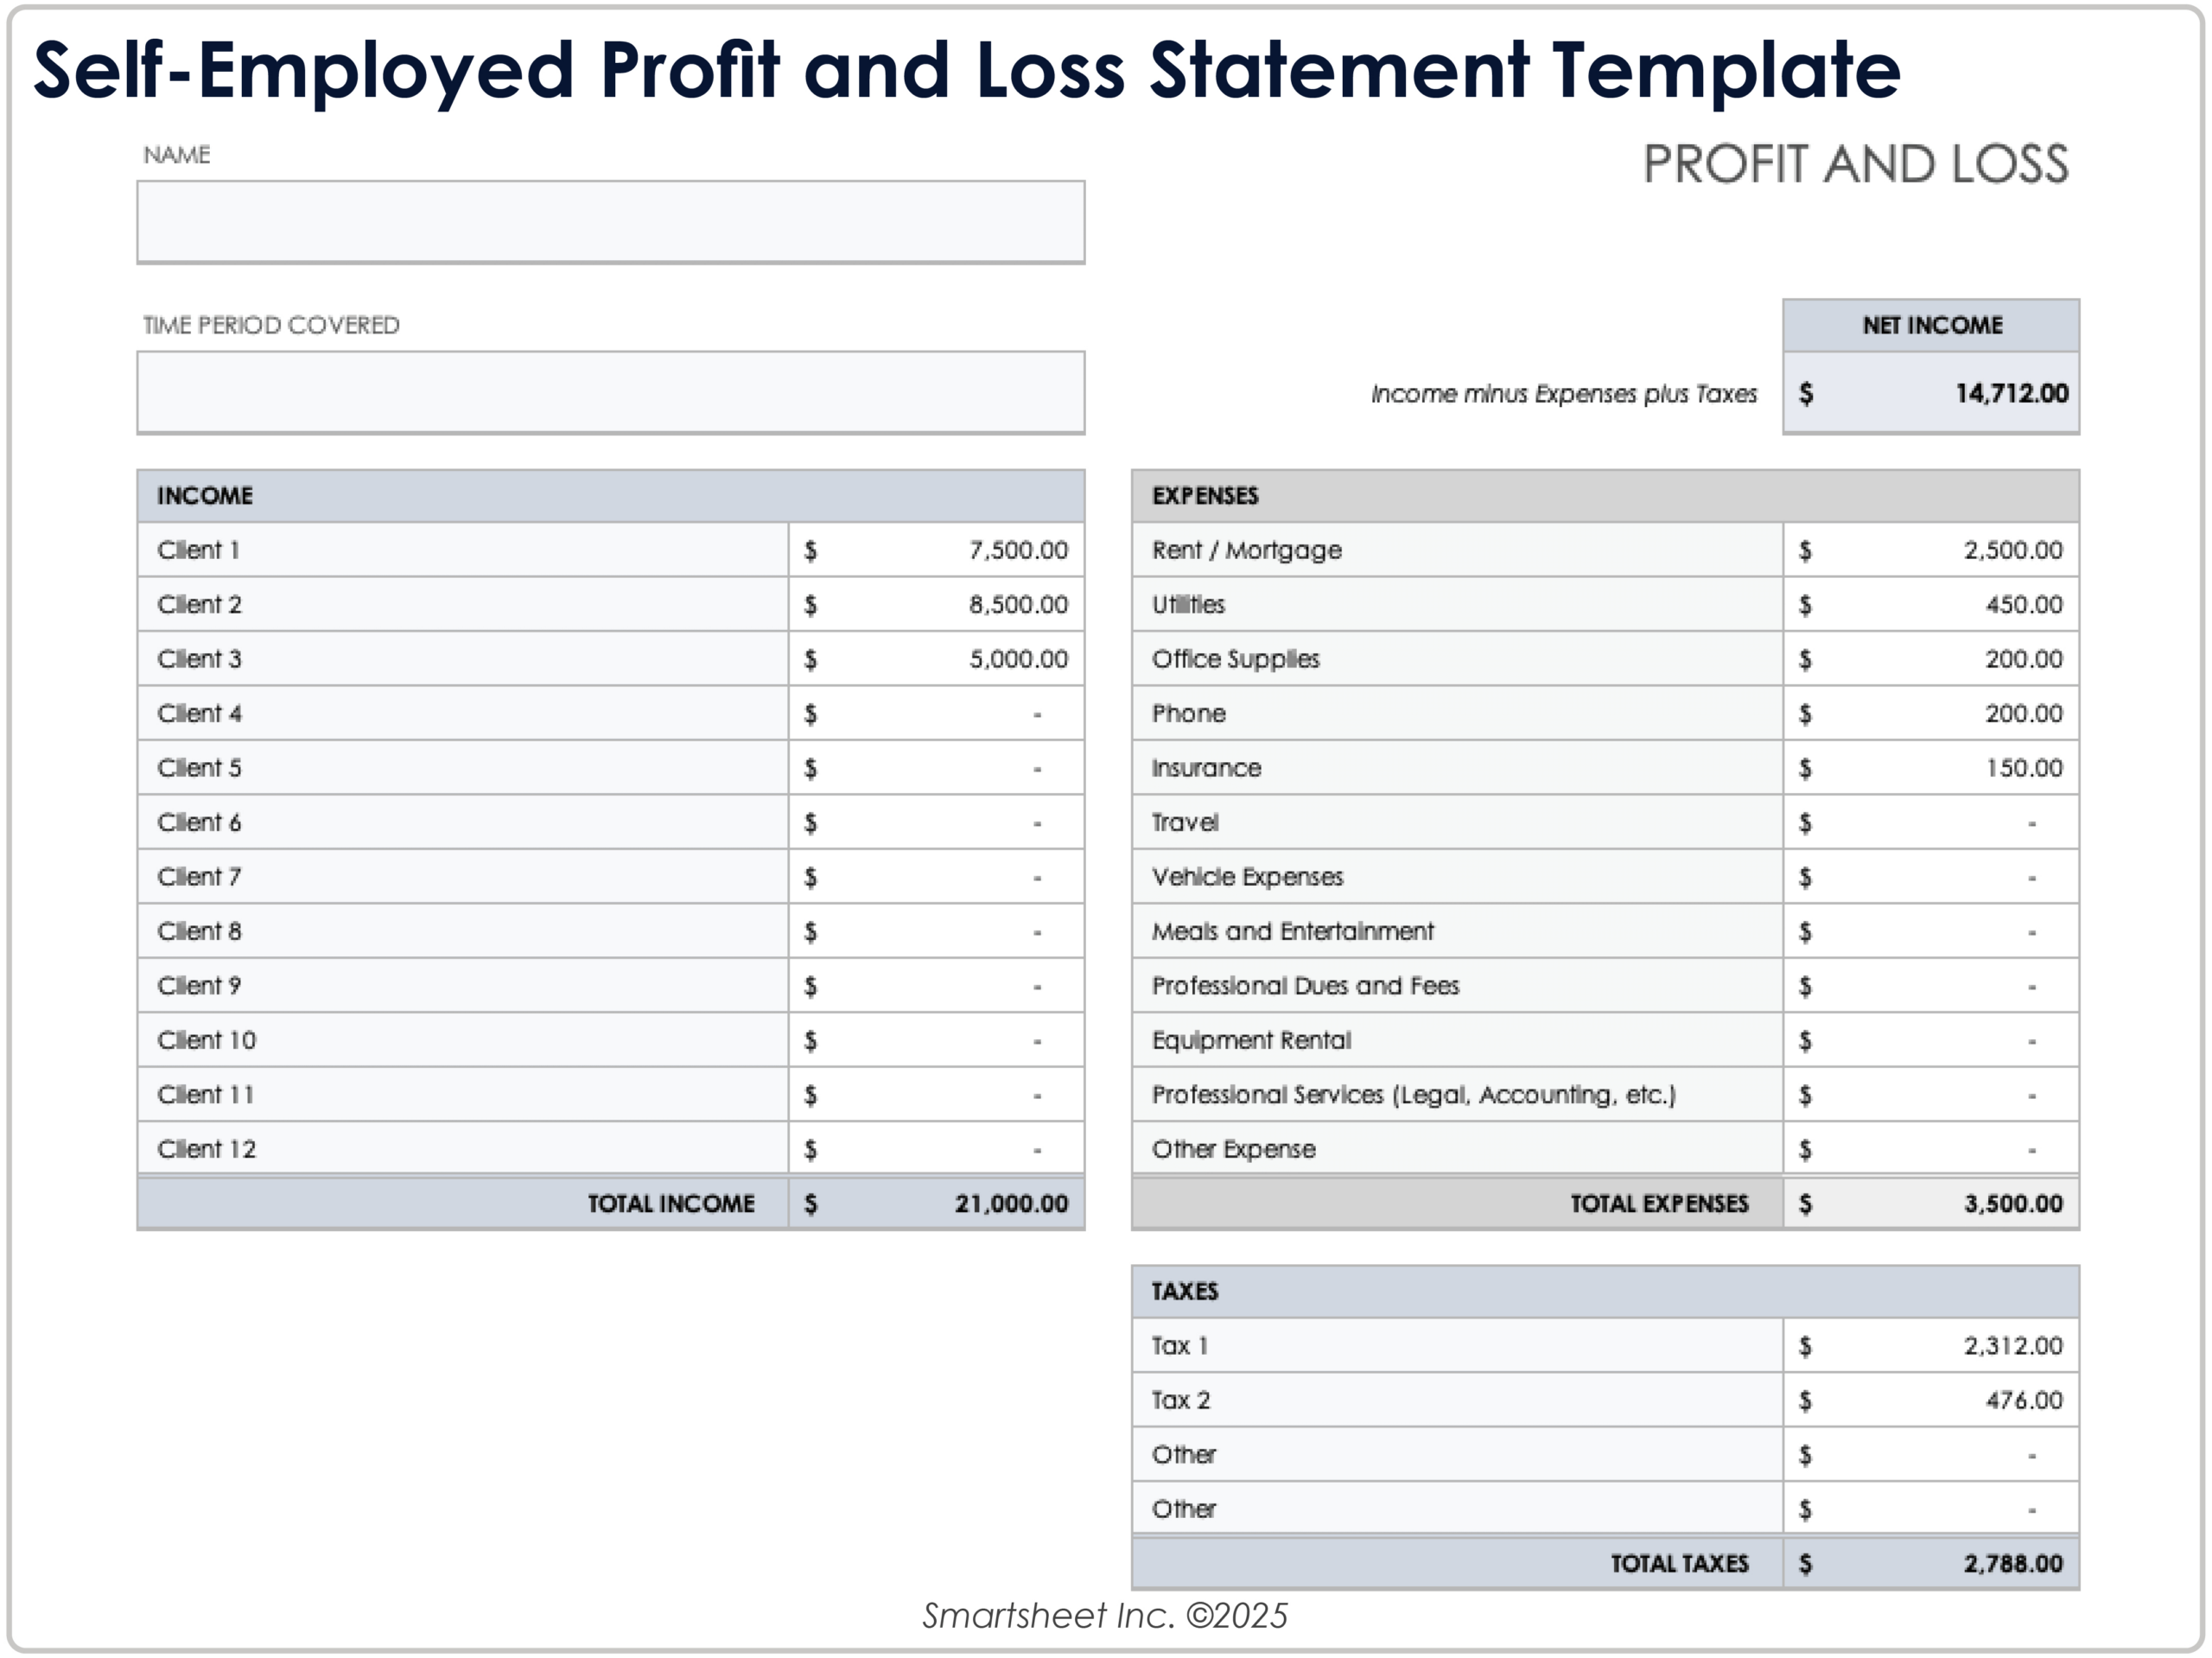
You can find free templates in Google Sheets, Excel, or as PDFs on sites like Microsoft's template gallery, vertex42, or Smartsheet. But here's the thing I always tell people: download one, then strip it down to the bare minimum and rebuild it. The defaults are usually designed for a service business or a generic retail operation. If you're a contractor, a restaurant, or a subscription business, the pre-loaded categories will either confuse you or create work later when you have to rename things. Start with a simple structure. Open a spreadsheet. Create three main sections: revenue, expenses, and net profit. That's it. Revenue goes at the top. Under that, list every expense category that actually applies to your business. Then subtract total expenses from total revenue at the bottom to get your net profit or loss. Here's a basic layout you can copy:
Revenue Product sales / Service income / Other income Cost of Goods Sold (COGS)
Get the Full Details
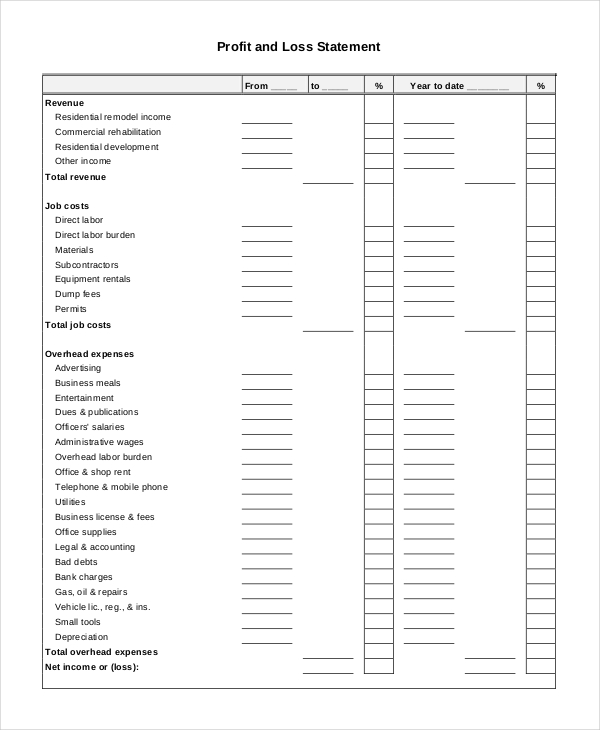
Materials / Labor directly tied to production / Shipping out Gross Profit Revenue minus COGS
Operating Expenses Rent / Utilities / Insurance / Marketing / Software subscriptions / Payroll / Taxes / Professional fees Net Profit / Loss
Gross profit minus operating expenses That's the skeleton. Everything else is customization. Add or remove categories based on what you actually spend money on. Don't add a category just because it looks organized. An empty line item is worse than a missing one because it creates confusion later when you try to reconcile.

Common Mistakes People Make
The biggest mistake I see is people treating their P&L like it has to match their bank account perfectly. It doesn't. A P&L is built on accrual accounting or cash accounting depending on which method you use, and the timing of when you record things is different from when money actually moves. If you're on cash basis, you record revenue when you get paid and expenses when you pay them. If you're on accrual, you record them when they're earned or incurred, regardless of payment timing. Pick one and stick with it. Mixing methods in the same statement is how you get numbers that don't make sense to anyone. Another mistake is not separating COGS from operating expenses. These two serve different purposes. COGS goes directly toward producing your product or service. Operating expenses are the overhead you pay regardless of how much you sell. When you mix them together, your gross margin calculation becomes useless, and you lose the ability to see whether your core business model is actually profitable before overhead eats into it.
A Specific Problem I Ran Into
Early on, I was working with a client who had a subscription-based service with monthly billing and annual contracts. The blank P&L template we downloaded from the internet had a single "Revenue" line. That didn't work because revenue was recognized differently depending on whether the customer paid monthly or annually. Prepaid annual revenue sits on the books as deferred revenue until it's earned month by month. A flat revenue line buried that reality and made the P&L look wildly inaccurate for any month where a big annual payment came in. The workaround was to add a deferred revenue adjustment section under revenue. Instead of recording the full annual payment as income upfront, I split it into twelve equal portions across the contract period. This took about twenty minutes to set up but prevented months of reconciling weird spikes in the numbers. If your business has any prepaid or recurring revenue component, factor that in from day one.
How Often Should You Update It
Monthly is the standard cadence for most small businesses. Weekly is useful if cash flow is tight and you need to catch problems early. Quarterly is fine if your business is stable and you just need the high-level view for taxes or investor reporting. Don't do it annually unless you're completely disorganized, because by then you'll be guessing at expenses instead of recording them. There are situations where a simple template falls apart. If you run multiple revenue streams, need department-level profitability, or operate across different currencies, a basic spreadsheet gets unwieldy fast. In those cases, accounting software like QuickBooks, Xero, or FreshBooks will handle categorization, multi-entity tracking, and automated reconciliation better than a hand-built sheet. The tradeoff is cost and learning curve. A good template is free and takes ten minutes to set up. Software costs money and usually requires a few hours of initial configuration. For a solo freelancer with one income stream, the template is the right call. For anything more complex, the software pays for itself in time saved during tax season. Your P&L should match your bank statements at the end of each period. If it doesn't, something got recorded twice, missed, or put in the wrong category. I used to skip this step because it felt like extra work. Then I learned that skipping it means you're flying blind. A thirty-minute reconciliation at the end of each month catches errors before they compound. You compare every line item in your P&L against actual bank transactions and flag anything that doesn't align. Most mismatches are simple mistakes like a supplier payment categorized under the wrong vendor or a refund recorded as income instead of a deduction.
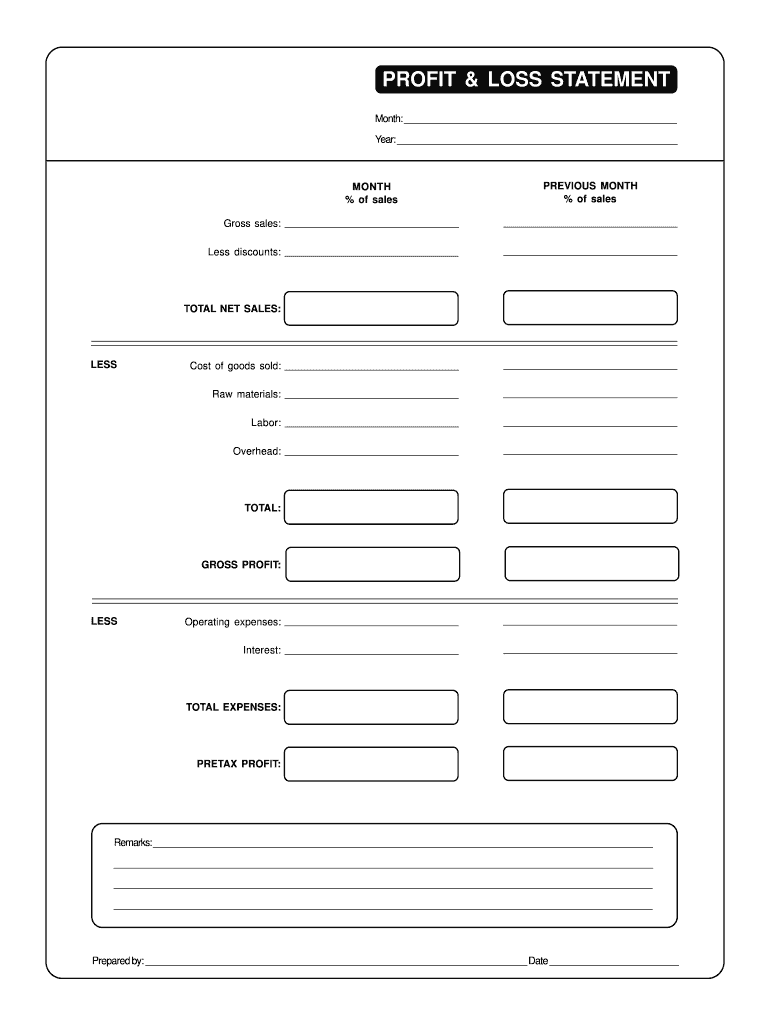
Once you've filled it in, review the numbers. Look at your gross margin percentage. If it's declining, your costs are growing faster than your revenue. Look at operating expense trends. Are they creeping up month over month? Check net profit. If it's negative for more than two consecutive months, something needs to change. Don't ignore red numbers hoping they'll fix themselves. Keep the statement for your records. Most businesses need to retain financial statements for at least seven years for tax purposes. Save a copy in a cloud folder with a consistent naming convention so you can pull it up whenever you need it. Something like "P&L_2024_03.xlsx" is easier to find than "final_version_really_final_v2.xlsx."