Understanding Board Resolutions for Retirement Plans Using American Funds
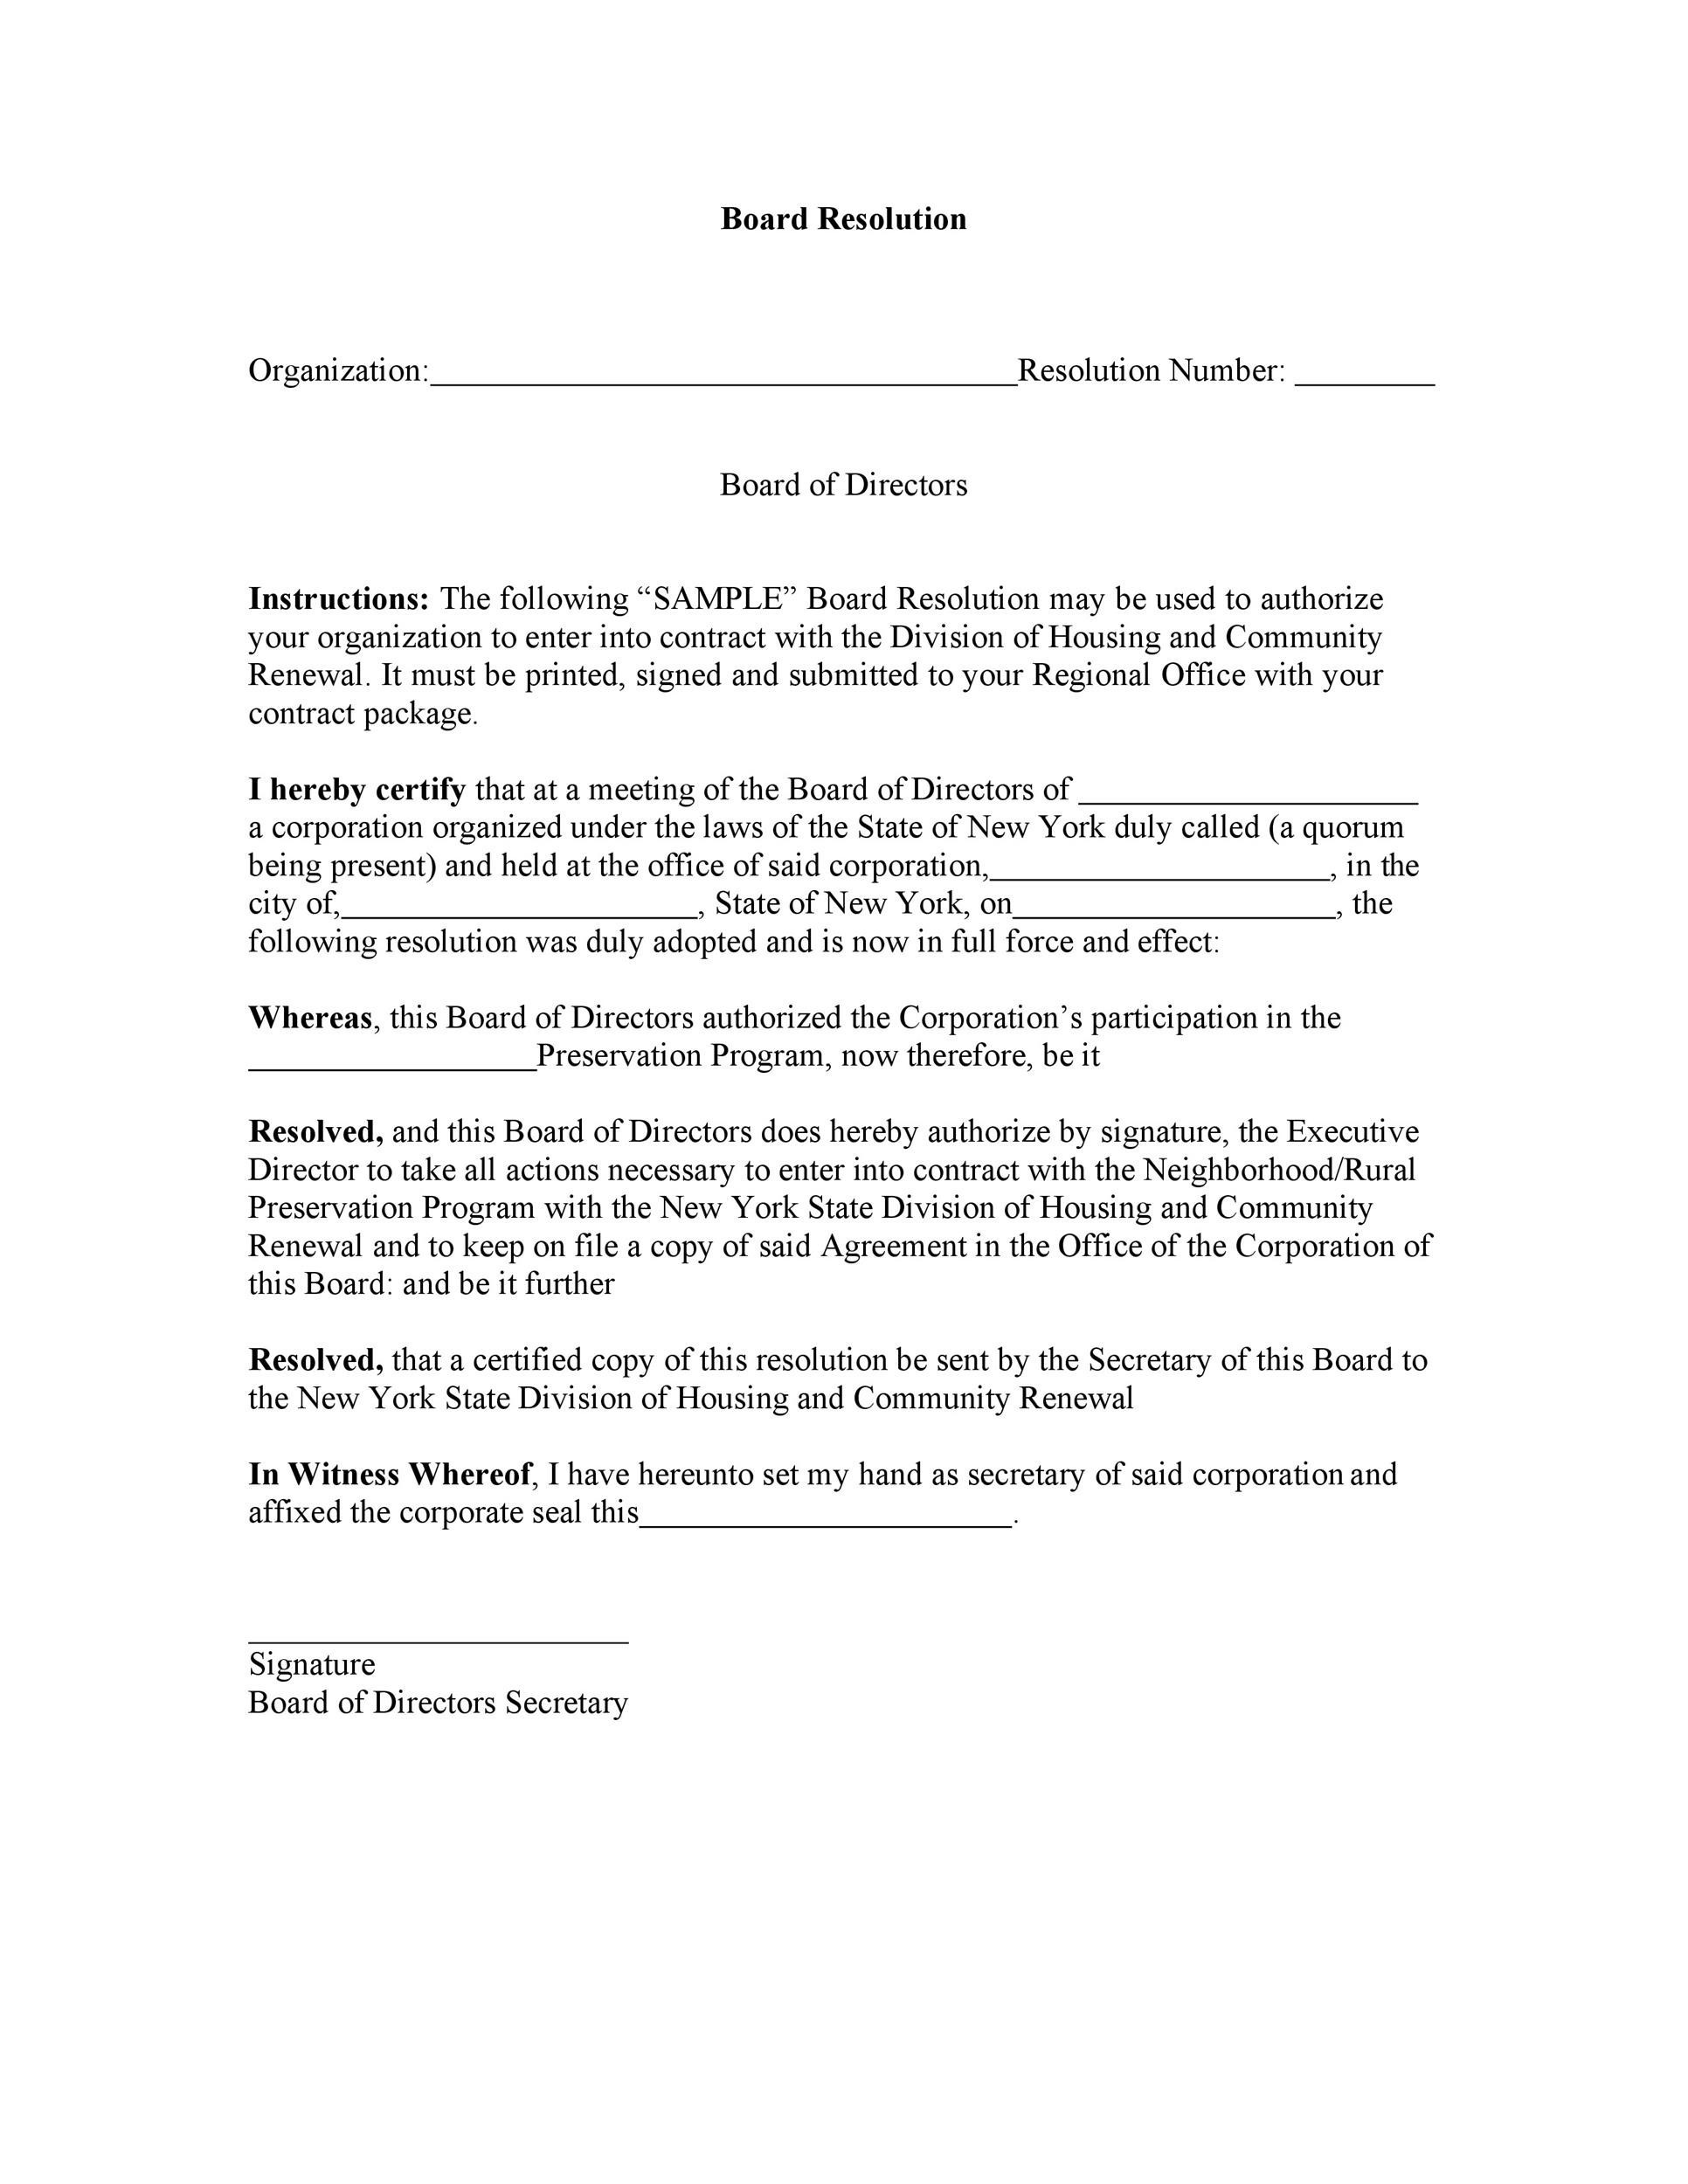
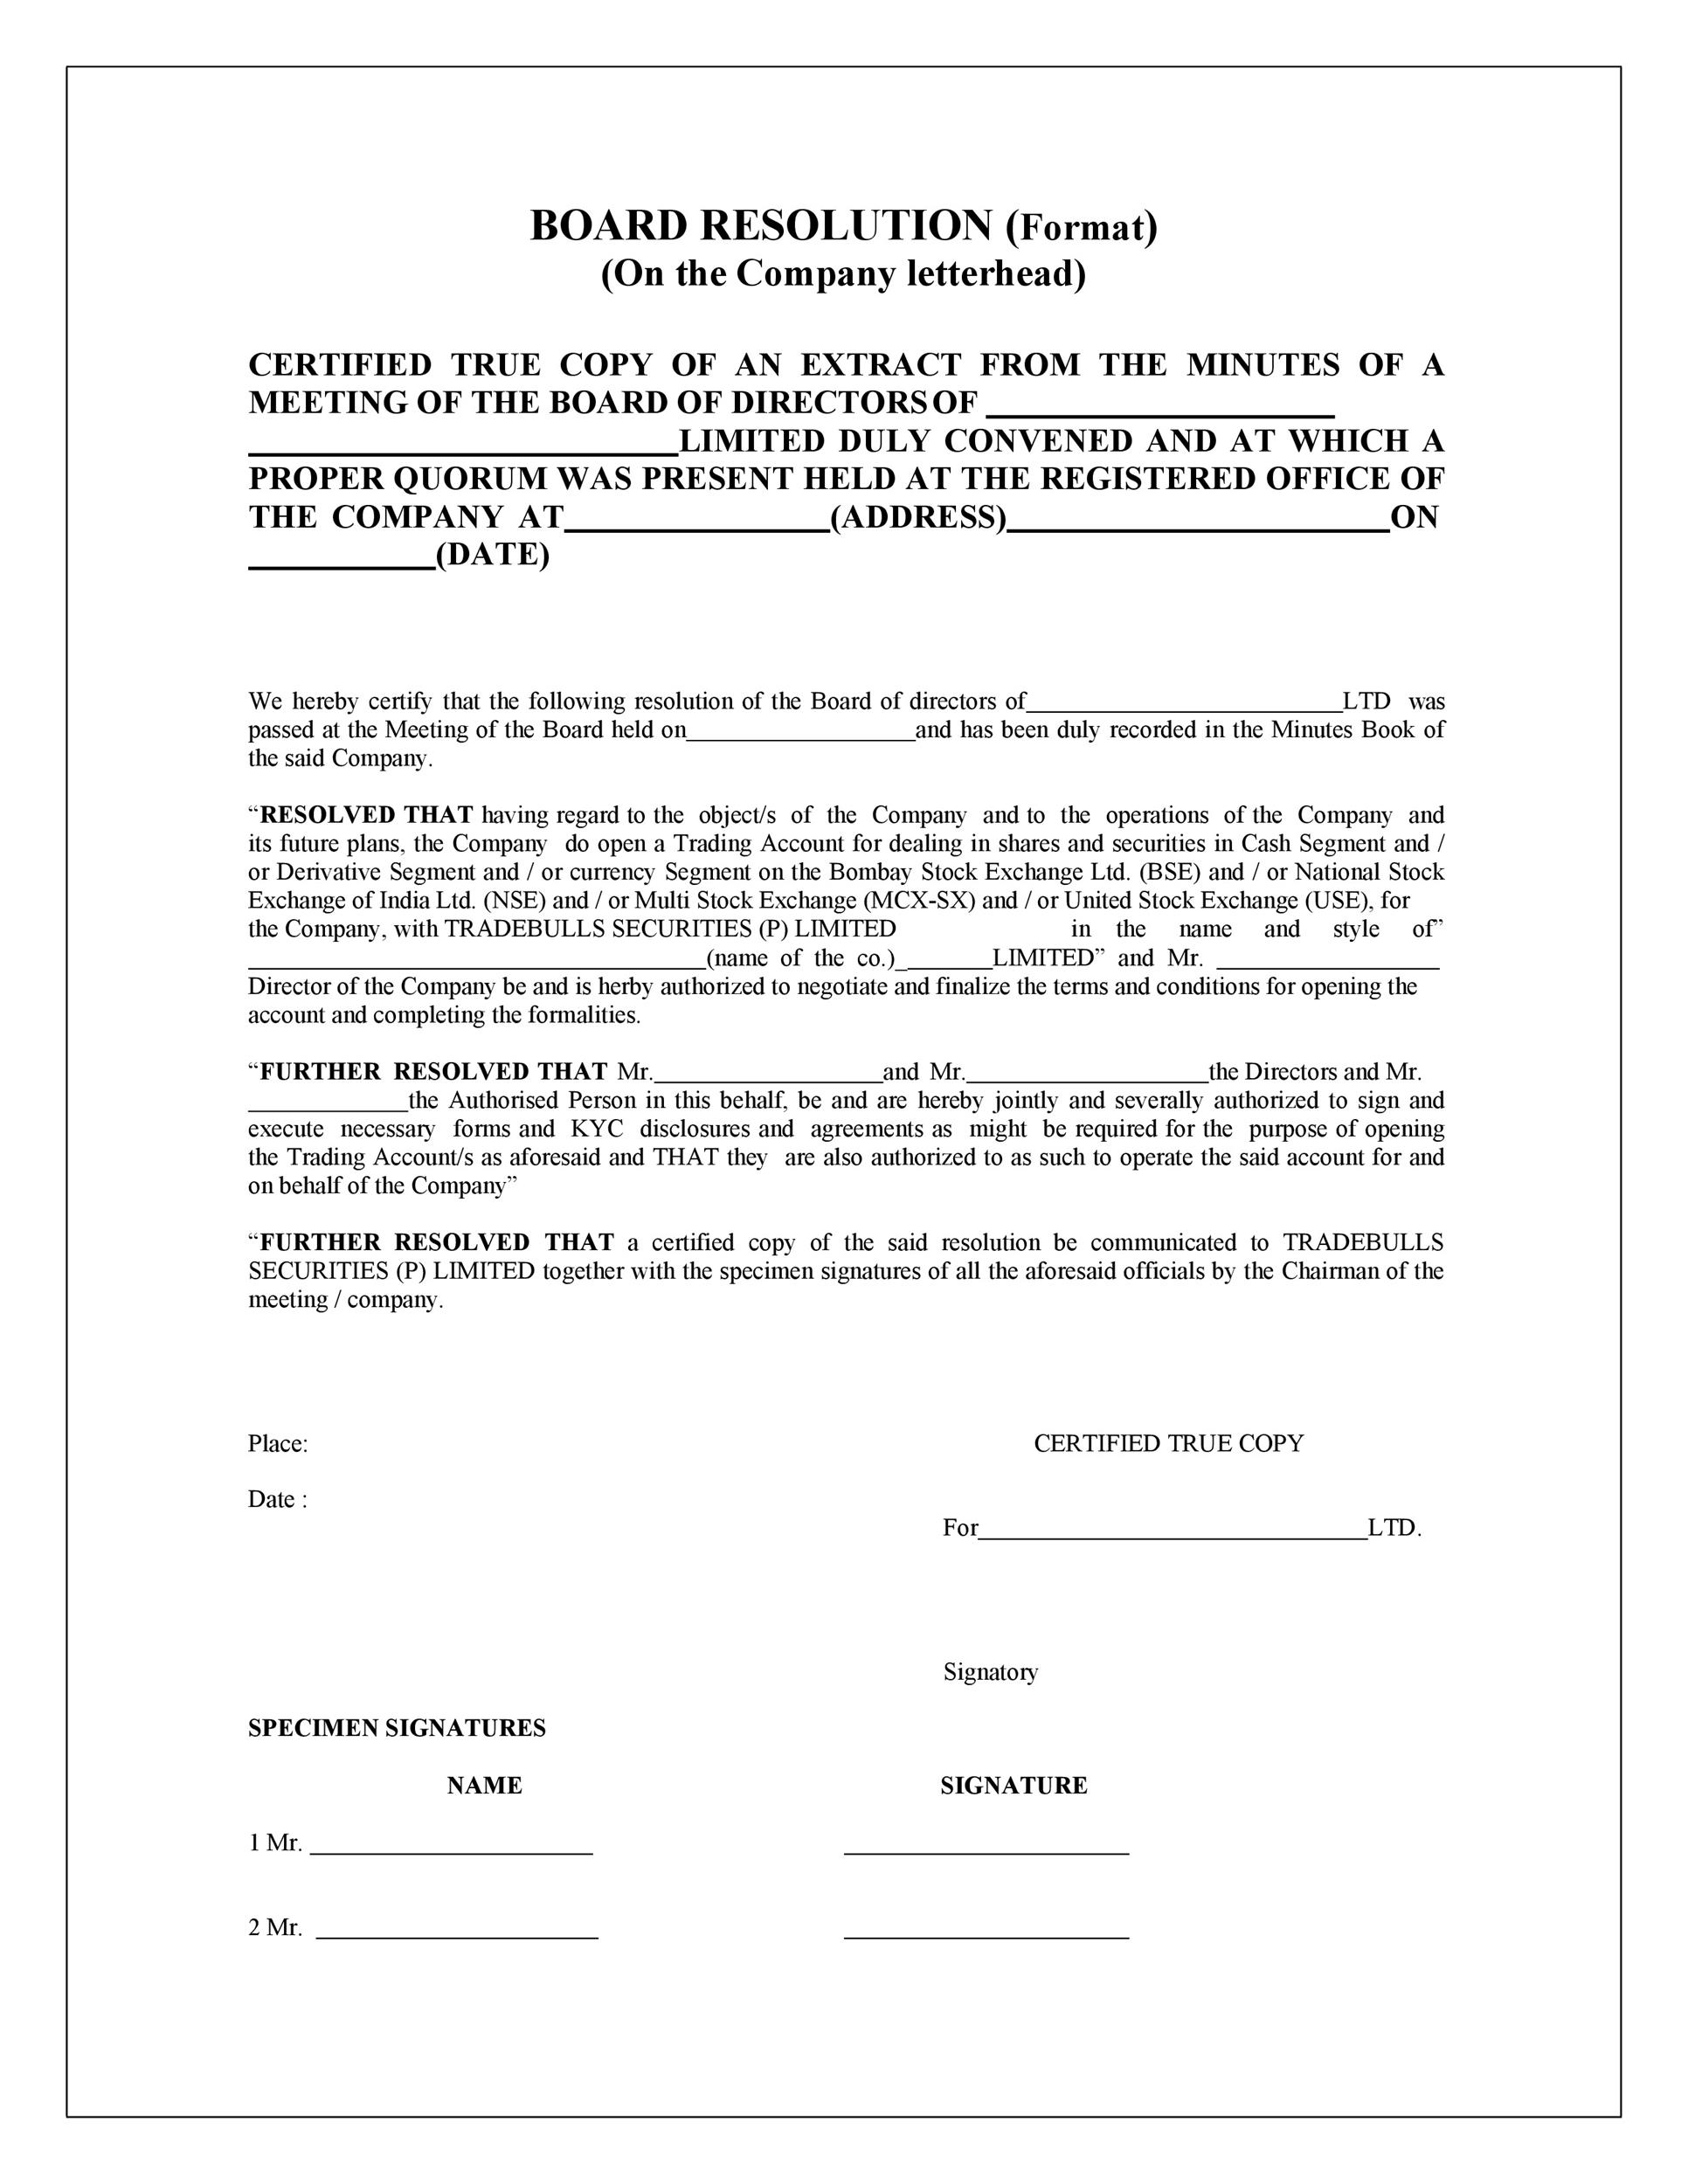
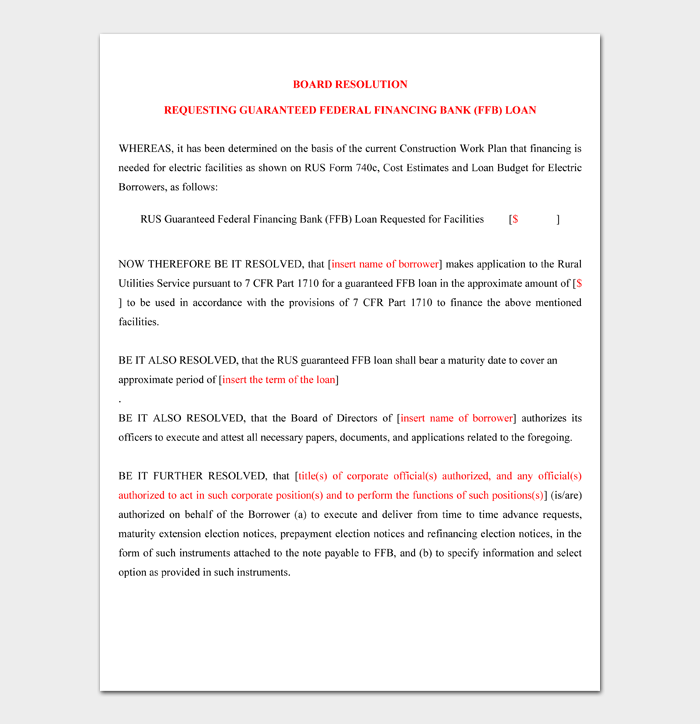
When a company's board of directors sets up or changes a retirement plan, they have to document the decision properly. That documentation takes the form of a board resolution. If you're using American Funds as the investment provider or custodian for that plan, there are a few things you need to know about how that process works, what American Funds typically requires, and where people usually trip up. A board resolution is essentially a formal record that the company's governing body agreed to take a specific action. For retirement plans, this usually covers adopting the plan, selecting or changing the investment provider, authorizing contributions, or amending plan terms. American Funds, through their administrative partners and plan service divisions, expects to receive a copy of this resolution before they'll process certain account changes. The resolution needs to include specific elements. It has to state the date of the meeting where the decision was made, list the attendees who voted, clearly describe the action being authorized, and be signed by the corporate secretary or an authorized officer. Without those pieces, the paperwork gets rejected and you're back to square one.
Here's the thing most people miss: American Funds doesn't just accept any resolution template. They have their own formatting expectations depending on the type of account. A retirement plan resolution for a corporate 401(k) looks different from one for a simplified employee pension, which looks different from a self-directed IRA. Using the wrong template is one of the most common reasons submissions get sent back. I've seen this repeatedly when working with mid-market employers who try to reuse old resolutions without checking whether the current document meets the specific requirements for the account type they're opening. The practical workflow usually goes like this. Your corporate secretary drafts the resolution based on the board meeting minutes. You send it to the plan administrator or American Funds representative for a preliminary review before the formal submission. They'll flag any missing signatures, unclear language, or formatting issues. Then the officially executed copy goes into the file. This preliminary review step alone saves most groups two or three rounds of back-and-forth that would otherwise add days or even weeks to account setup. One edge case that causes real headaches involves boards that pass resolutions via written consent instead of an actual meeting. American Funds accepts these, but the documentation requirements are slightly different. You need every single director to sign the consent, not just a majority. I learned this the hard way with a client who assumed a simple majority was sufficient because that's how their corporate bylaws work for regular decisions. The resolution came back rejected because one director hadn't signed the written consent, and tracking down that person took three weeks because they were traveling internationally with poor connectivity. Now I always check whether all directors have executed written consents before anything goes out for submission.
Another thing that catches people off guard is the timing. American Funds and their partner administrators often require the board resolution to be dated on or after a specific reference date, particularly when the resolution is authorizing changes to an existing plan. If the board meets in January to amend the investment lineup but dates the resolution for the prior December, some submission pathways will reject it as retroactive. The fix is straightforward — date the resolution for the actual meeting date — but the rejection itself creates unnecessary delay and confusion. There's also the question of plan document amendments versus operational resolutions. These are not the same thing. A plan document amendment changes the legal terms of the plan and requires its own separate documentation, usually prepared by your plan advisor or ERISA attorney. A board resolution addresses the governance decision to make that change. Both are needed, but they serve different purposes and get reviewed differently. Mixing them up or submitting one in place of the other is a frequent error that stalls processing. For smaller companies without a dedicated corporate secretary, the resolution drafting often falls to the business owner or office manager. That's workable, but it helps to get the resolution reviewed by someone familiar with ERISA requirements before it goes to the board for signature. A resolution that looks correct on the surface can still have problems — like failing to properly authorize the specific types of investments being selected, or using language that doesn't align with the plan's actual terms. American Funds will catch some of these issues during their review, but catching them earlier is considerably less expensive than re-doing everything after a rejection.
Get the Full Details
The biggest limitation to keep in mind is that Board Resolution Guidelines American Funds Retirement processes vary depending on which American Funds entity you're dealing with and which third-party administrator is handling the plan records. There isn't a single universal form. Some plans go through Capital Group directly, others through intermediaries like Unum, Alight, or Human Interest. Each may have slightly different requirements for how the resolution should be formatted, what supporting documents need to accompany it, and how long processing takes. Before you spend time drafting anything, confirm with your specific service provider which version of the guidelines applies to your account. If your situation involves a complex plan structure — multiple employer contributions, profit-sharing arrangements, or recent plan mergers — the resolution requirements become more detailed. In those cases, relying solely on a generic template is risky. Working with a plan advisor who has experience with American Funds retirement products tends to save more time than trying to figure it out independently, even though it costs upfront.