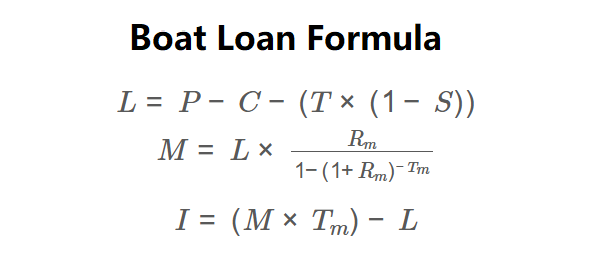Figuring Out Your Monthly Payment Without a Dealer Lying to You
A Boat Loan Calc is just a tool that takes your loan amount, interest rate, and term length and spits out a monthly payment. The math behind it is straightforward, but the way people mess it up is where things get interesting. I've sat across from enough finance managers at marinas to know most borrowers have no idea what they're actually signing. The standard amortization formula is M = P[r(1+r)^n]/[(1+r)^n-1], where P is principal, r is your monthly interest rate, and n is total number of payments. You don't need to memorize it. Most calculators online handle it in about 0.3 seconds. What matters is feeding it the right numbers. Here's the part people always get wrong: the interest rate. Lenders advertise annual percentage rates. Your calculator needs the monthly rate, which means dividing the APR by 12. If someone quotes you 7.2% annual and you plug that in as 7.2 into the monthly field, your payment will be completely wrong. Divide by 12 first. It gives you 0.6% per month. Simple, but I've seen it trip up experienced people.
Let me walk through an example. Say you're financing a $45,000 sailboat over 120 months at 6.8% APR. Monthly rate is 0.00567. Your payment comes out to roughly $527 per month. Not bad for a boat that'll depreciate faster than a new car. The total interest paid over that term? About $18,200. That's nearly half the boat's price going to the bank. Keep that number in mind when you're negotiating.
What Online Calculators Miss
Most free Boat Loan Calc tools online only show the principal and interest. They don't account for taxes, registration fees, dockage deposits, or the dealer prep charges that get rolled into the financed amount. If you're looking at a $50,000 sticker price, your actual loan might be closer to $53,000 once everything gets tacked on. Run the calculator with the real number, not the advertised one. I ran into this exact problem last year while helping a friend compare offers from three different lenders. The monthly payments looked nearly identical on paper, but one lender had rolled a $1,200 documentation fee into the principal without mentioning it upfront. The effective interest rate on that loan was actually 7.4%, not the 6.9% they quoted. You catch that by calculating the true monthly rate from the payment amount and working backward, not by trusting the APR figure they hand you.
Get the Full Details
When the Calculator Fails You
There are scenarios where a standard amortization model gives misleading results. Balloon payments are the biggest one. Some marine lenders offer lower monthly payments by pushing a large lump sum to the end of the term. A Boat Loan Calc set up for a standard amortizing loan won't show you the balloon amount unless you adjust the parameters. If you're looking at a 5-year loan with a balloon, treat it as two separate calculations: the monthly payments for the amortized portion and the remaining balance that hits you at maturity. Another edge case is prepayment penalties. Some boat loans charge a fee if you pay off the loan early, usually calculated as 2% of the remaining balance in the first year, declining each year after. The monthly payment might look attractive, but if you plan to refinance or sell the boat within 18 months, that penalty eats into whatever savings you thought you were getting. I had a client who took a 5.9% rate loan to buy a used trawler, sold it after 14 months, and paid $2,800 in prepayment penalties that effectively pushed her annualized cost to 8.1%. She never would have taken that loan if she'd modeled the exit scenario first.
Where to Get a Reliable Calculator
You don't need to build one from scratch. Several solid options exist. BoatUS offers a free calculator on their website that handles standard amortization and allows you to add taxes and fees. MyBoatLoan.net has a decent tool too, though the interface is a bit dated. If you want something you can run locally without ads or sign-ups, I've found that a simple spreadsheet with the PMT function in Excel or Google Sheets works perfectly. The formula is =PMT(rate/12, months, -loan_amount). Copy it into any cell and adjust the inputs. Takes about 15 seconds to set up and never breaks. One thing to watch for with downloadable tools: some older Excel-based Boat Loan Calc files use the wrong compounding assumption. Marine loans typically compound monthly, but a few spreadsheads I've seen assume annual compounding, which throws the payment off by $10 to $30 per month depending on the term. Always verify by comparing the output against an online calculator before trusting the file for serious decisions.
Practical Tips That Actually Matter
The biggest lever you have is the down payment. Throwing an extra 10% upfront on a $60,000 boat cuts your principal to $54,000 and reduces total interest by roughly $5,400 over a 120-month term at current rates. That's not a theoretical saving. It's what the numbers show. The down payment also drops you into a better risk tier with some lenders, which can improve your rate by half a point or more on boats over $50,000. Term length is the second lever, and it's where most people make the worst trade. Extending from 84 months to 120 months might drop your payment by $40, but it adds roughly $4,200 in interest. The payment feels easier month to month, but you're paying significantly more for the privilege. If your budget is tight, consider whether you can afford a larger payment for a shorter term instead. The interest savings usually outweigh the monthly strain, especially if you plan to sell the boat before the loan is paid off. Don't skip the comparison shopping step. I've seen the same boat financed at rates ranging from 5.4% to 9.2% depending on the lender, the borrower's credit profile, and whether the deal was arranged through the dealer or directly with a credit union. Credit unions typically offer the lowest rates for marine loans, but not all of them lend on boats over a certain age. A 2008 vessel might qualify at Navy Federal but get declined by regional banks that cap loans at 15 years old. Check the lender's boat age policy before you start crunching numbers.

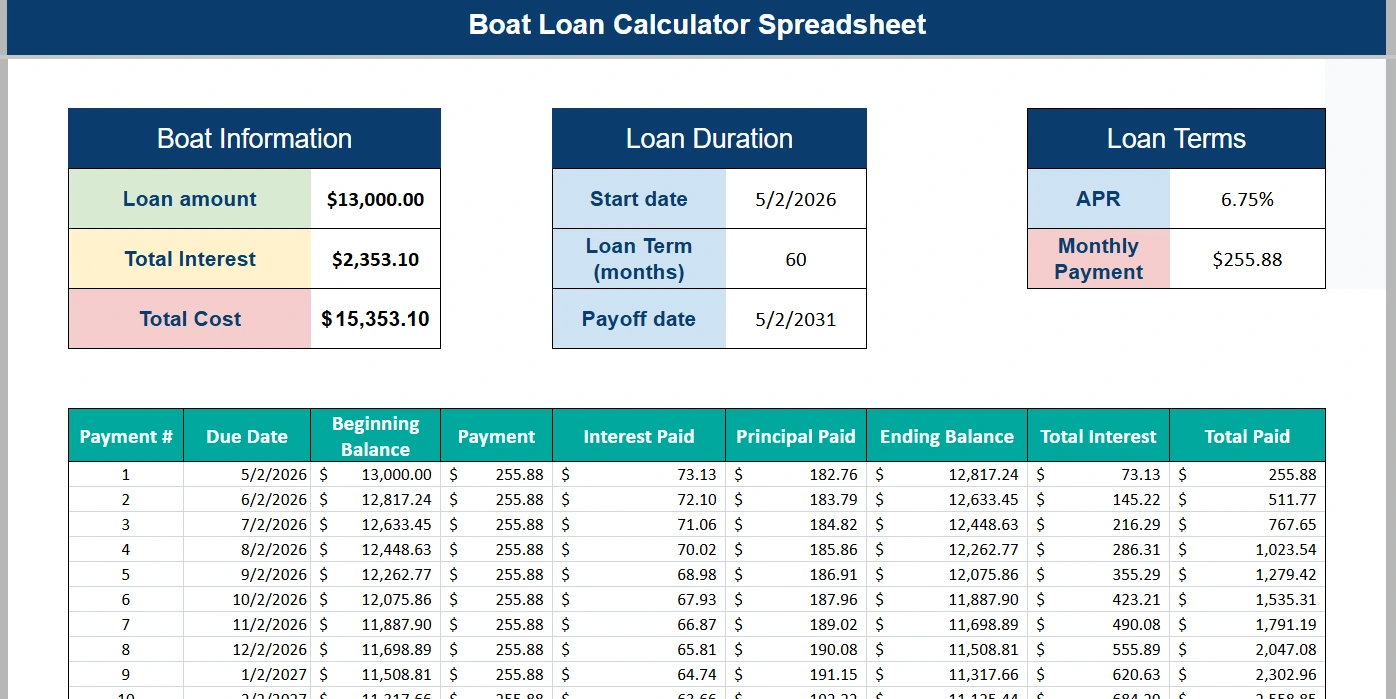
If you're working with a Boat Loan Calc and the numbers still don't seem to line up with what the lender quoted, ask for an amortization schedule in writing. A legitimate lender will provide one. It shows exactly how much goes to principal versus interest each month and reveals any hidden fees baked into the payment. If they won't or can't, that's a signal to walk away and look elsewhere.