Most people get tripped up when they first try to work through bond type problems because the formulas look simple but the application varies depending on what you are actually solving for. I spent a few years grading introductory finance exams and the patterns of mistakes were pretty consistent across semesters.
The core issue is that students try to memorize three separate formulas for present value, future value, and yield to maturity instead of understanding that they are all just variations of the same cash flow discounting principle. Once you see it that way, the whole thing becomes much less intimidating.
Bond Type Practice Answer Key Fundamentals
When I put together practice problems, I usually start with a straight bond with annual coupon payments, then gradually introduce semiannual compounding and callable features. The answer key needs to show each step clearly because that is where the real learning happens.
A typical problem might ask you to price a 10-year, 6% coupon bond with a face value of $1,000 when the market yield is 5%. The formula is straightforward: you discount each coupon payment and the final principal repayment back to the present value. I use $50 annual payments in my examples because the numbers work cleanly without calculator anxiety.
The tricky part that catches most students is when the bond pays semiannually. You have to adjust both the coupon payment and the number of periods. That 6% bond actually pays $30 every six months, and you have 20 periods instead of 10, using a 2.5% periodic rate. This adjustment is where answer keys tend to gloss over the detail, but it is critical for accuracy.
I recall one student who lost points because she used the annual rate for semiannual periods without adjusting anything. She got a price of about $1,040 instead of the correct $1,043.87. The difference looks small but it compounds when you are working with larger portfolios or longer time horizons. I made sure to note this specific error pattern in my feedback for two straight years because it kept showing up.
Working Through Yield to Maturity Calculations
Finding the yield to maturity is essentially solving for the interest rate in the bond pricing equation. This usually requires iterative methods or a financial calculator because there is no algebraic solution. Some textbooks try to approximate with interpolation, but that approach can introduce errors of 10 to 20 basis points depending on the bond characteristics.
I prefer teaching the trial and error method with linear interpolation as a backup. You pick two rates, calculate the bond prices at each rate, and then interpolate between them. It is slower than hitting a single key on a financial calculator, but it builds actual intuition about how price and yield move inversely.
The answer key should show multiple decimal places for intermediate calculations even though the final answer might round to two decimals. Students who only show two decimals throughout often arrive at slightly wrong answers because rounding compounds at each step. This is another common pitfall I noticed repeatedly.
Calling Features and Their Impact on Pricing
Callable bonds add a layer of complexity that many introductory courses handle too quickly. The issuer can redeem the bond before maturity at a specified call price, which creates uncertainty about the actual cash flows. When calculating yield, you need to determine whether the bond will trade at a yield to call or yield to maturity, depending on the interest rate environment.
I include a specific edge case in my practice sets where the call price is higher than par value but the bond is trading below par. This creates a situation where the yield to call is actually lower than the yield to maturity, which seems backwards until you work through the cash flow analysis. Most students expect the call yield to always be higher because of the call premium, but that assumption fails in certain market conditions.
The workaround I teach is to calculate both yields and then compare them. If the bond is trading below par and rates are falling, the issuer is likely to call it, so the yield to call becomes the more relevant metric. If rates are rising, the bond probably won't be called, making the yield to maturity the better estimate. This dual calculation takes about five minutes per bond once you get the hang of it.
Practical Application and Common Mistakes
Bond valuation problems on exams often include distractor information that is not needed for the solution. I sometimes add details about the bond rating or the industry sector to see if students understand that credit quality does not change the mathematical pricing relationship. The price still depends on the promised cash flows and the appropriate discount rate, regardless of whether the bond is rated AAA or BB.
Another common issue is confusing current yield with yield to maturity. Current yield is simply the annual coupon divided by the current price, which ignores both capital gains and losses from buying at a premium or discount. A bond purchased at $900 with a $60 coupon has a current yield of 6.67% but a yield to maturity closer to 7.2% because of the $100 gain at maturity. This distinction matters when comparing investment opportunities.
I also see students forget to account for accrued interest when calculating the full bond price. The clean price is what you get from the pricing formula, but the actual amount paid includes interest that has accumulated since the last coupon payment. This is standard practice in the bond market and understanding it helps with real-world applications beyond exam settings.
Building Your Own Practice Sets
If you want to create additional practice problems, start with a spreadsheet model that calculates bond prices across a range of yields. This lets you generate consistent problem sets with known answers. I usually vary the coupon rates from 0% to 10% and the yields from 1% to 15% to cover different market scenarios.
Including zero-coupon bonds in your practice set is useful because they represent the simplest case mathematically. With no interim payments, the price is just the face value discounted back the appropriate number of periods. This clarity helps students verify that their formulas are working correctly before adding coupon payments to the mix.
The answer key format should show the formula setup, the substituted values, and the final result with appropriate units. I include brief notes about why certain steps matter because that context helps with long-term retention. Students who understand the reasoning behind each calculation step perform better on comprehensive exams that combine multiple bond concepts.
For downloadable practice materials, I typically organize problems by topic: basic pricing, yield calculations, callable bonds, and then mixed review sets. Each section builds on the previous one, and the answer keys are separated into a different document so you can test yourself without seeing solutions immediately. This spacing effect improves learning outcomes according to educational psychology research, though I discovered that through experience rather than coursework.
Gallery Bond Type Practice Answer Key
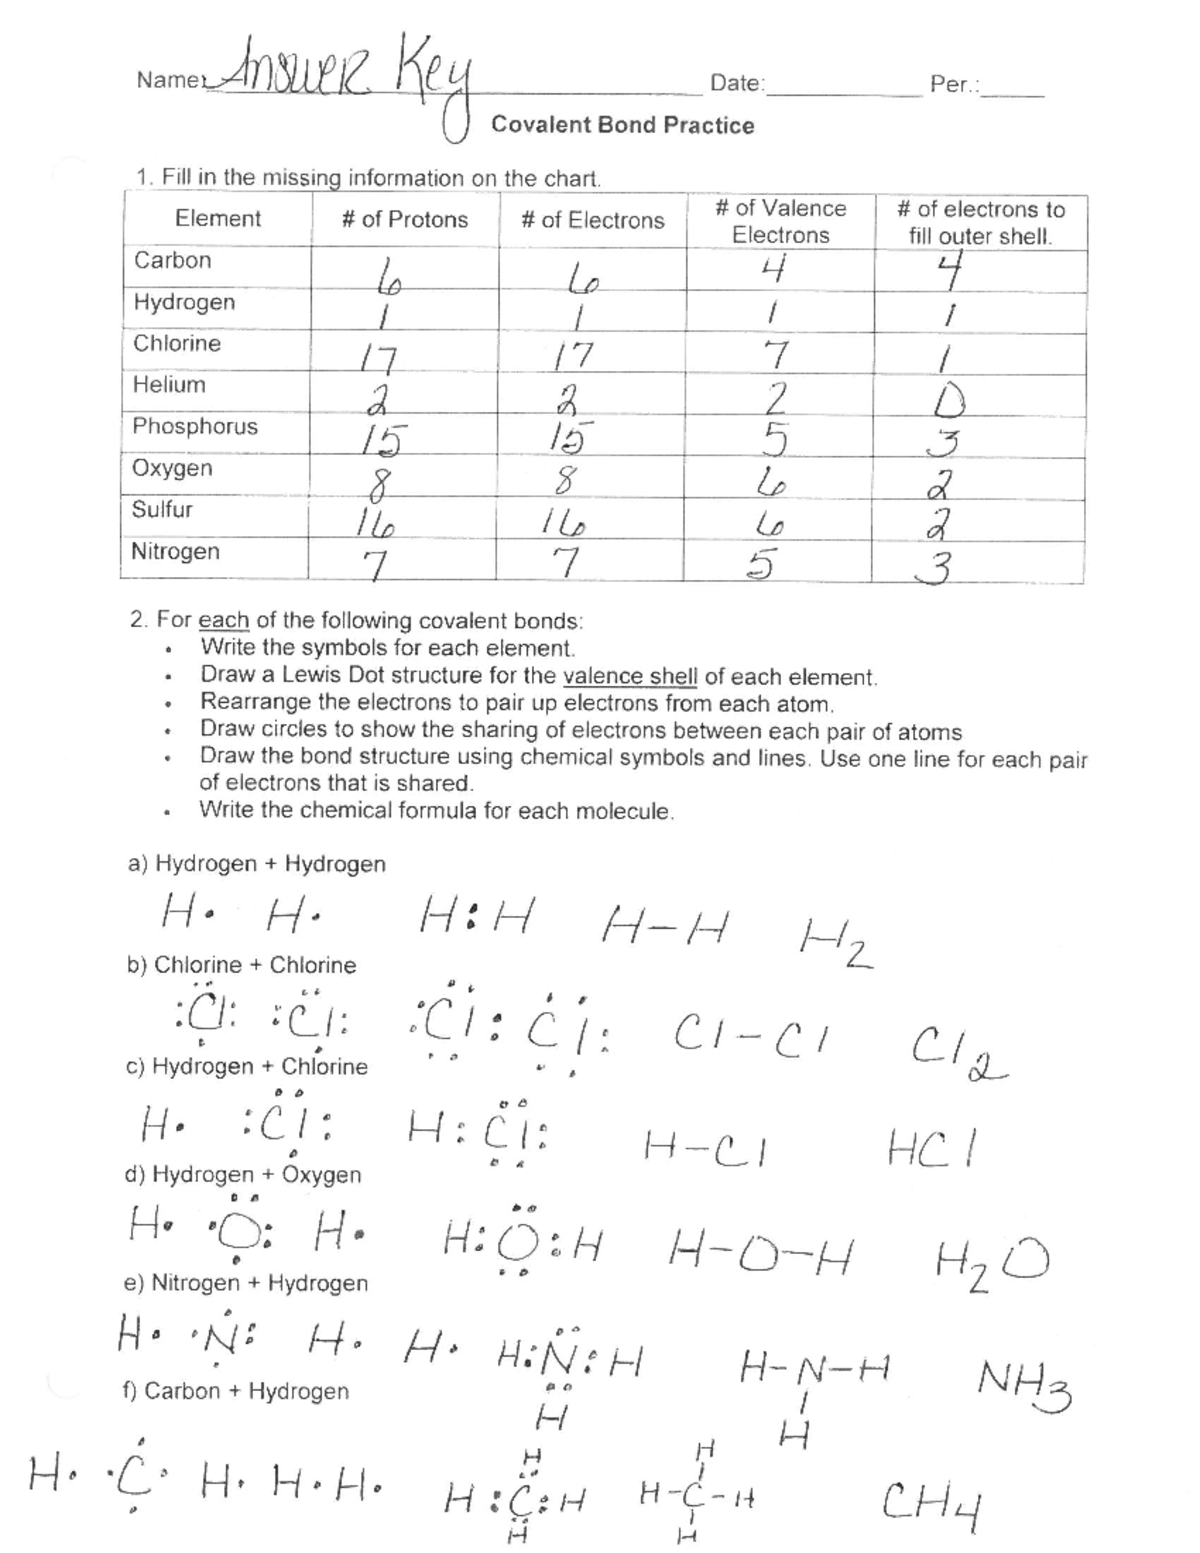
Covalent Bond Practice - Answer Key for Chemistry 101 - Studocu
9th Grade Science | Bond Types Worksheet (PDF+ Answer Key) by Ms. Emily Hayes
Types Of Chemical Bonds Worksheets Answer Key
Bond Type Practice: Covalent, Ionic, Metallic Bonds
Types Of Bonds Worksheet Answer Key — db-excel.com