Writing a bookstore business plan when you actually intend to open one
A bookstore business plan is just a document that forces you to answer questions you would rather not think about. Most people treat it like a formality for the bank. The ones who ignore the parts that don't look impressive on paper are the ones who run out of cash in month four. I learned this the hard way when I helped a friend near Sacramento put one together. She had a clear vision for a speculative fiction shop with a reading room. Great vision. Terrible numbers. She had not accounted for the fact that her city's main shopping corridor was two miles from the nearest residential neighborhood with a median income above $65,000. That one miss on foot traffic turned her projected monthly revenue into something closer to a donation. The real value of a bookstore business plan is not in the executive summary. It is in the sections you write last and hate the most. I will walk through how to actually build one without making it longer than it needs to be.
How to build a practical Bookstore Business Plan
Start with your location hypothesis. This is the part where most plans fall apart because people describe their ideal store instead of where their ideal customer actually lives. You need a 1-mile radius population count, average household income, and the foot traffic pattern at different times of day. Walk the block yourself. Count people at different hours. Do not rely on city-planning documents from 2018. Next figure out your product mix. A bookstore is not one business. It is five businesses layered on top of each other. Books at wholesale get you roughly a 40 to 50 percent gross margin on new releases. Returns eat half of that back if you order too aggressively. Used books have better margins but take twice as long to stock. Gift items and cards can push your overall margin up by 8 to 12 percentage points if you do them well. Coffee is either a disaster or a genuine profit center depending entirely on whether you have the right equipment and someone who knows how to run it. These are not suggestions. They are the arithmetic most independent bookstores miss until it is too late. Then lay out your costs. Rent will kill you if you sign a five-year lease without an escalator cap. I once saw a bookstore in Portland sign a deal with a 3 percent annual increase compounded every single year. By year three, the rent was already outpacing their sales growth. Get a cap. Thirty percent is reasonable. Twenty-five percent is aggressive. Anything above thirty-five is a trap.
Your staffing model matters more than people expect. If you are open six days a week and your best employee works forty hours and costs twelve dollars an hour, you need at least three people on a rotating schedule. That is thirty-six to forty-eight hours of labor before you even count overtime, training, or the nights when someone calls out. Factor in payroll taxes. Factor in worker's comp insurance. Factor in the time you spend managing people instead of merchandising shelves.
Get the Full Details

Revenue modeling that does not look like fantasy
Most business plans project revenue based on what the owner hopes to sell. That approach produces numbers you cannot defend to anyone. Use a bottom-up model instead. Calculate your expected transactions per day, multiply by your average transaction value, then multiply by your open days per year. Adjust for seasonality. September through December will look very different from February through April. Do not smooth it out. Special orders and community events are real revenue drivers that get ignored. One local author event with a signed book signing can move between fifty and two hundred copies in a single afternoon. The margin on those is low. The revenue is not. Build a separate line item for events and keep it honest. Three or four well-run events per month is realistic for a small shop. Ten is exceptional. Online sales deserve their own section. Amazon will undercut you on price every single time. Your advantage is curation, community, and same-day pickup. Do not try to compete on shipping speed. Compete on selection and service. The math works if you keep your overhead low enough.
Common pitfalls I see repeatedly
The biggest mistake is underestimating the working capital needed. A bookstore requires inventory upfront. You pay your wholesaler before the books sit on a shelf. You pay rent before customers walk through the door. Six months of operating expenses plus a full initial inventory order is the minimum cushion most lenders accept. Ten months is safer. If you are borrowing against personal assets, ten months is what keeps you from going to sleep every night wondering if the monthly payment will clear. Another mistake is stacking too many product categories too quickly. Adding a small café line, a subscription box program, and an online store in the first year sounds ambitious. In practice it fragments your attention across three operations that each require their own systems, vendors, and staff training. Pick one supplementary revenue stream and get it profitable before adding another. I watched a store in Austin add a podcast studio after a successful café. They could not keep the espresso machine running correctly, let alone produce consistent audio content. They closed eighteen months later. Gross margin confusion is another quiet killer. People see 50 percent margin on books and assume they keep half the dollar. Then they forget about returns, shrinkage, discounting, and the administrative cost of reordering. Net margin for a typical independent bookstore lands somewhere between 2 and 5 percent in a healthy year. If your plan shows 10 percent or higher without extraordinary event revenue or a really low rent deal, something is wrong with your assumptions.
What a solid financial section should include
You need a startup cost table, a monthly cash flow projection for the first two years, and a break-even analysis. The break-even number tells you exactly how many transactions you need per day to cover fixed costs. Write it down. Update it quarterly. If your actual numbers drift from the projection for two consecutive months, revise the plan immediately. Do not wait until the annual review. Include a scenario analysis. Best case, baseline, and worst case. The worst case should reflect a sustained 20 percent drop in foot traffic or a major lease renewal at a higher rate. Lenders want to see that you have thought through what happens when things go sideways. Investors care more about whether you understand your unit economics. Either way, skip it at your peril. One thing nobody tells you about the process: the physical act of writing a detailed Bookstore Business Plan changes how you think about your store. I have watched people discover during the revenue modeling phase that their chosen location cannot support their desired square footage. I have seen others realize that their product mix was fundamentally misaligned with the neighborhood demographics. The document is useful precisely because it forces uncomfortable decisions early.
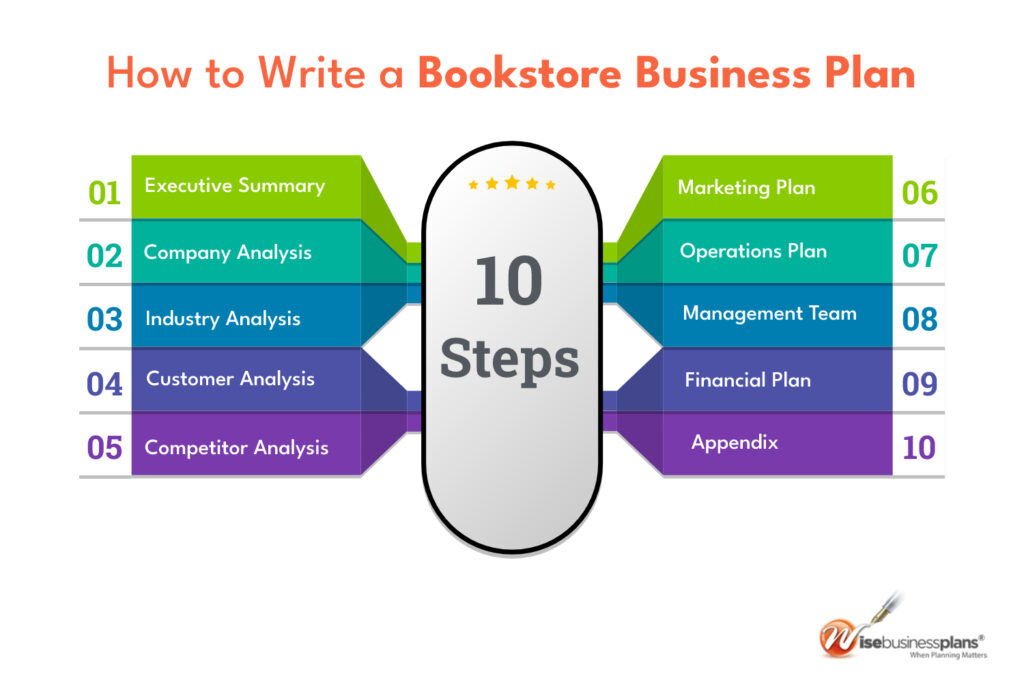
If you want a template to start from, check the Small Business Administration website. The SBA provides free business plan templates that cover the core sections. Industry associations like the American Booksellers Association also have resources. The template is a starting point, not a substitute for the actual work of filling it with numbers that reflect your specific situation. The real question is whether this exercise is worth the time investment. It is, provided you treat it as a living document rather than a one-time submission. Update it monthly during the first year. Review the projections quarterly. Adjust your assumptions when your actual data contradicts them. A bookstore business plan that sits on a shelf after the bank approves your loan is just paperwork. The ones that actually help are the ones you keep in front of you while you run the business.