What Bq In Standard Costing Actually Means
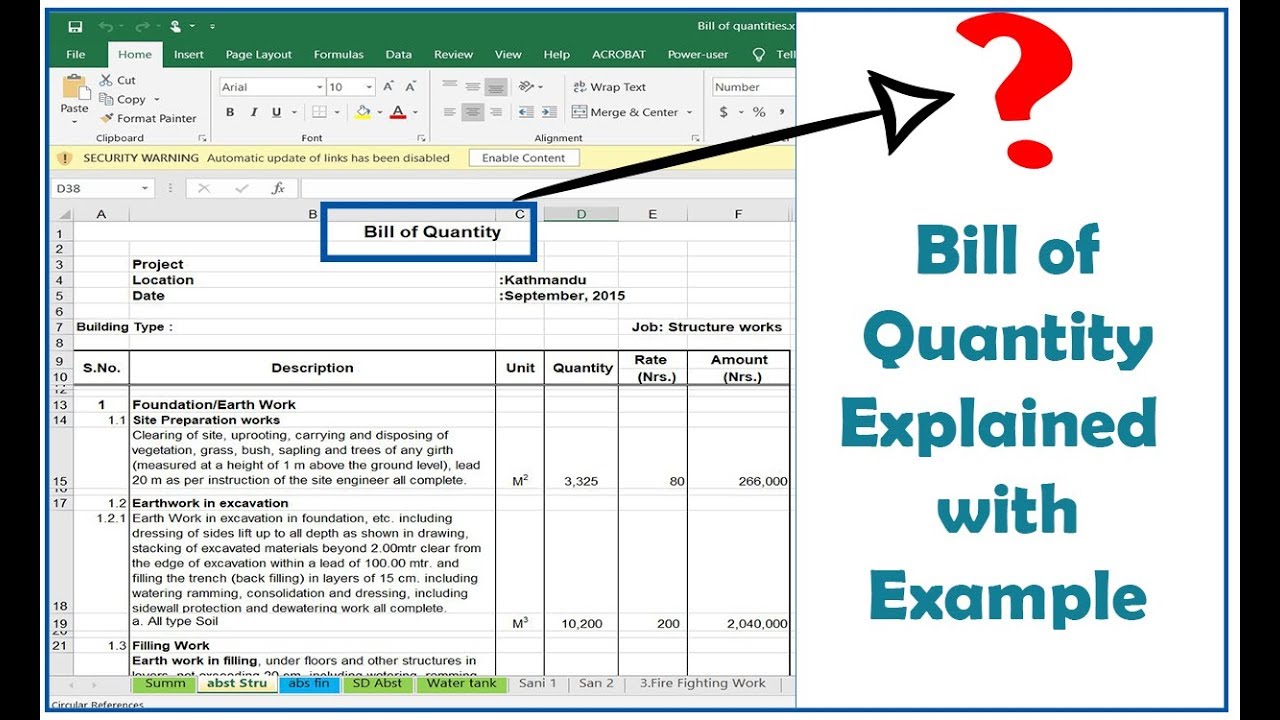
Bq stands for Bill of Quantity, and in standard costing it represents the blueprint of what a product should consume under normal operating conditions. Every raw material, every component, every hour of direct labor gets assigned a standard cost based on engineering studies, historical data, and sometimes just a best-guess from whoever last opened the factory floor. The Bq is then multiplied against those standards to build your total standard cost per unit. That number becomes your benchmark, and variances are measured against it. Here is the practical breakdown. You start with your engineering bill of materials, which lists every input required. For each line item, you pull a standard usage rate, usually based on time studies or historical averages, and multiply by the standard price per unit. The sum across all line items gives you the standard cost. Variance analysis comes later, when actual costs diverge from the Bq baseline. Price variance happens when you pay more or less than the standard rate. Usage variance hits when you consume more or fewer units than specified. I remember one case where a manufacturing client had a Bq issue that basically broke their variance reporting for six months. The problem was a sub-assembly component that had been reformulated three quarters earlier, but the Bq was never updated in the cost system. So every month they were posting favorable material usage variances on paper, even though actual consumption was slowly creeping up. The system was comparing against a ghost standard from 2019. We spent two weeks tracking down every revision notice and rebuilt the Bq from the engineering change orders. Once we did that, the variances snapped into something that actually made sense. My workaround was to cross-reference the ERP Bq against the latest CAD drawings and sign-off sheets, not just trust whatever was sitting in the cost module. Systems are only as current as the last person who bothered to update them.
The Counter-Intuitive Stuff Nobody Tells You
Most people treat Bq in standard costing like a static document. It is not. The biggest pitfall is assuming that one approved Bq covers the entire fiscal year. Real operations have seasonal variations, supplier switches, and process tweaks that quietly change the bill of quantity over time. If your Bq does not reflect those shifts, your standard costs become fiction, and your management reports will be misleading without anyone noticing why. Another thing that trips people up is the treatment of waste and scrap. A proper Bq should include normal spoilage as a separate line item with its own standard yield percentage. What I see far too often is waste getting buried in the main material line, which inflates the per-unit cost and makes your yield variances unreadable. When waste is hidden, you can never tell if a usage variance came from production inefficiency or from a raw material quality problem. Split them out and suddenly your variance analysis actually guides decisions instead of just generating numbers for a spreadsheet.
When Bq In Standard Costing Breaks Down
There are scenarios where this whole approach stops being useful. Custom or low-volume manufacturing is the first one. If you are making one-off pieces or running batches of ten where the bill of quantities changes per order, standard costing with a fixed Bq becomes a exercise in guesswork. The overhead absorption gets distorted, and the variances are so large they tell you nothing useful. In those environments, job costing or throughput accounting tends to give you better signal for the effort involved. Highly volatile commodity markets are another failure case. If your raw material prices swing more than twenty percent quarter to quarter, locking in a standard price in the Bq means your price variances will look catastrophic every single month. You are not running inefficiently; the market moved. Some companies switch to a rolling average standard that updates monthly under those conditions, but even that is a compromise. The variance becomes less about operational performance and more about purchasing timing, which makes it harder to hold anyone accountable. If you are working in an environment where the product design changes frequently, the administrative burden of keeping the Bq current can actually consume more time than the costing system saves. I have seen small-to-medium shops where the controller spent nearly a full day every month chasing down engineering change notices and re-keying standards. That is a dead investment of labor. In those cases, moving to a period-based standard review cycle, maybe quarterly instead of monthly, often lands in a better place. You accept a little lag in accuracy and gain back a day of productive work.
Get the Full Details
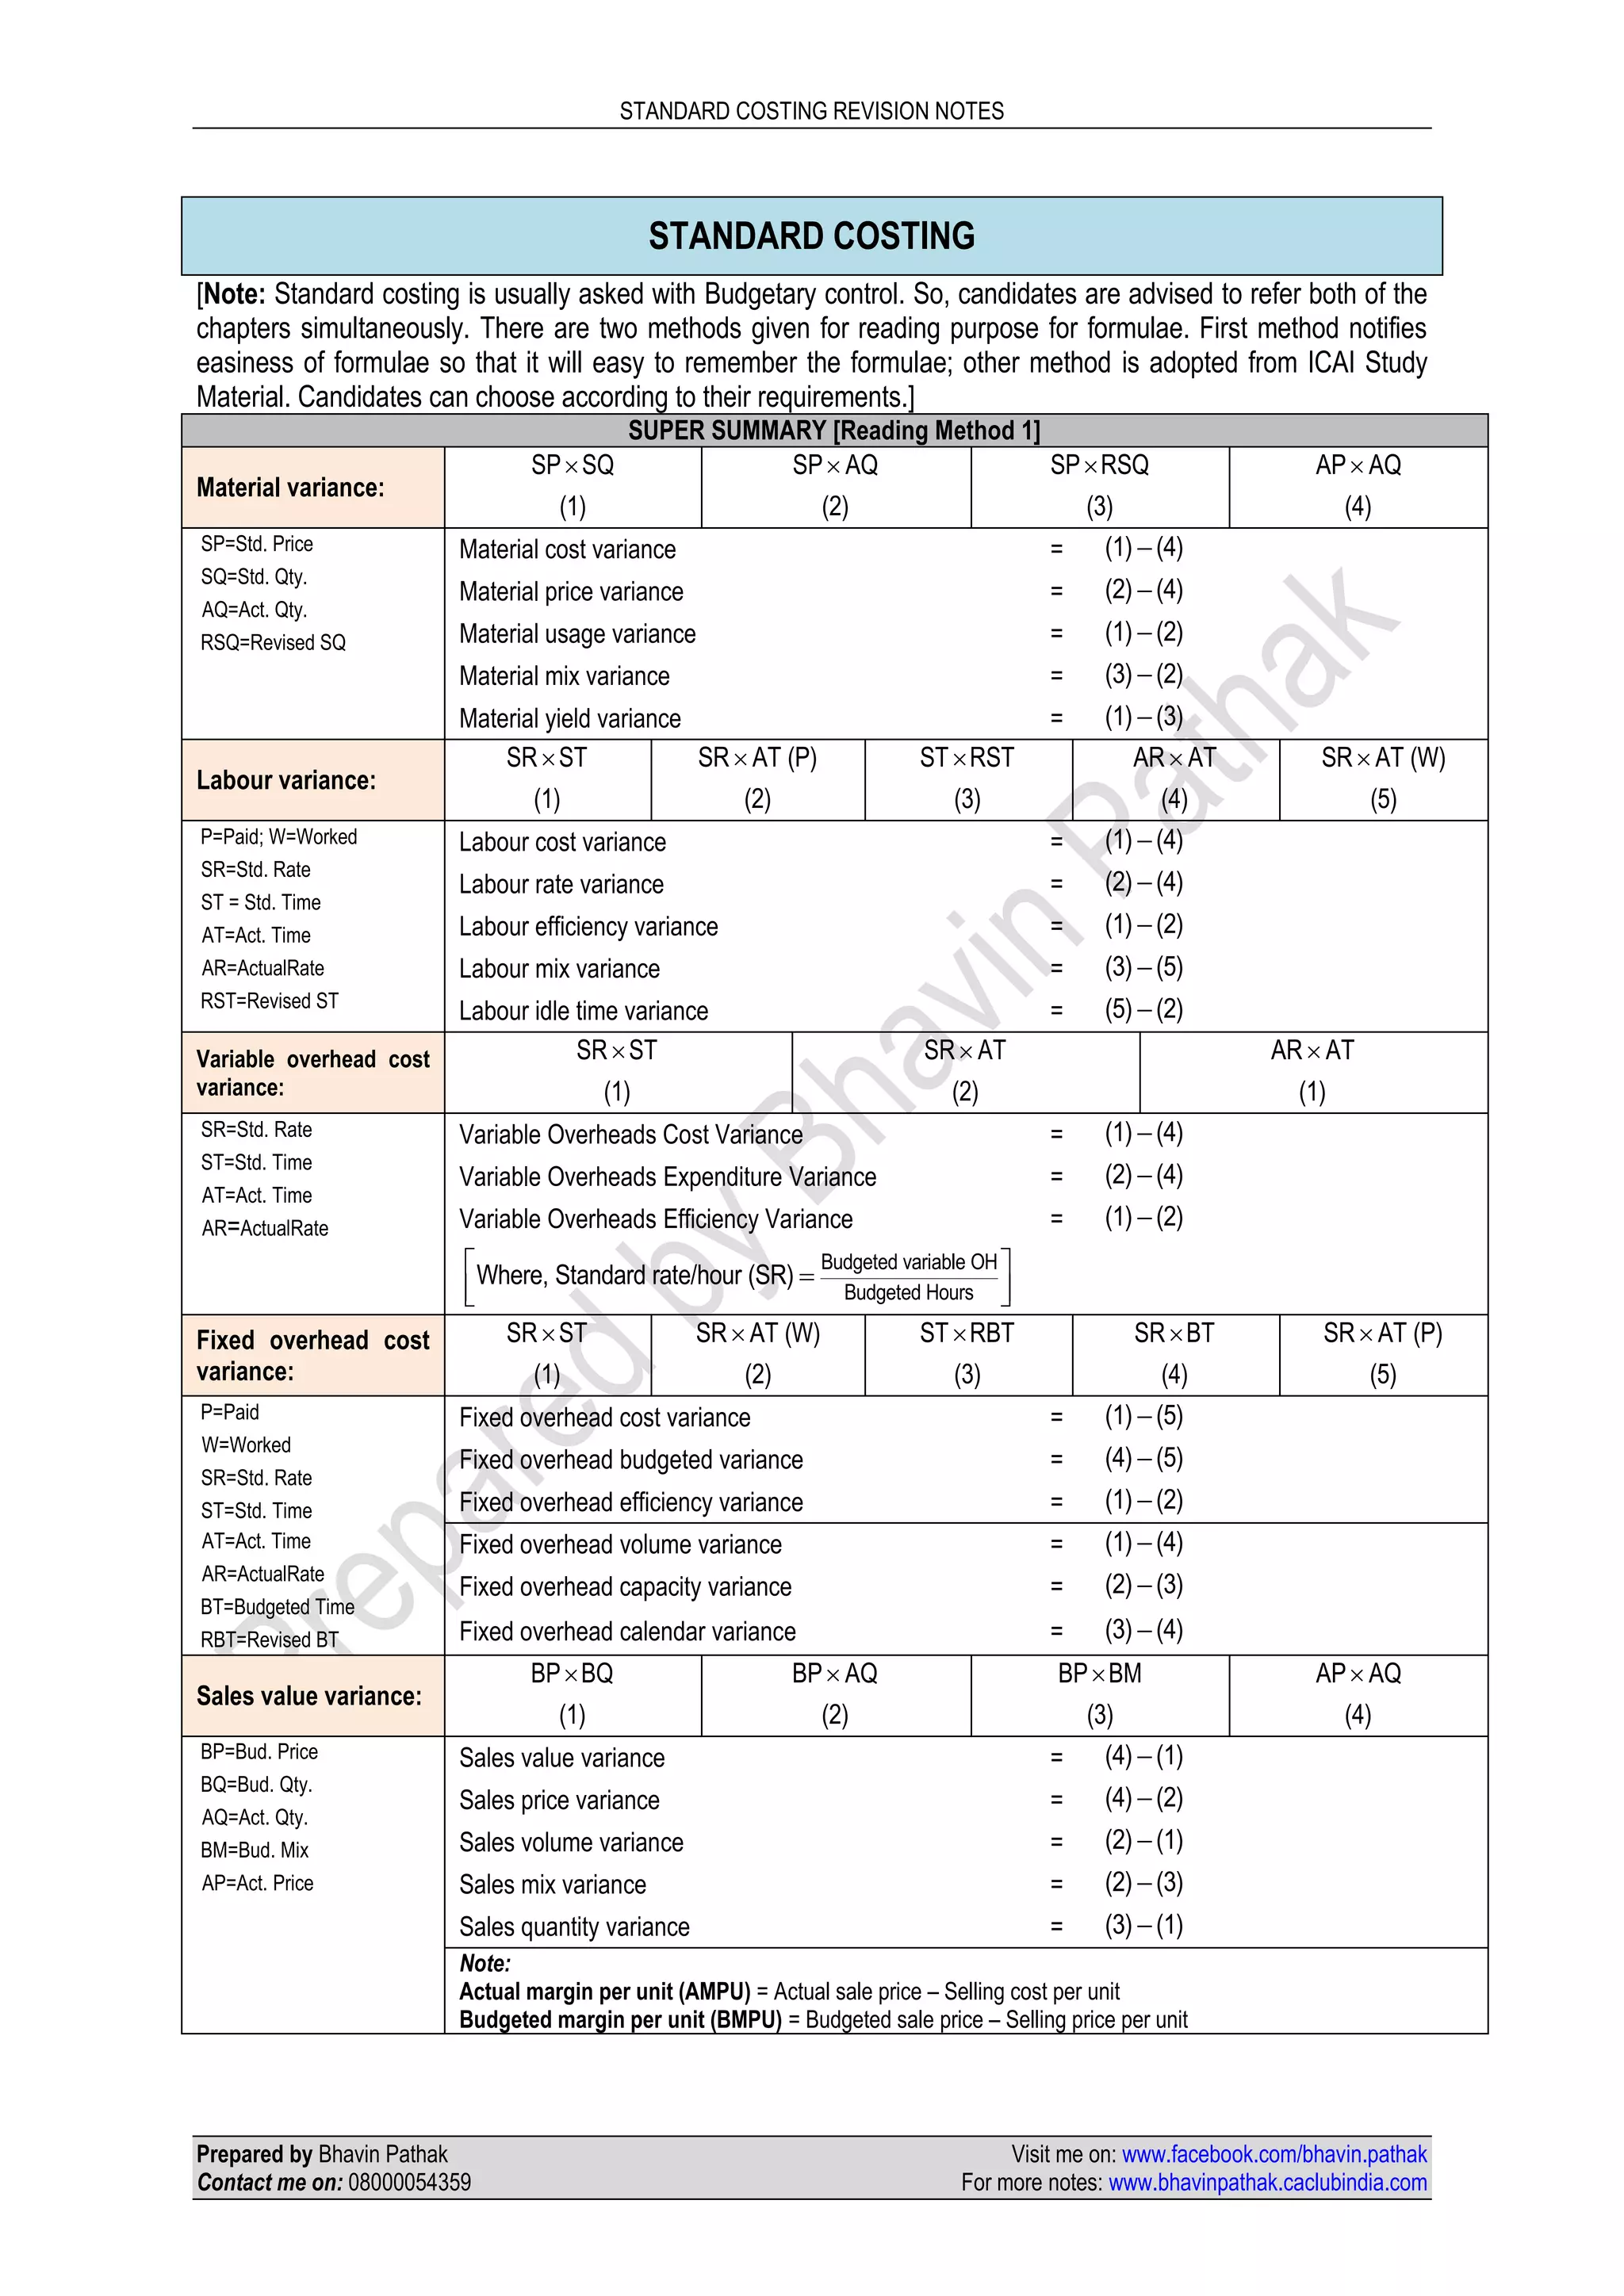
A Practical Path Through It
Start with whatever Bq your engineering or product team maintains today. Do not trust it. Pull the version dates and compare them against your last production run. Look for any design changes, supplier changes, or process improvements that happened after the Bq was approved. Cross-reference those against your ERP records. If you find a gap, document it. Then decide whether to update immediately or flag it for the next standard review cycle. Separate your normal waste from your base material lines. Give each a yield percentage. This alone will clean up your variance reporting faster than most other changes you could make. Run a test comparison between your old blended method and the split method on last quarter's data. The difference in how the variances look will probably surprise you. Set a rule for how often the Bq gets reviewed. Once a quarter is common, but if your product line is stable, semi-annually might be fine. The key is having a schedule instead of waiting for someone to remember to do it. When variances start looking weird, the first place to check should always be the Bq, not the actual cost data. More often than not, the standard is stale and the operations team is doing exactly what they should be doing.