Why Brazil's Economic History Still Messes With Macro Analysts
I spent years working on Latin American sovereign spreads and Brazil was always the headache. Not because the data is missing, but because it tells contradictory stories depending on which decade you zoom in on. If you are trying to understand Brazils Economic History without understanding the inflation scars of the 1980s, you are going to misread every policy move that came after. Brazil did not have a normal economic trajectory. It was a commodity exporter under Portuguese rule, then accidentally became a coffee oligarchy, then threw a full-blown import substitution industrialization push in the 1930s that locked the country into state-heavy manufacturing for decades. The military dictatorship from 1964 to 1985 oversaw what they called the Brazilian Miracle, where GDP grew at double-digit rates, but the spending was financed with external debt that blew up the moment interest rates moved against them in the early 1980s. That is when the real damage started.
Understanding Brazils Economic History Requires First Understanding the Inflation Trauma
Most people outside Latin America treat hyperinflation as a theoretical concept. Brazil lived through it for fifteen years straight. Annual inflation hit 2,900 percent in 1990. Prices changed within hours. Workers demanded salary adjustments twice a month because waiting meant losing purchasing power. This is not something you recover from with a single interest rate decision. The government tried indexation. They tied everything to a fake unit called the URV before finally launching the Real Plan in 1994. Currency board tactics, fiscal adjustment, and a new currency called the real. Inflation dropped from four digits to single digits almost overnight. It worked long enough for Brazil to stabilize, but the structural problems never got fixed. Fiscal dominance returned within five years and the real got hammered repeatedly. Here is the thing nobody tells beginners: the central bank of Brazil, BCB, is genuinely independent now on paper. The legal framework looks solid. But in practice, when the government needs to roll over debt and the fiscal gap is massive, political pressure sneaks in through the back door. I watched this happen in 2020 and again in 2022. The BCB raised rates, then the finance ministry issued bonds that quietly crowded out the transmission mechanism. You can read the legal mandate all day, but the actual rate path is a negotiation between the central bank governor and the Treasury secretary, and it shows in the yield curve.
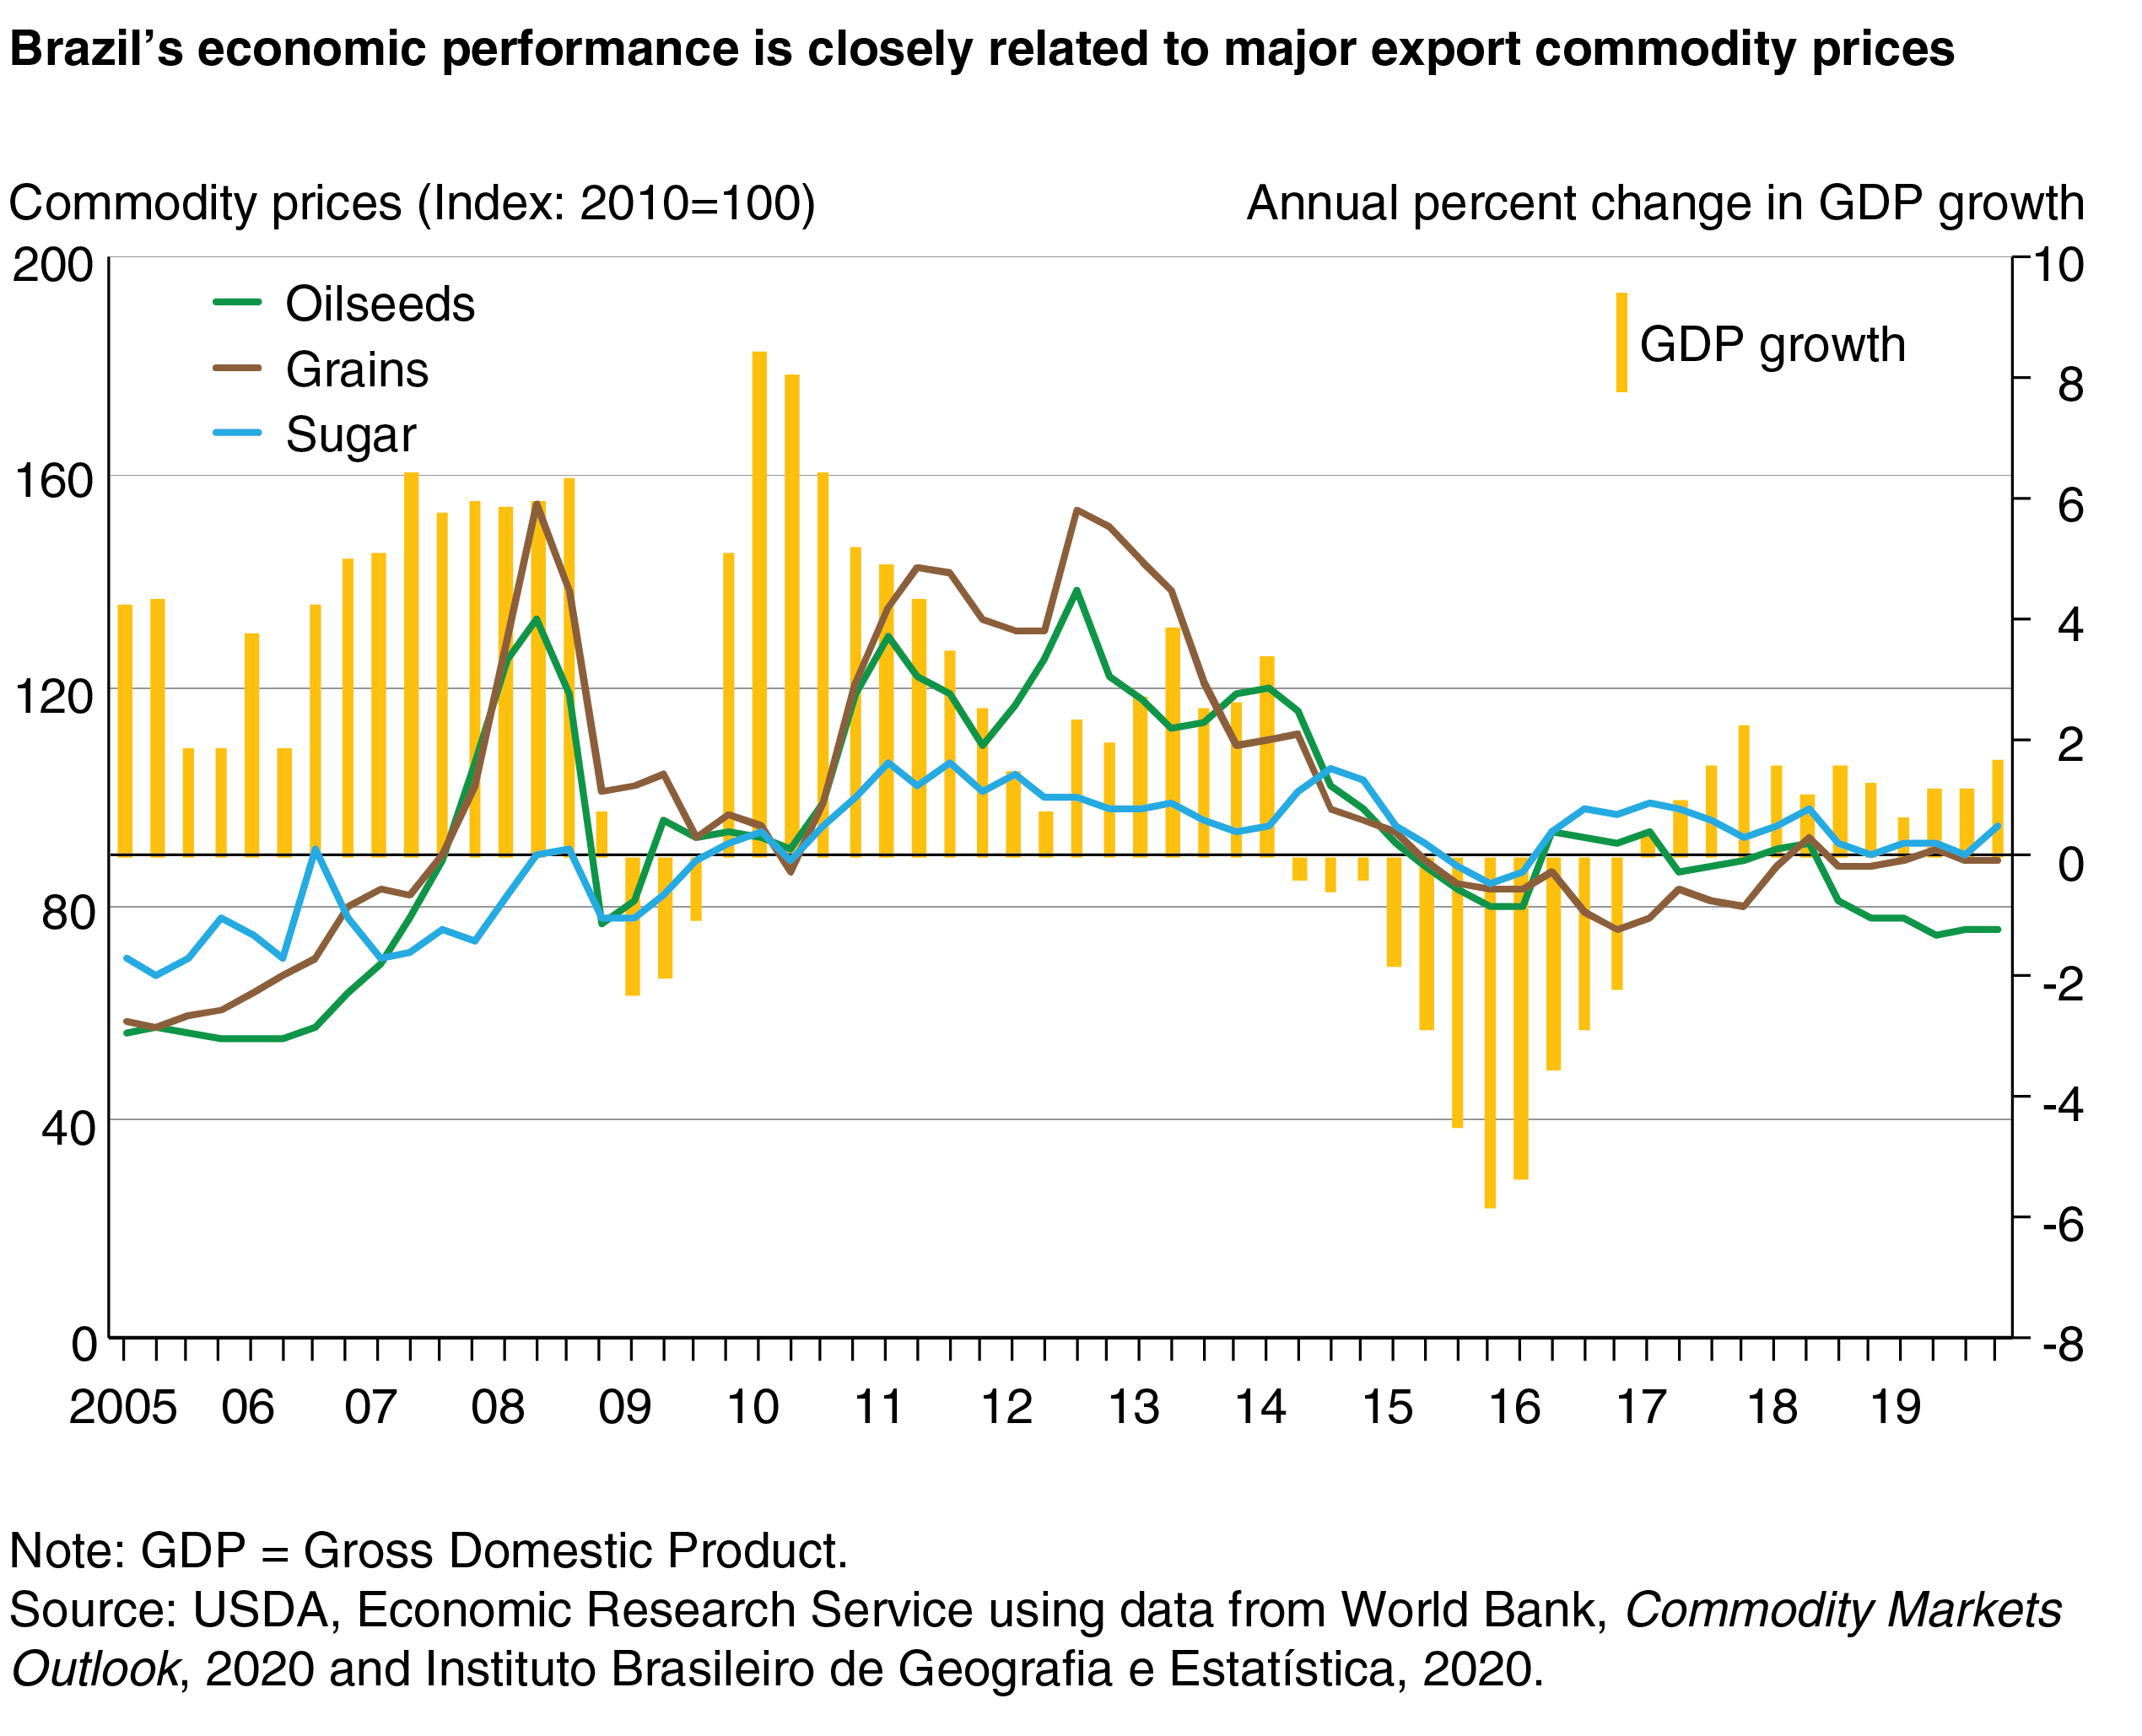
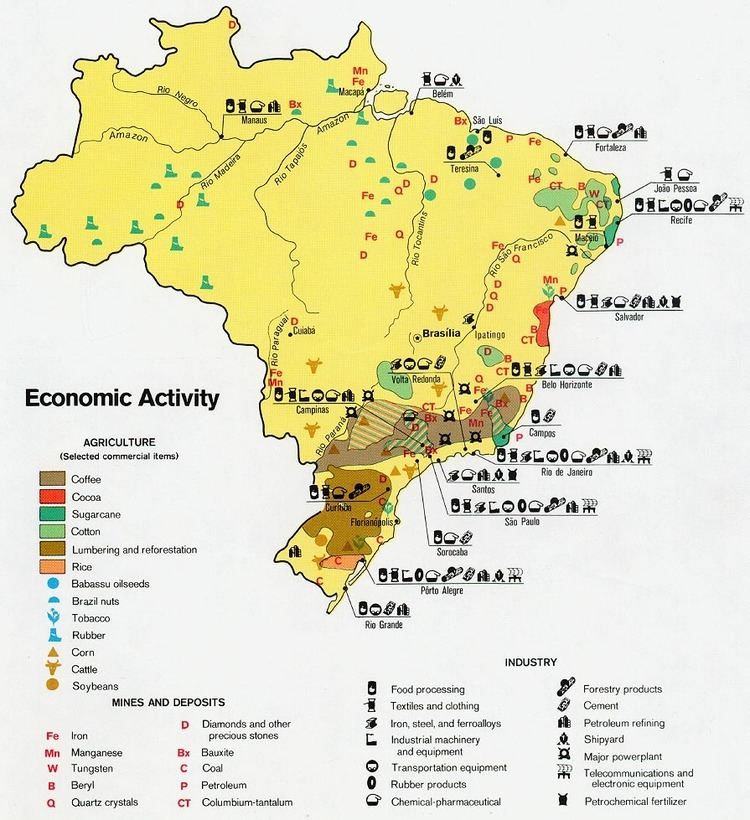
If you are building a model around Brazilian macro data, do not assume the central bank controls the short end purely through policy rates. The SELIC rate is the target, but the actual curve shape is determined by how much fiscal issuance is hitting the market and whether the government is buying its own bonds through the SNS program. That program lets the treasury deposit funds at the central bank. It is supposed to be a liquidity management tool. In practice, it became a way to absorb excess reserves and keep the SELIC artificially low when political timing demanded it. I spent weeks trying to reconcile divergent inflation expectations between the market focus report and the official IPCA print during the 2021 transition. The workaround was to stop looking at the headline IPCA and instead track the stripped inflation measure from the BNDES benchmark bond curve. It lagged reality by about a month but it was honest about what was actually priced in. The headline number was being distorted by temporary energy tariff adjustments that the regulator temporarily capped. The export sector adds another layer of complexity. Brazil is the world's largest sugar producer, a top soy and iron ore exporter, and a major aerospace manufacturer through Embraer. When commodity prices spike, the real appreciates. When they crash, the real depreciates hard. This commodity currency feedback loop means Brazil's trade balance can swing by over 20 percent of GDP between boom and bust cycles. It also means the central bank's inflation target of 3 percent, with a two percentage point margin, keeps getting disrupted by imported price shocks that have nothing to do with monetary policy. People often miss that Brazil's debt structure is mostly domestic. Unlike Argentina, which blew up because it owed everything in foreign currency, Brazil owes primarily in reais. That sounds like a stability advantage. It is not. It means the government can monetize its debt, which destroys the currency's value over time and forces the central bank to keep real interest rates structurally higher than they would be otherwise. The result is a high-interest-rate trap. The SELIC has stayed elevated for years because the fiscal deficit requires constant borrowing and the only buyers are domestic banks and pension funds demanding yield that compensates for inflation risk. Lowering rates without fixing the primary surplus is impossible. Every administration has tried. None have succeeded.
Get the Full Details
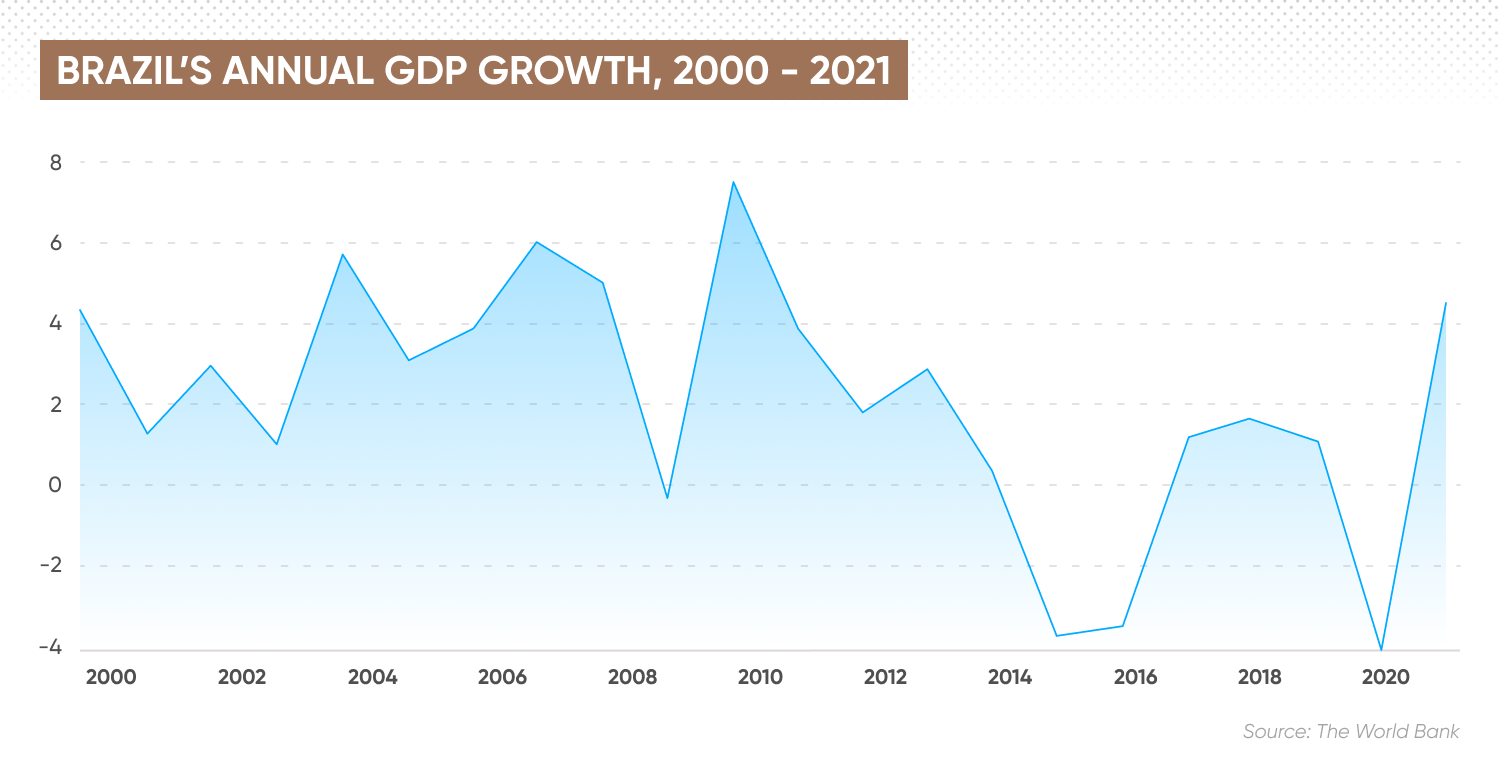
The 2016 constitutional spending cap was supposed to solve this. It tied primary expenditure growth to inflation. It worked for a few years, kept the deficit from exploding, and let the real stabilize around 3.50 against the dollar. Then the pandemic hit and the cap was suspended. It was never reinstated with real enforcement. The fiscal framework that replaced it in 2024 has similar structures but again lacks enforcement mechanisms. I have seen analysts treat these frameworks as binding constraints when they are really just aspirational. The market punishes violations quickly through the currency and bond spreads, but the political cost of actually cutting spending remains prohibitively high for any sitting president. If you want to study this properly, start with the inflation period from 1980 to 1994. Read the original Real Plan design documents from the BCB archive. They are available online in Portuguese and they explain the URV mechanism better than any English summary. Then look at the SELIC target path from 2005 to present and overlay it with the fiscal surplus or deficit data from the Secretariat of Federal Revenue. You will see the pattern immediately. Every time the primary balance turns negative, the central bank is forced to hold rates higher than the inflation target alone would require. The gap between the neutral rate and the policy rate is essentially a fiscal tax disguised as monetary policy. The common pitfall is assuming that commodity windfalls fix Brazil's structural issues. They do not. They create temporary appreciation, improve the trade balance, and give politicians room to delay reform. Then the commodities drop and the old problems return with compounding interest. The 2000s boom funded social programs and reduced poverty significantly. It also funded wage increases and tax breaks that expanded the fiscal base without expanding productive capacity. When iron ore prices fell in 2012, the recession was deeper than it needed to be because the fiscal space had been consumed by permanent spending rather than temporary stimulus.
Another mistake is treating the central bank as a pure inflation fighter. The BCB has a dual mandate in practice even though the law only mentions inflation. Financial stability matters to them because exchange rate pass-through to inflation is so fast. A 10 percent real depreciation can add nearly 2 percentage points to annual inflation within six months. So the central bank routinely intervenes with swap auctions and sometimes direct FX sales to prevent disorderly moves. This is not free money. The swaps cost the treasury and show up in the fiscal deficit. But they prevent the kind of panic-driven depreciation that turned manageable inflation into a spiral like the ones in the late 1980s. The most useful resource I found for tracking this was the BCB's own database, BDDE, combined with the IPCC inflation reports published weekly. The market focus survey inside those reports gives you the consensus expectation distribution, which is far more informative than the point estimate. I built a simple dashboard that tracked the 25th and 75th percentile inflation expectations alongside the SELIC path and the CDIs. When the spread between those percentiles widened above 150 basis points, it reliably preceded a policy shift within two to three months. That gave me a practical early warning system that was more accurate than most of the sell-side commentary coming out of São Paulo at the time. What makes Brazil different from other emerging markets is the sheer size of the internal economy. Brazil is not a small open economy that gets dominated by external flows. It has a large domestic consumer base, a diversified industrial sector, and a financial system that is mostly local currency denominated. That means external shocks matter but they do not dictate the entire path. Domestic politics matter more. A poor harvest in the south can tighten food inflation enough to force a rate hike. A regional election cycle can delay fiscal adjustment by a full year. The exchange rate can weaken because of commodity prices or because the central bank refuses to intervene and some trader decides to short the real on geopolitical noise. All of these factors interact in ways that do not happen in smaller emerging markets.
The lesson from Brazils Economic History is not that the country is doomed or that it is a value trap. It is that the constraints are real and they are largely political. The tools exist. The central bank knows what it is doing technically. The fiscal framework exists on paper. What is missing is the political will to use them consistently across electoral cycles. Until that changes, expect the same pattern: periods of relative stability punctuated by sharp crises whenever the fiscal gap widens beyond what the domestic bond market can absorb at acceptable yields.