Why Your Break Even Calculation Is Probably Wrong
I spent about two weeks last year trying to build a break even model for a friend's food truck business. We had the truck, the permits, the location scouting done, and then we hit the spreadsheet. The initial break even came out to selling 47 units per day. Seemed tight but doable. Then we realized we'd classified the driver as an owner-operator drawing a profit share instead of a salaried employee. That shifted fixed costs by about $3,200 a month and pushed the break even to 73 units daily. Not the same business at all. This is what most people miss when they start building a Break Even Analysis Business Plan. They get the formula right and the accounting wrong. The formula itself is straightforward enough that even a high schooler could calculate it in five minutes. But the assumptions underneath it are where the whole thing falls apart if you haven't actually run a business before.
What a Break Even Analysis Business Plan Actually Looks Like
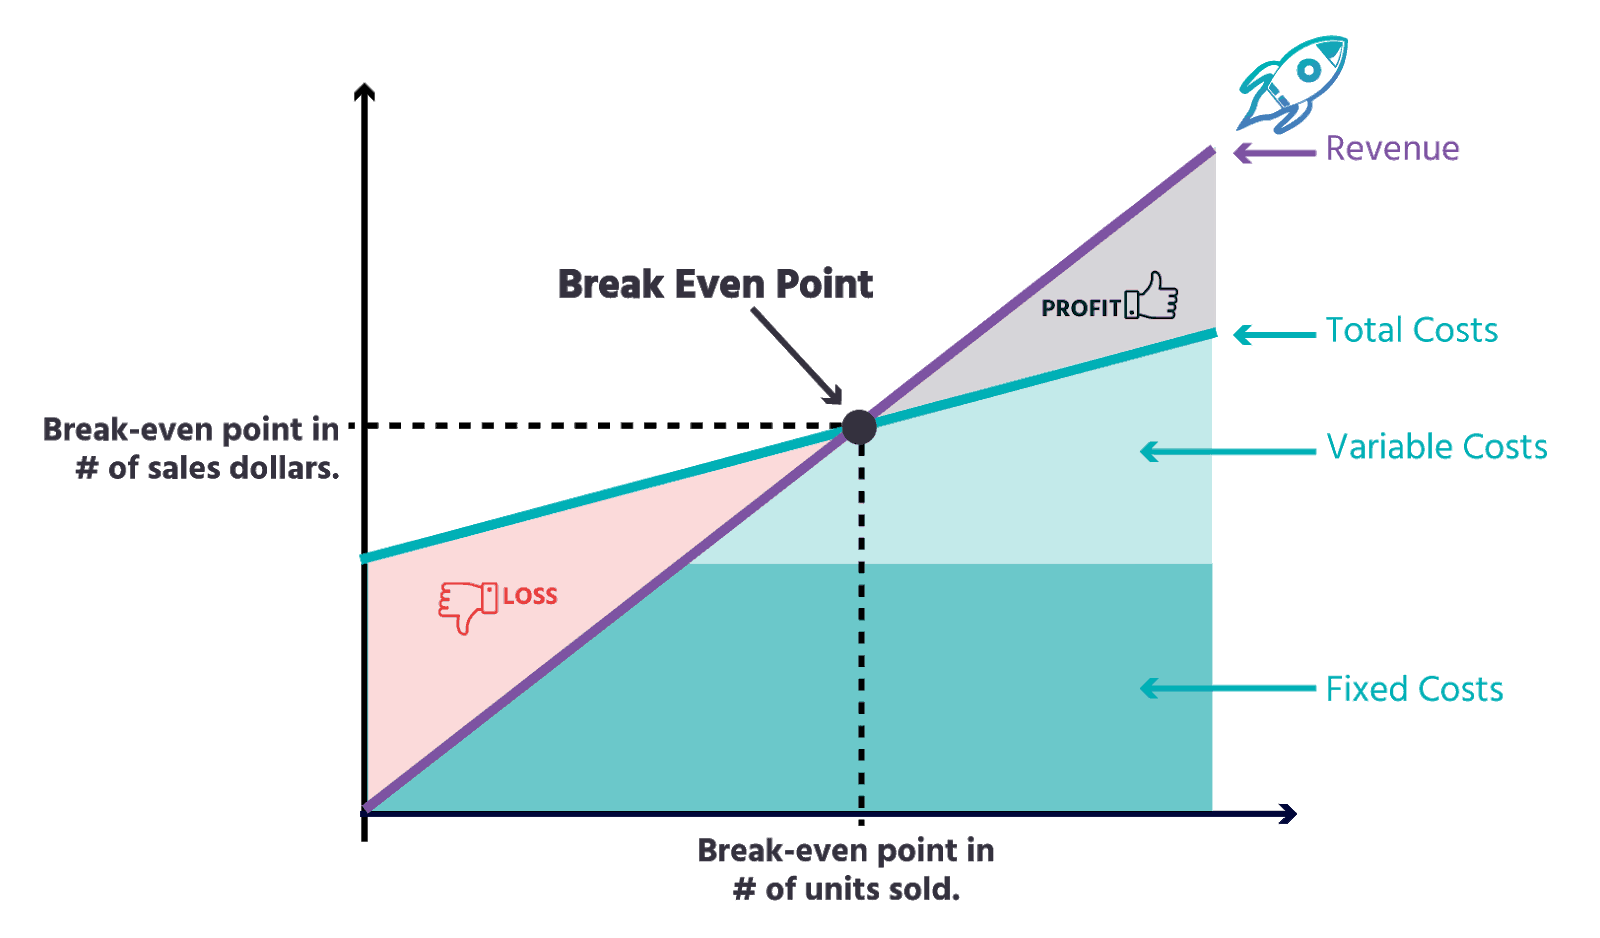
A break even analysis determines the point at which total revenue equals total costs. Nothing fancy. Below that point you're losing money. Above it you're making money. The analysis becomes a business plan document when you layer in projections, scenario modeling, and sensitivity checks so investors or lenders can see what happens if your assumptions shift. The standard formula divides fixed costs by the contribution margin per unit. Contribution margin is simply the selling price minus the variable cost per unit. Fixed costs are everything that stays the same regardless of how much you sell. Variable costs move directly with production volume. That's the textbook version. The real version requires you to sort every expense on your P&L into one of those two buckets, which is harder than it sounds. I keep a running list of items that commonly get misclassified. Insurance premiums are fixed, not variable, even if your insurer adjusts them based on revenue. Shipping costs are variable but only if you pass them directly to the customer; if you absorb them, they become a fixed operating expense. Subscription software sits in a gray zone — it's fixed by contract but variable in practice if you add seats as you grow. I've started treating subscription costs as step-fixed, meaning they hold steady until a growth threshold triggers a new pricing tier.
The Actual Process
Start by listing every expense your business will incur in its first 12 months. Put them in a spreadsheet with columns for the monthly amount, whether it's fixed or variable, and the assumption behind that classification. Don't guess. Pull quotes, look at similar businesses in your space, check industry benchmarks. If you can't find a benchmark, flag the line item and move on. Flagged items need more research later. Next, list your products or services with their selling price and the direct cost to produce each one. Material costs, labor hours tied directly to production, packaging, transaction fees — these are your variable costs. Anything not tied to a specific unit sold goes into fixed costs. Once both lists are done, calculate total fixed costs per month and divide by the contribution margin per unit. The result tells you how many units you need to sell to cover everything. Multiply that unit count by the selling price and you have your monthly break even revenue. Do this for each product line separately, then combine them if you have multiple offerings using a weighted average contribution margin based on your projected sales mix.
Get the Full Details
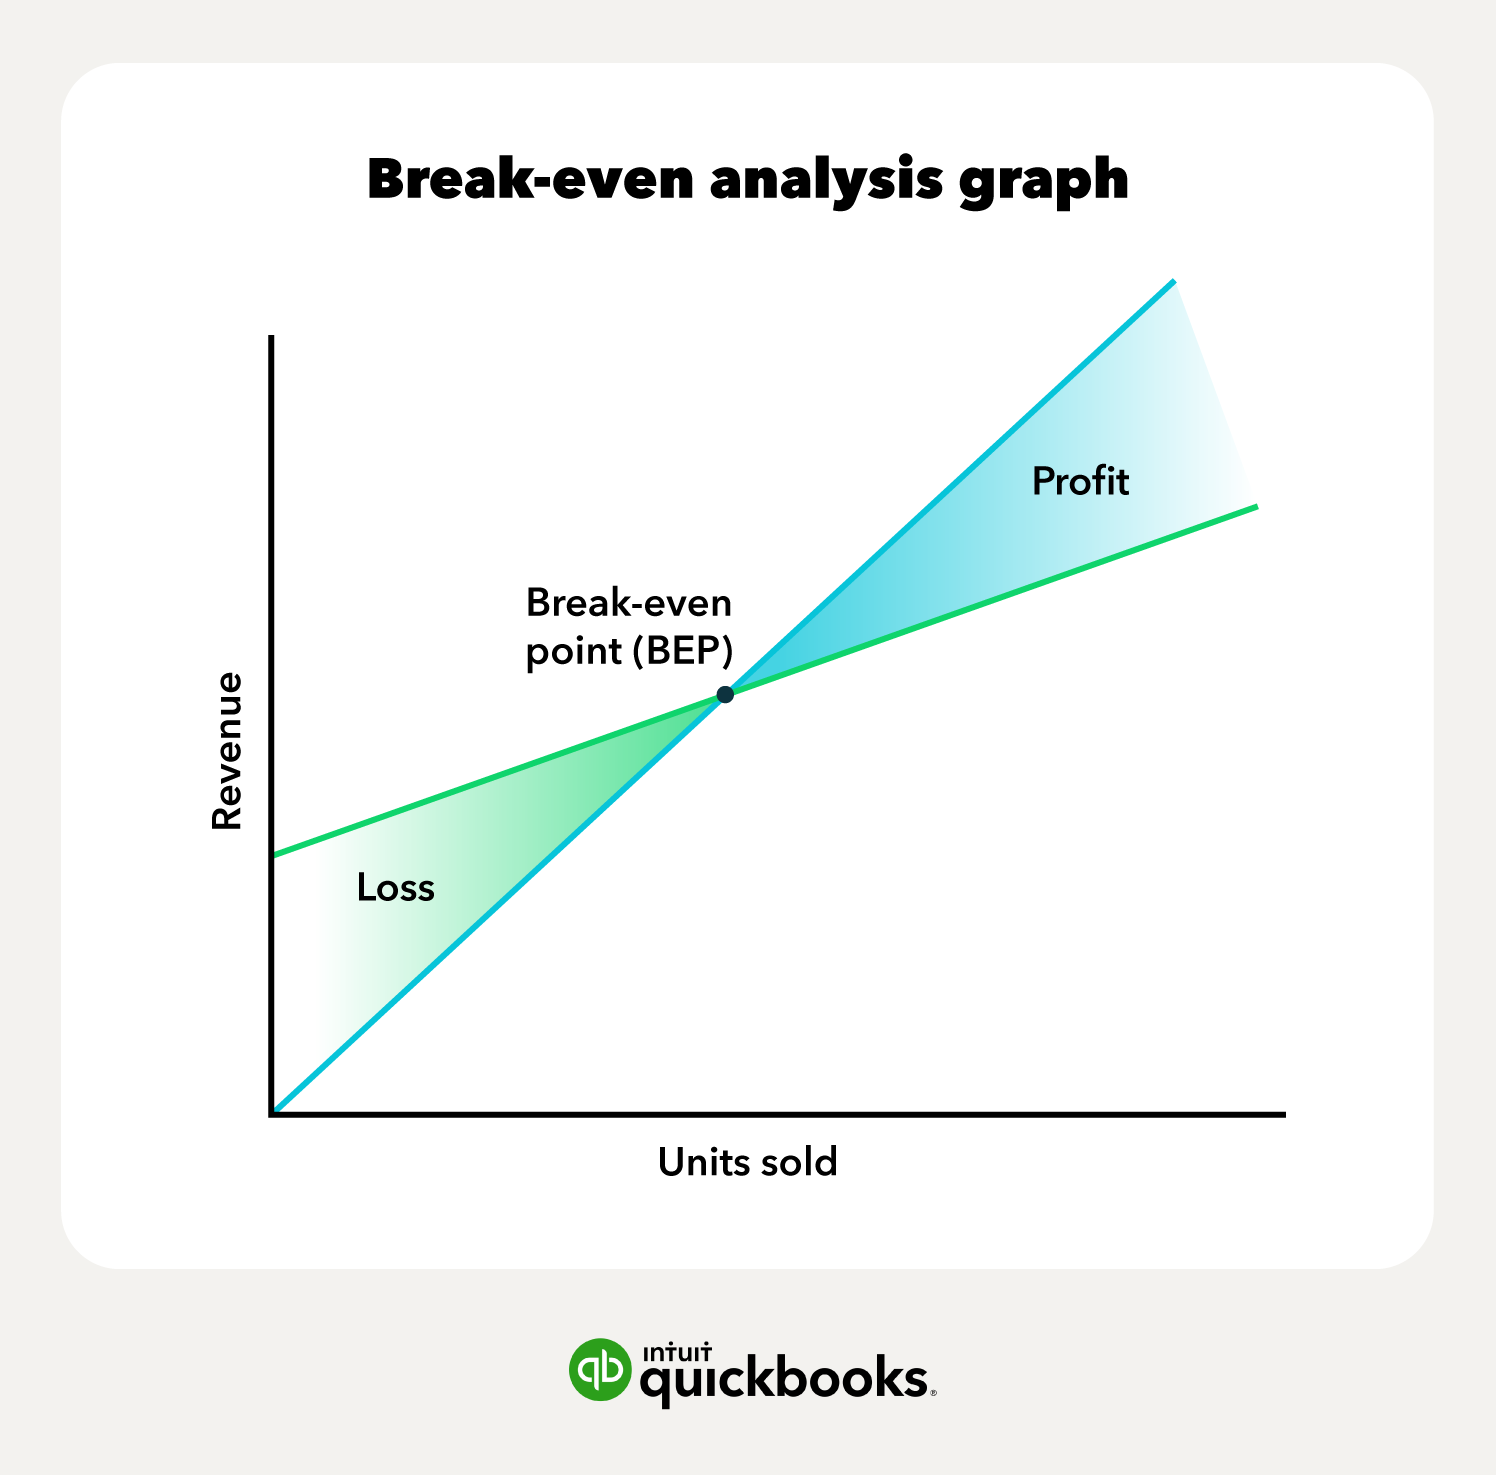
Here's where most people stop and call it done. You shouldn't stop there. Run sensitivity analysis on your three most uncertain assumptions. In my food truck example, the uncertain variables were daily foot traffic and ingredient cost volatility. I built a quick scenario table with optimistic, baseline, and pessimistic cases for each. If break even shifted from 47 to 73 units, that's a red flag worth investigating before you present anything to anyone.
Common Mistakes That Waste Weeks
The biggest mistake I see is treating break even as a one-time calculation. It isn't. Your costs change, your prices change, your market changes. A break even analysis done in January is useless by June if you haven't updated it. I recommend rebuilding or at least updating it every quarter for the first two years of a business. After that, update it whenever something material shifts — a supplier increases prices by more than 10 percent, you add a product line, you relocate to a different rent bracket. Another common error is ignoring the time value of money. Break even tells you when you'll cover costs, but it doesn't tell you whether covering costs early or late matters. If your break even is month 14 and your runway is 12 months, the analysis is accurate but irrelevant. You'll run out of cash before you reach it. I always cross-reference break even timing against my available capital and funding schedule. If they don't align, I either reduce the scope of the launch or secure additional funding before proceeding. There's also the tax trap. New business owners often calculate break even on pre-tax numbers and then get surprised by tax liability once revenue exceeds the threshold. The IRS and state agencies don't care that you thought you'd break even. Set aside 25 to 30 percent of gross profit for taxes in your model. It changes the picture significantly.
When Break Even Analysis Completely Fails
Be honest about the limitations. Break even analysis assumes linearity — that variable costs stay constant per unit and fixed costs stay constant in total. This assumption breaks down quickly in most real businesses. Raw material prices fluctuate. Labor rates change with experience and turnover. Volume discounts alter your per-unit costs at certain thresholds. Advertising spend doesn't scale linearly with revenue; you might need to spend more per customer to acquire them as the easy prospects get taken. For service-based businesses, the model is especially fragile because labor is both fixed and variable depending on how you staff. A consulting firm with 10 salaried associates has very different cost dynamics than one with 10 contractors billed hourly. The break even point for the salaried model comes faster but carries higher ongoing obligation. The contractor model has a lower fixed cost floor but variable costs that can spike unexpectedly during peak demand. When linearity assumptions fail badly, switch to a contribution margin income statement format instead. It shows revenue, variable costs, contribution margin, fixed costs, and net income in a single view. It's more work to build but far more accurate. I typically use break even analysis for quick early-stage estimates and contribution margin statements for anything that needs to survive investor scrutiny or internal quarterly review.
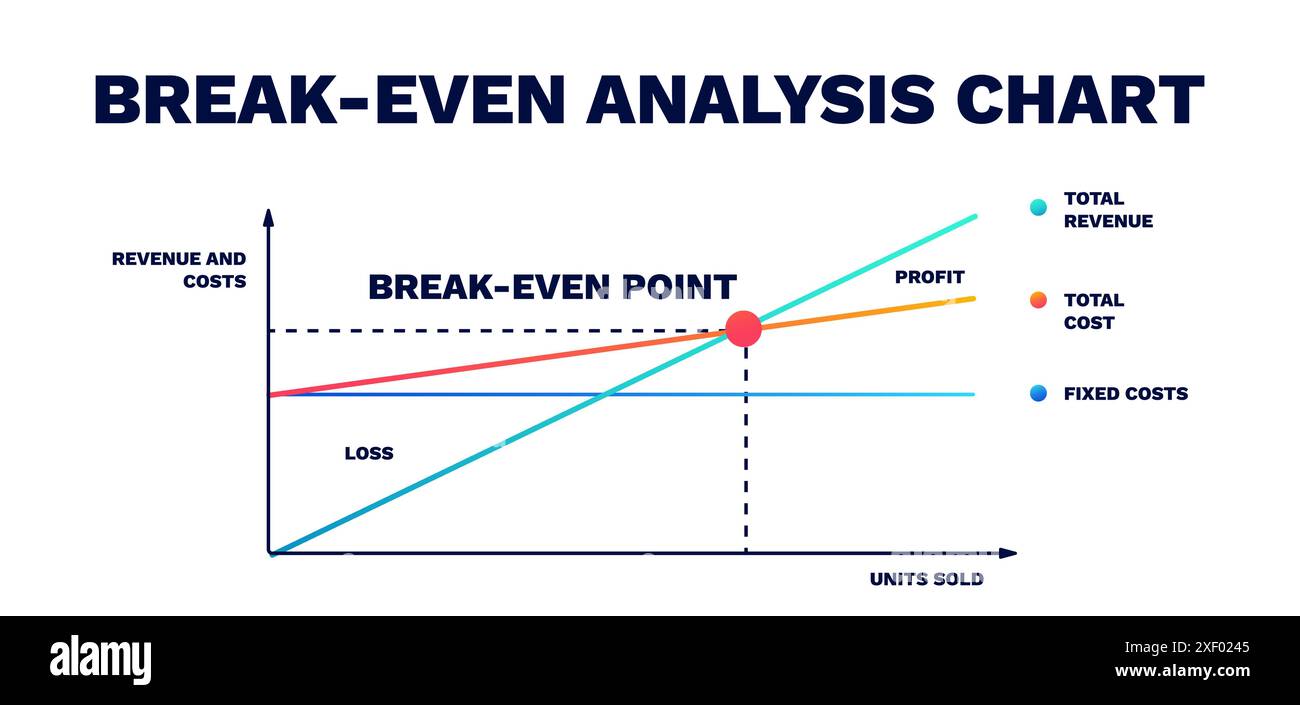
You can download a basic template if you want one that follows this approach. I've been using a modified version of the one from the SCORE website for years and just keep adding rows as needed. The structure matters more than the tool. What matters is that you treat the numbers as living estimates, not permanent answers. Your first break even calculation will be wrong. Your tenth one will be closer. The difference is whether you keep updating it or file it away and hope for the best.