The actual spreadsheet formula for break even
Most people build their break even model wrong and don't realize it until they need to present it to someone who actually knows finance. The core equation is straightforward: Fixed Costs divided by (Price Per Unit minus Variable Cost Per Unit). In Excel, that's one cell with a simple formula like =B2/(B3-B4). But the part that gets people into trouble isn't the math itself, it's how they structure the data around it and what happens when reality doesn't match the clean assumptions built into the model. I once had a client who built a perfectly clean break even model for a SaaS product, got it down to 12 minutes, and then spent three hours trying to explain why the model said they'd break even at 400 customers while their actual sales data showed they were losing money at 800. The problem was step functions in their pricing tier — a $19/month plan and a $99/month plan, and the variable costs for the lower tier were higher because they included more support overhead per seat. Her model assumed linear variable costs across all units. I ended up rewriting the whole thing to track revenue and cost per cohort instead of averaging them out. That's the kind of thing that doesn't show up in any tutorial.
Breaking Down Your Fixed And Variable Costs
You need to separate your cost structure into two buckets and keep them strictly separate. Fixed costs are things that exist regardless of whether you sell one unit or a thousand. Rent, salaried staff, software subscriptions, insurance premiums, loan payments. Variable costs move with each unit sold — materials, shipping, payment processing fees, commissions, direct labor. The most common mistake I see is people lumping items like phone bills or web hosting into fixed costs when they actually scale with usage. Those should be variable. Another issue that comes up constantly: depreciation and amortization. These are fixed costs in accounting terms, but they're non-cash. If you're using break even analysis for cash flow decisions, you need to decide whether to include them or not, and document which approach you chose. Mixing them into the same calculation without noting it creates confusion that compounds over time.
Building the model in Excel step by step
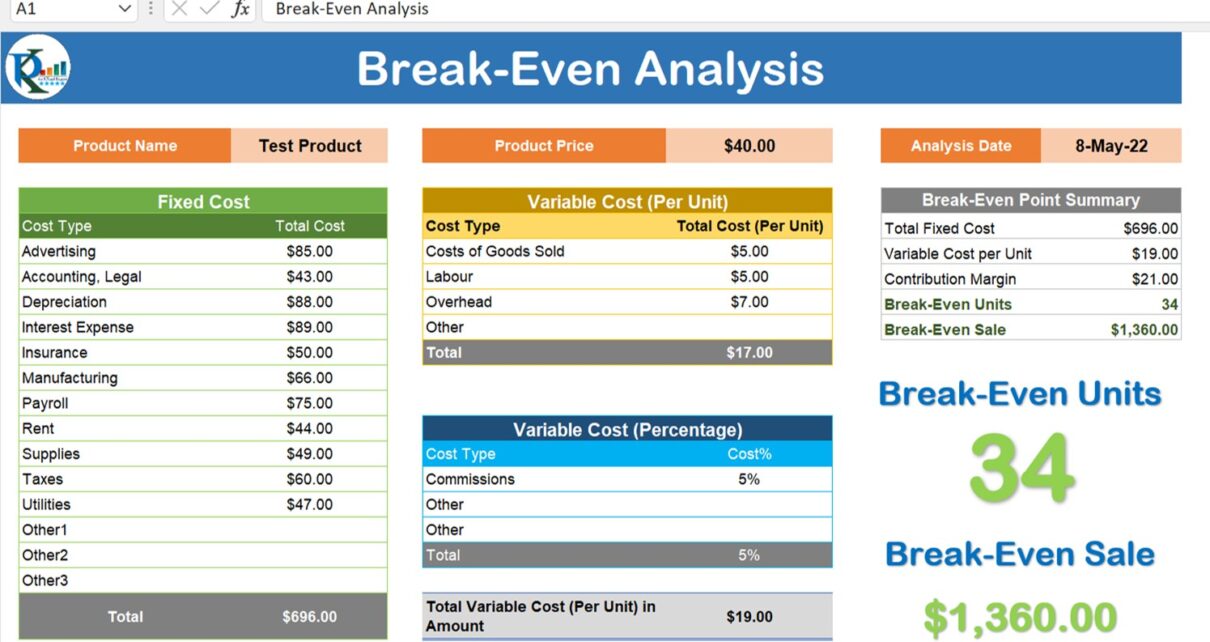
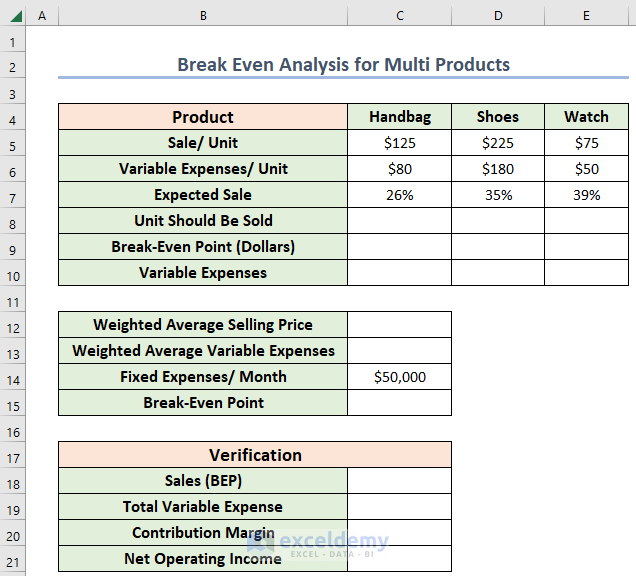
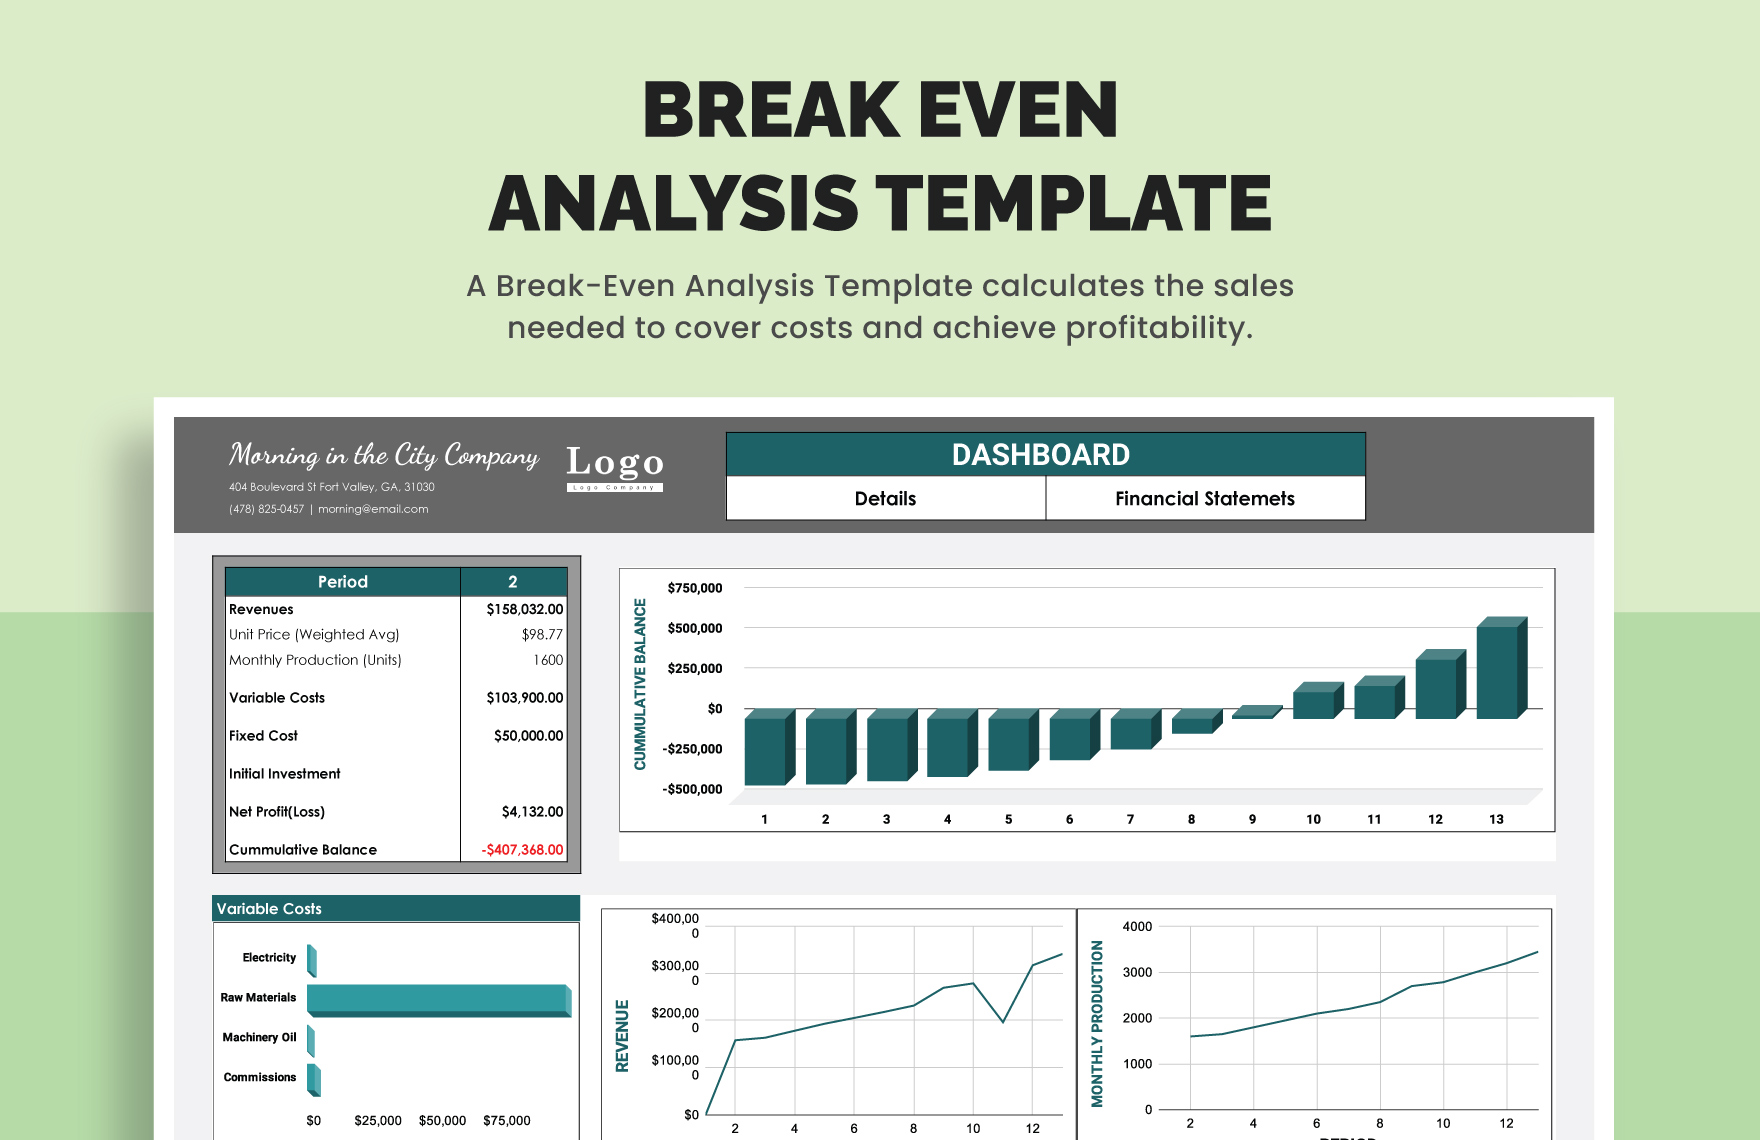
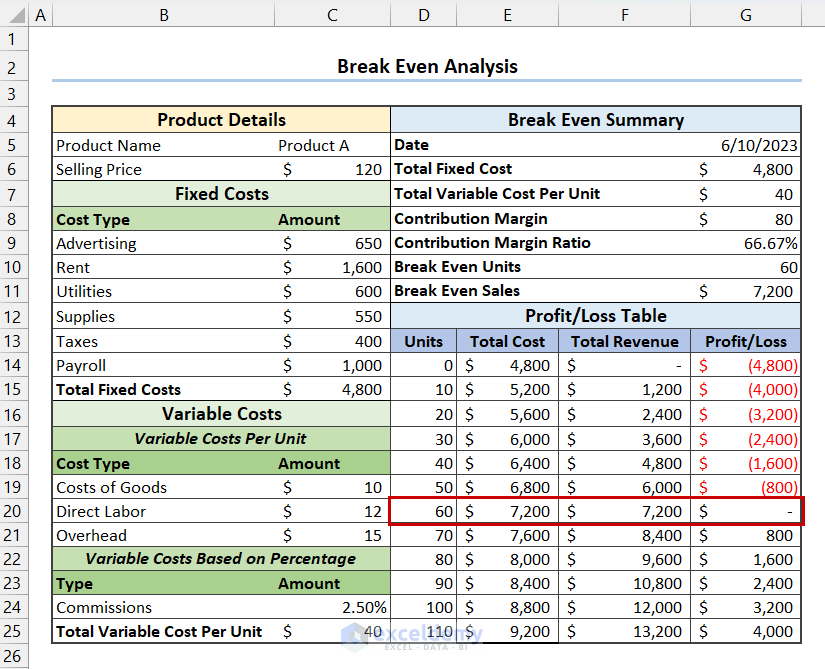
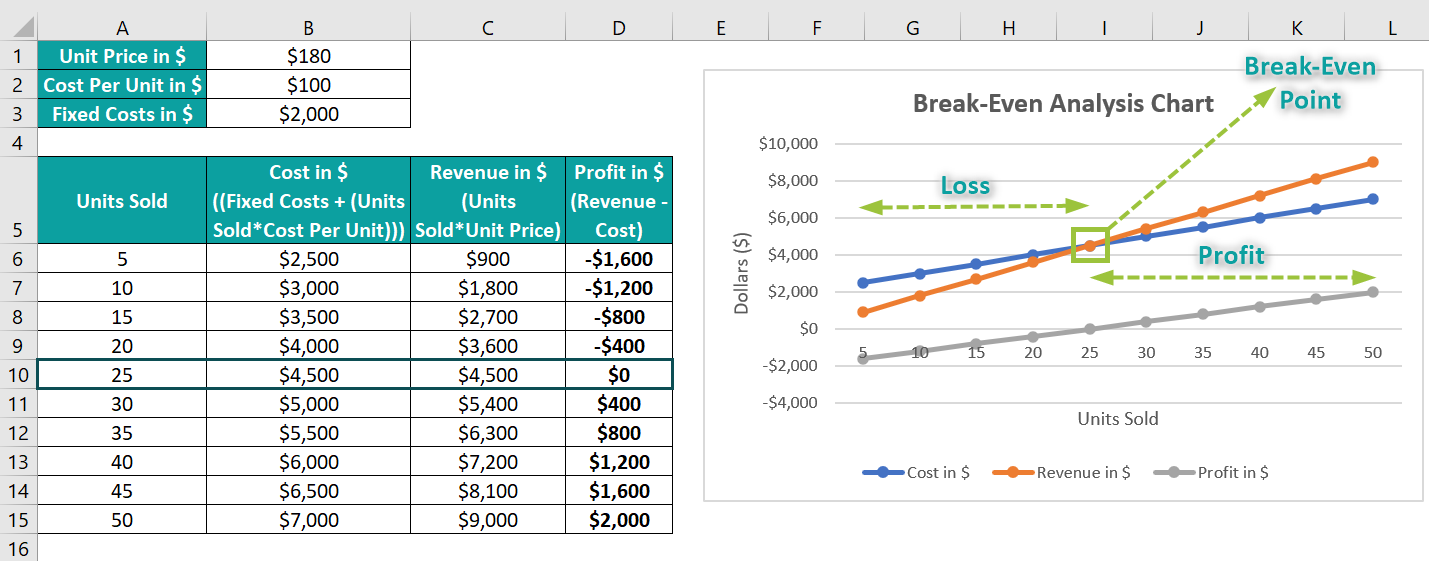
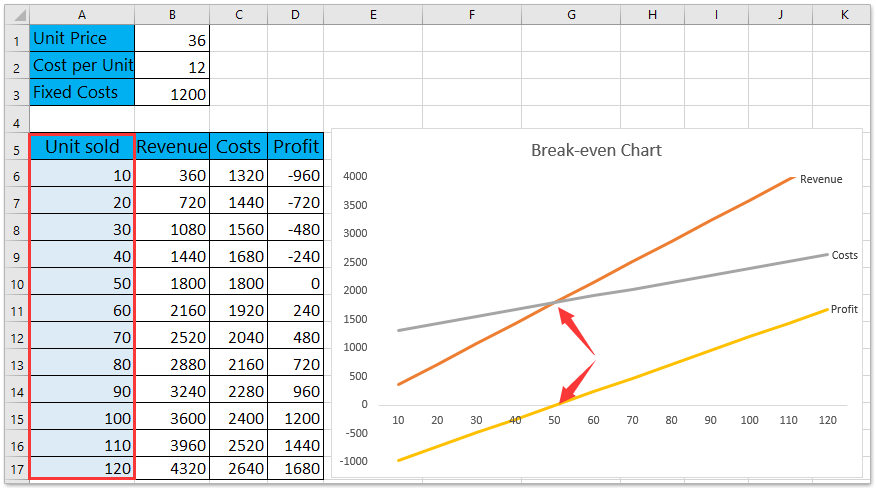
Set up your spreadsheet with labeled rows for each cost component. Column A lists the cost categories. Column B is your input area for the values, and Column C is where the formulas live. Start with your price per unit in B2, your variable cost per unit in B3, and your total fixed costs in B4. Then in C2, enter the break even formula: =B4/(B2-B3). Format that cell as a whole number since you can't sell a fraction of a unit. Below that, build a sensitivity table so you can see how break even shifts when assumptions change. Highlight cells C6 through F12, go to Data, What-If Analysis, Data Table, and set your row input to the price per unit and your column input to the variable cost per unit. This replaces the kind of manual recalculation that used to take an hour for most people who built these models by hand. For Break Even Analysis In Excel, the next critical step is adding a visual. Insert a chart with your break even point clearly marked. Plot total revenue as one line and total cost as another. The intersection is your break even point. Without this visual, it's easy to look at a single number and miss the slope — how steeply costs climb versus how steeply revenue climbs after that point. That slope determines your margin acceleration, which is often more important than the break even number itself.
Get the Full Details
Common formula errors that silently corrupt your results
There's a persistent habit I see in spreadsheets where people divide fixed costs by the selling price alone. That gives you a number, but it's wrong. You have to subtract variable costs from the price first. If you skip that step, your break even quantity will be wildly off because you're treating every dollar of revenue as profit, which is only true if your variable costs are zero. Another one that sneaks in: mixing time periods. You might have monthly fixed costs and annual variable costs, or vice versa. If you're calculating break even per month, everything needs to be on a monthly basis. If you're doing it annually, convert accordingly. I found a model once where the owner had $5,000 in monthly rent and $12,000 in annual insurance, but he'd listed the insurance as $12,000 in a monthly calculation. The break even point was inflated by a factor that made the model completely unusable for decision-making. He caught it only because the result seemed absurd compared to his gut sense of the business.
When the model hits its limits
Break even analysis assumes constant unit economics. That assumption breaks the moment you introduce volume discounts, tiered pricing, or economies of scale that change your variable cost per unit as production ramps up. If your supplier gives you a 15 percent discount after 500 units, your variable cost curve is no longer flat. The single break even number becomes meaningless because there could be multiple break even points, or none at all, depending on the shape of the cost curve. Similarly, if your fixed costs aren't truly fixed — if you need to hire another person at 300 units or lease additional space at 600 units — then your cost structure has step functions. A standard break even formula won't capture that. You'd need to build a piecewise model or use a goal seek with conditional formatting to approximate it. For most small businesses, this level of complexity isn't necessary. But if you're modeling a business where costs jump at certain thresholds, the simple formula is not going to give you useful answers. There's also the issue of what you include as "fixed." In a service business, labor is often treated as fixed because people are on salary. But if you're outsourcing or paying hourly, that cost moves with demand. Misclassifying labor is probably the single most common source of error in these models, and it skews results in both directions depending on how it's handled. Get the classification right before you trust the output.
A practical example from a real model
Last year I was looking at a custom furniture shop. Price per unit averaged $2,400. Variable costs were materials at $800, finishes at $200, and commission at $240, totaling $1,240. Fixed costs ran about $18,000 per month covering shop rent, two salaried employees, insurance, and equipment leases. The break even was 9.2 units per month, so rounded up to 10. They were consistently selling 14 to 16 units. The model showed a clear margin cushion, which was helpful for a decision about whether to take on a large commercial order. What made this model useful wasn't the break even number itself. It was the sensitivity table showing how break even shifted if material costs rose 20 percent or if they had to hire a third employee. That's where the model earned its keep — not in telling them where they were, but in showing them what could go wrong and how much room they had before things tightened up.