The Basics of Break Even Point
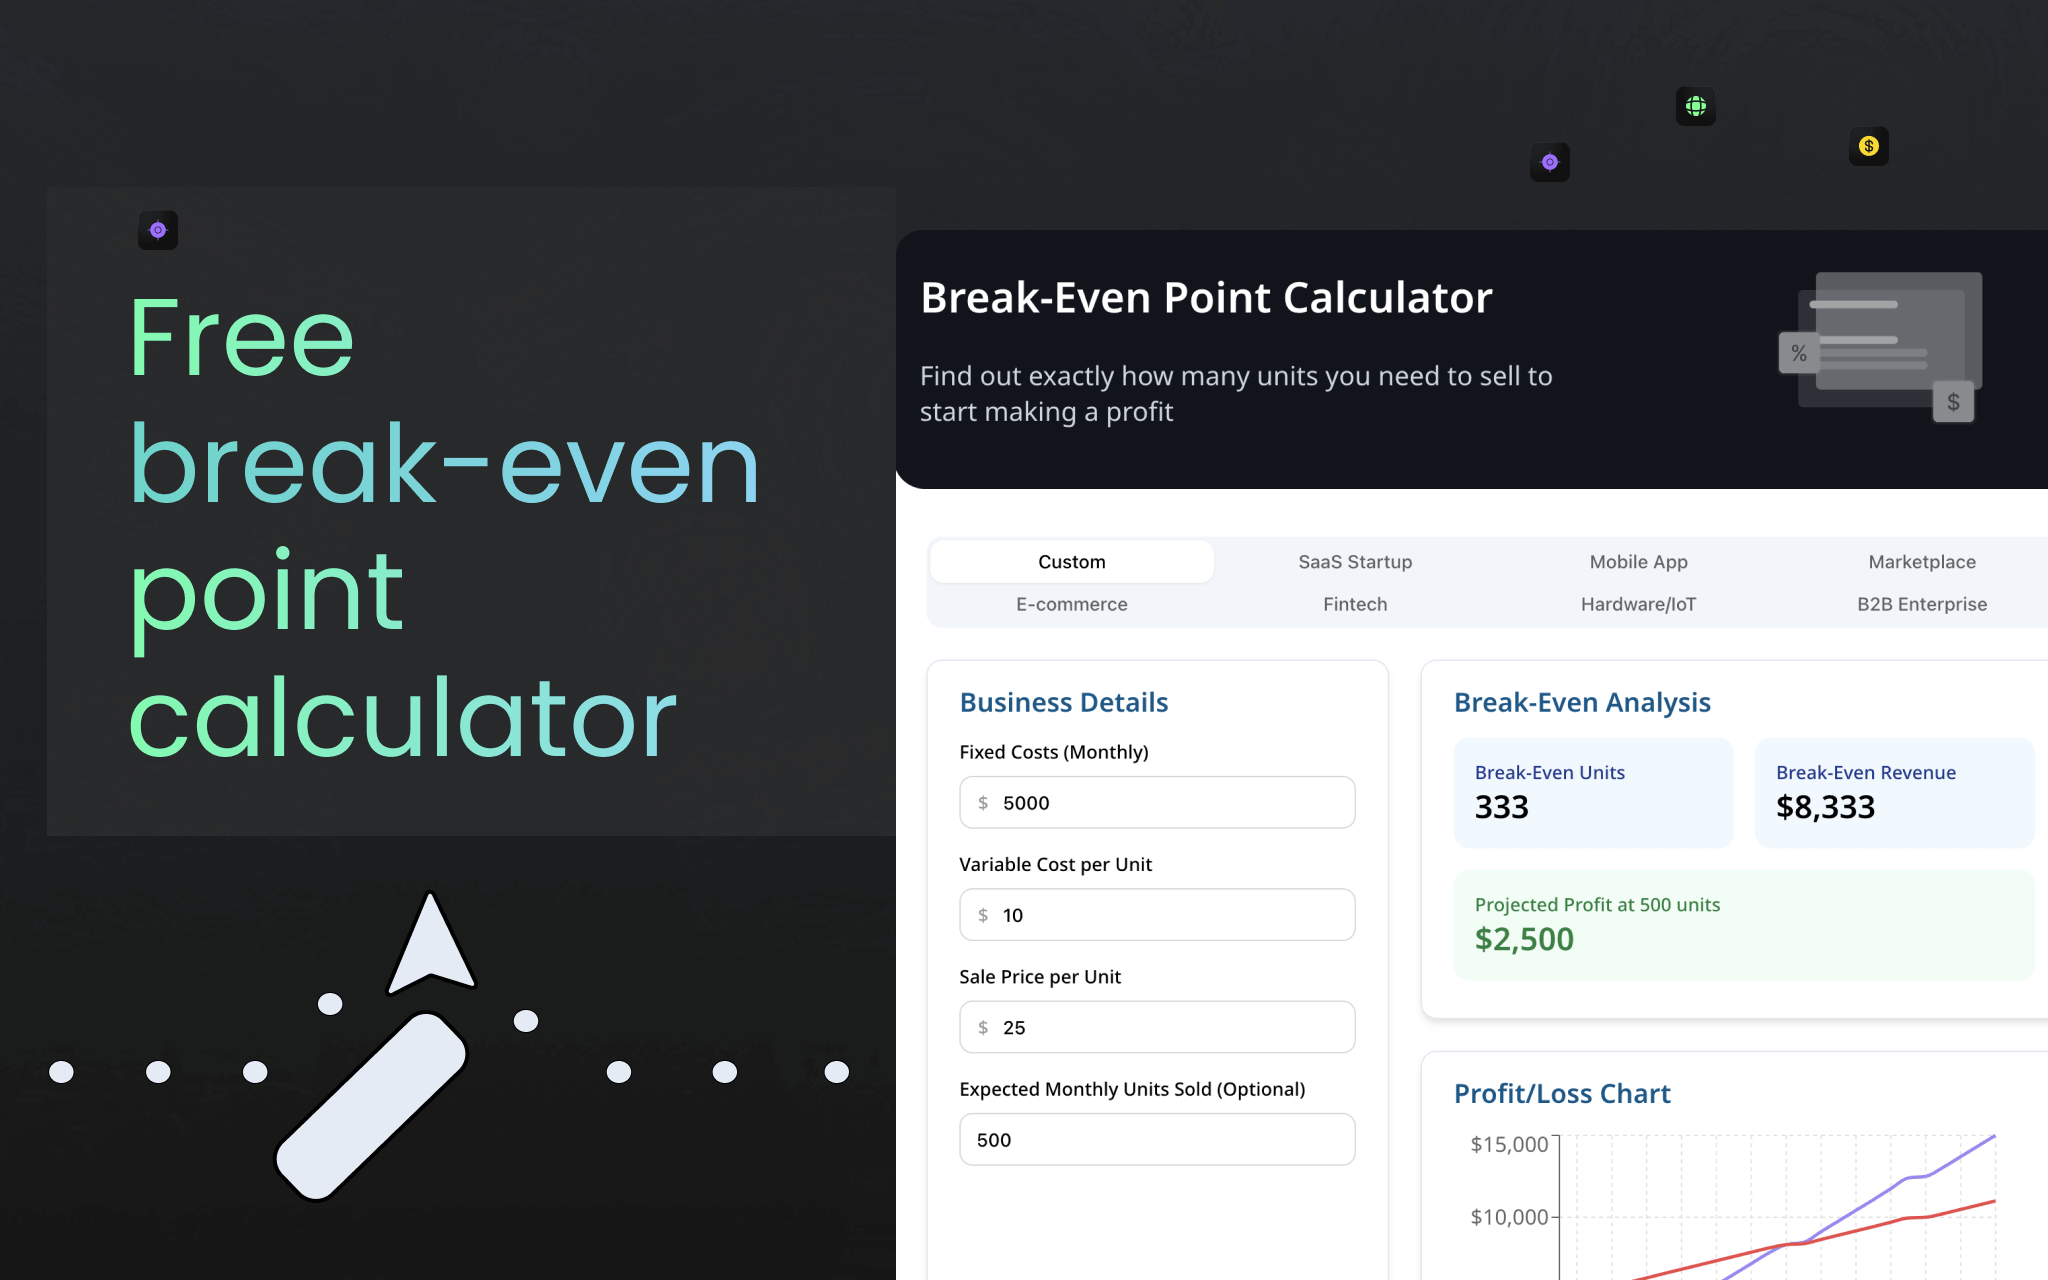
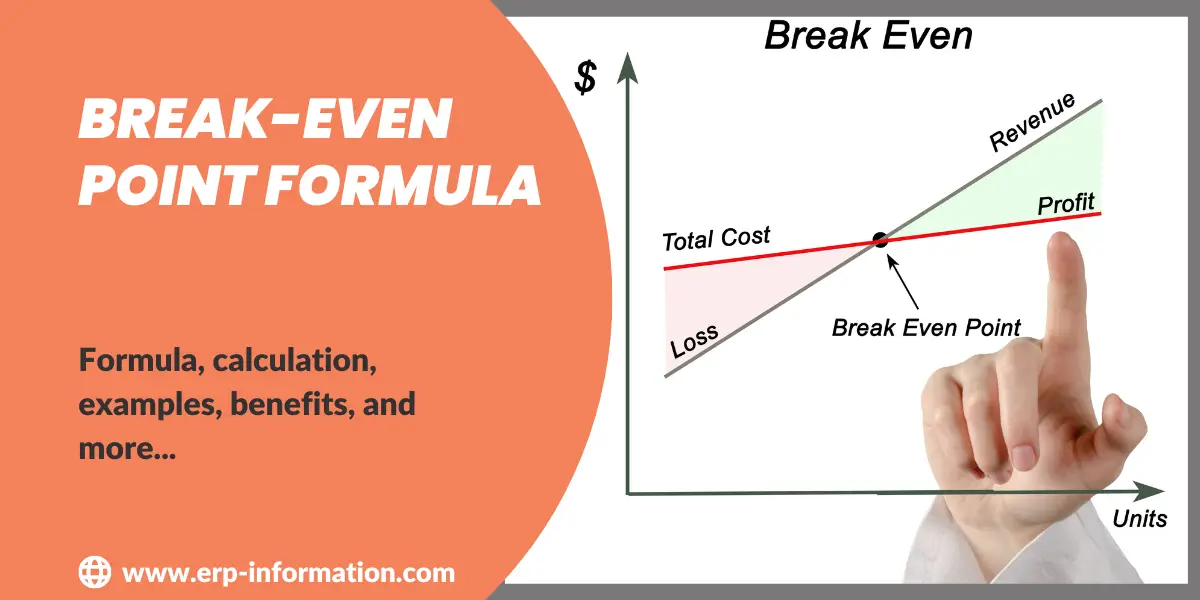
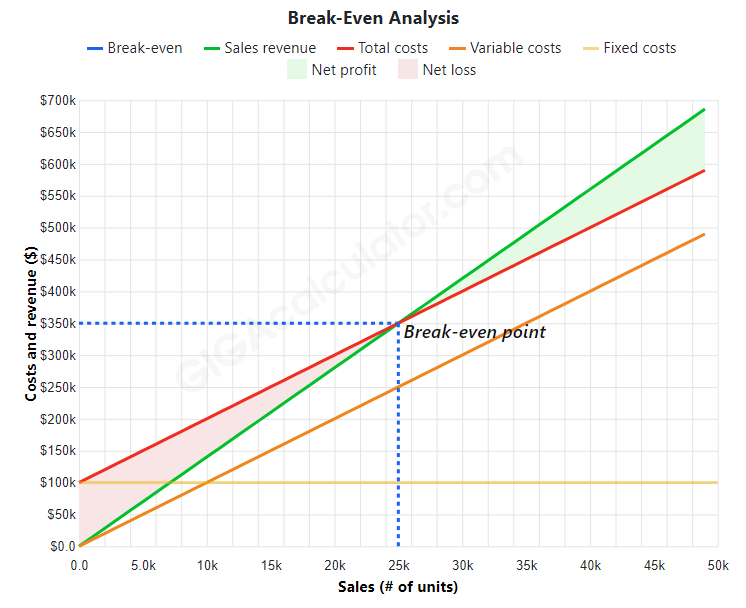
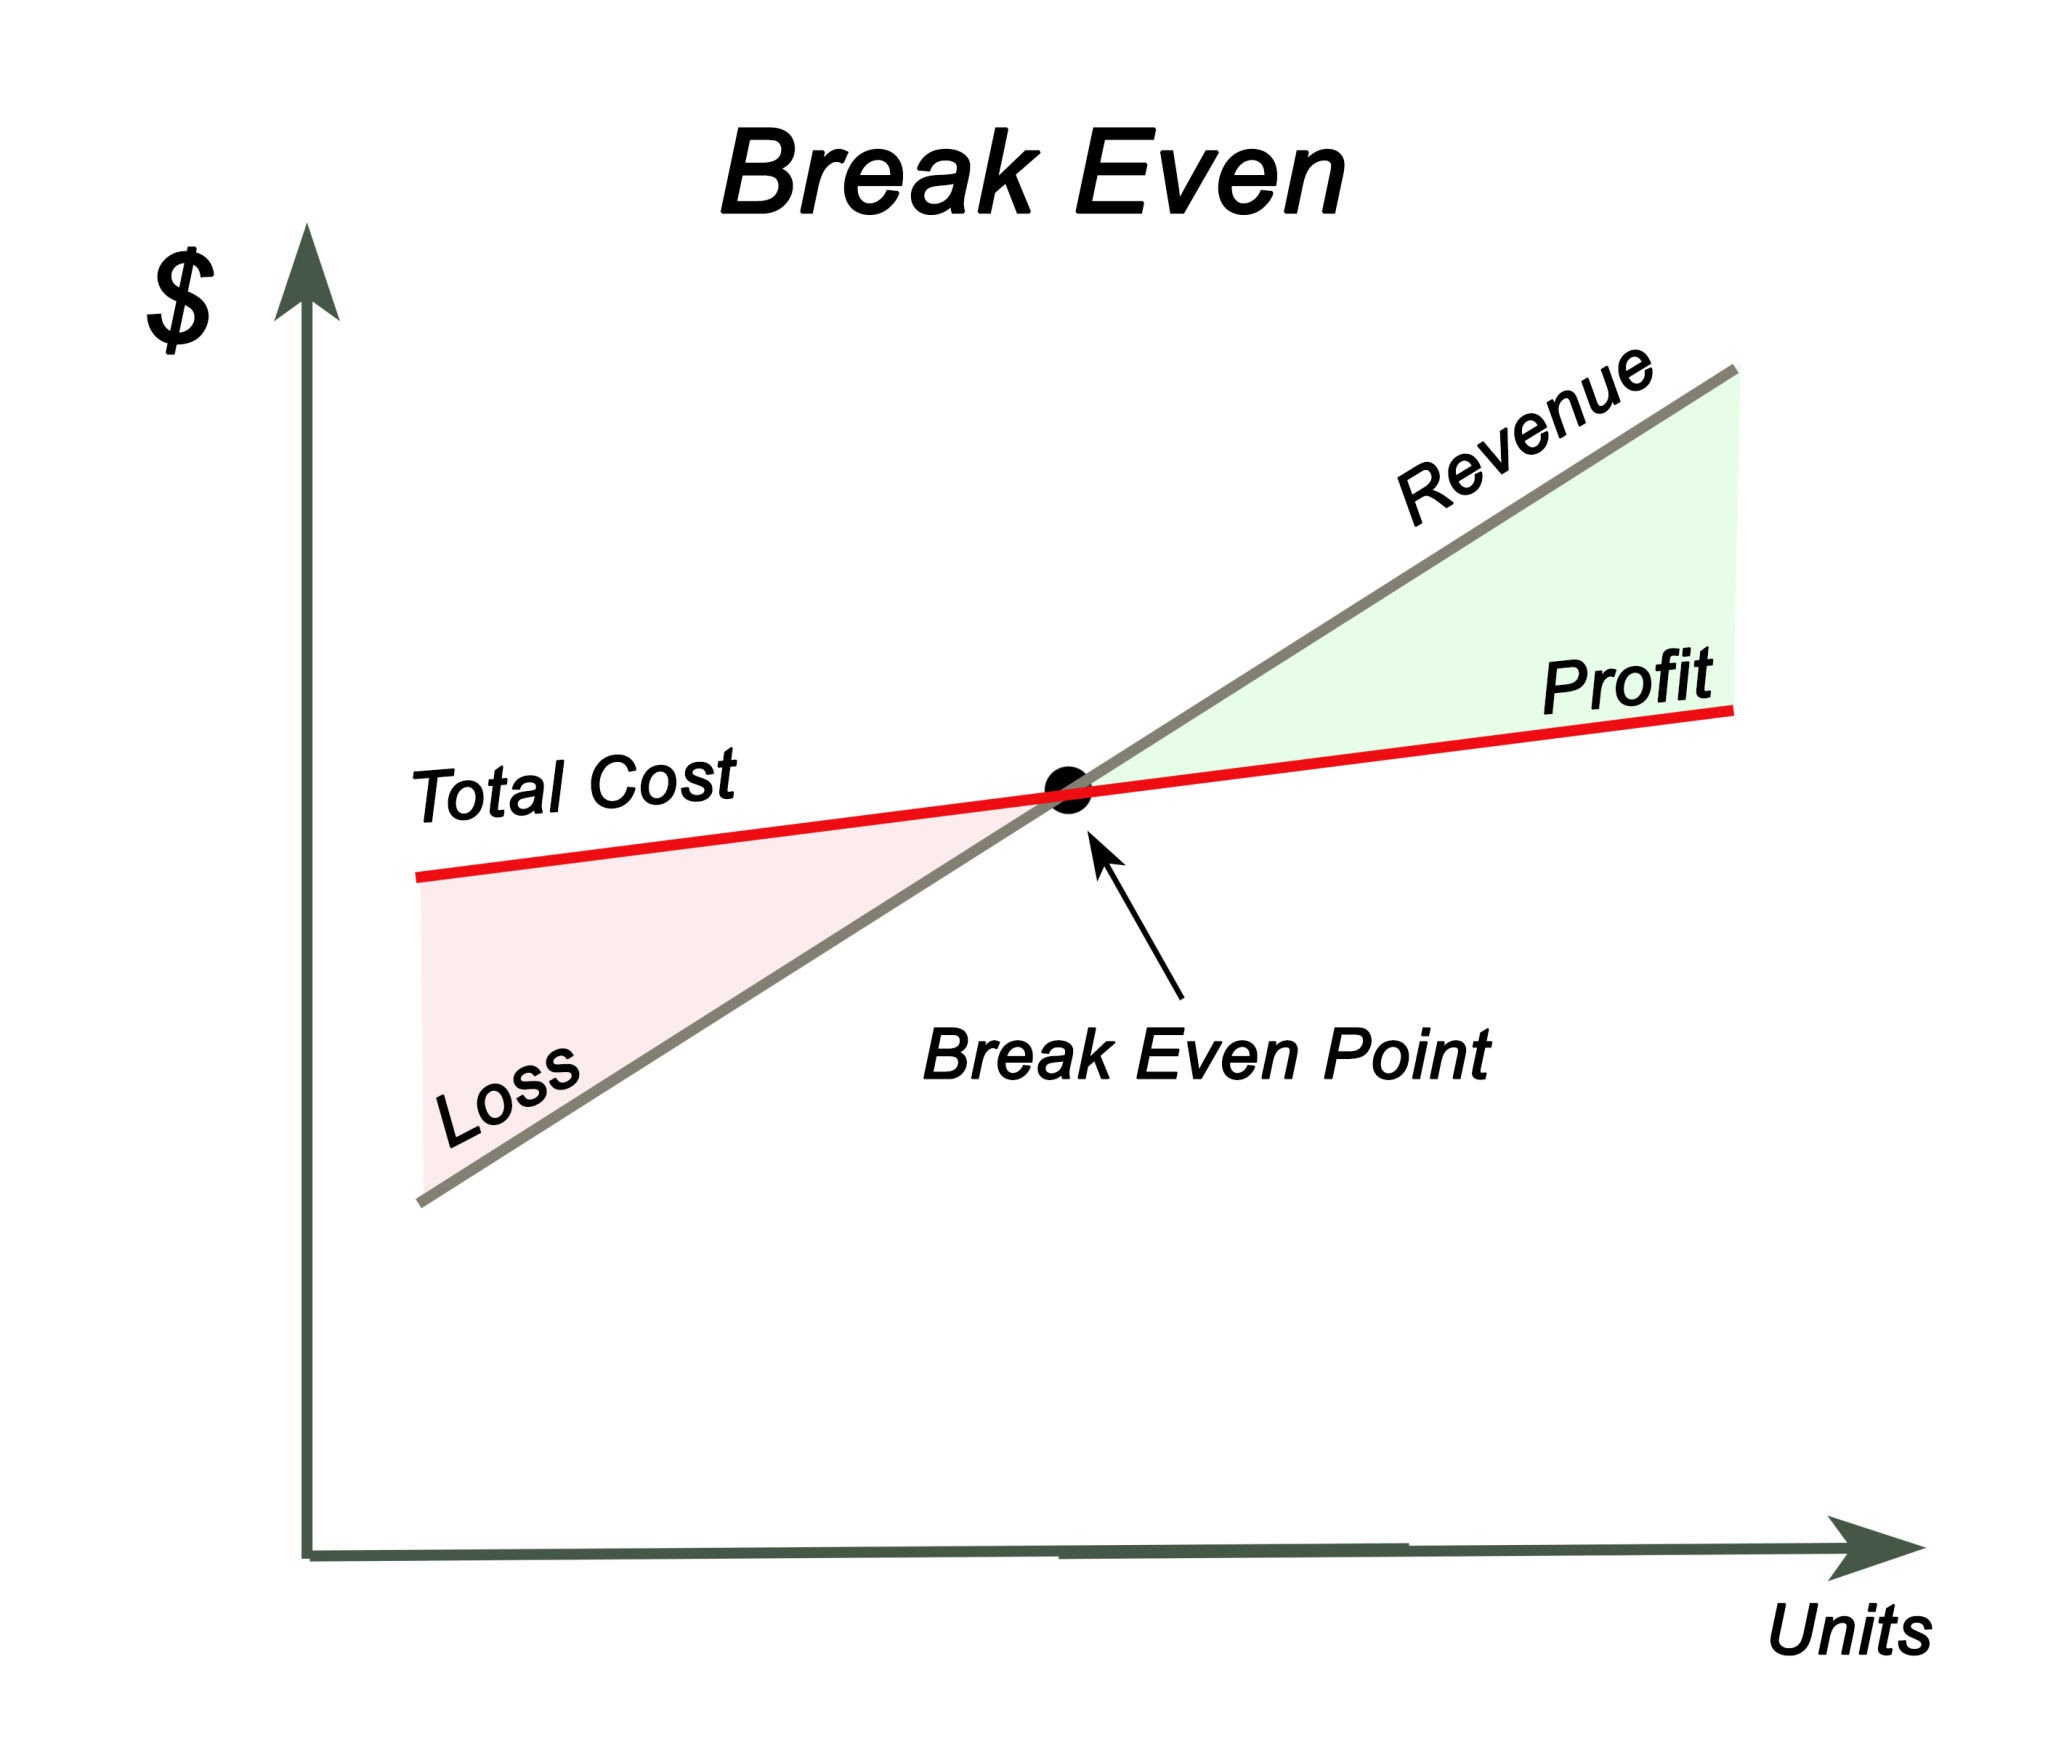
A Break Even Point Calculator figures out how many units you need to sell before you stop losing money and start making it. The math itself is dead simple. Take your fixed costs and divide them by the contribution margin per unit, which is just the selling price minus the variable cost per unit. That gives you the number of units where your total revenue exactly matches your total costs. Everything after that number is profit. I learned this the hard way when I was running a small manufacturing operation back in 2016. We were selling a custom part at $47 each. Material and labor came to about $31 per unit, and our monthly overhead—rent, equipment leases, insurance, three salaried people—landed at roughly $18,500. So $18,500 divided by $16 contribution margin equals 1,156 units per month to break even. That meant we needed to ship about 38 units a day just to stay afloat. When orders dipped to 30 a day for two straight months, we were deep in the red. Not dramatic, just painful. It made the numbers real in a way spreadsheets never do.
How to Use a Break Even Point Calculator
Most calculators online follow the same basic inputs. You enter your total fixed costs, your variable cost per unit, and your selling price per unit. Hit calculate and you get your break even quantity. Some advanced ones will also show you the break even revenue, which is just the break even units multiplied by your price. Here is the practical part that trips people up. Fixed costs are not just rent and salaries. If you are leasing equipment, that counts. Insurance premiums, software subscriptions, business licenses, minimum wage for staff you cannot fire this quarter—those are all fixed costs. Variable costs track directly with production. Raw materials, packaging, shipping, payment processing fees, commissions. If you make zero units, you should not be paying these. If you make more, they go up proportionally. I worked with a client once who had a Break Even Point Calculator spit out 2,400 units, then we dug into the numbers and realized he had forgotten about his shipping costs as a variable expense. Shipping was eating about $4 per unit. That shifted his break even from 2,400 units to roughly 2,824 units. A difference of over 400 units. He was designing pricing based on the wrong number. It happens all the time.
Where This Tool Actually Breaks Down
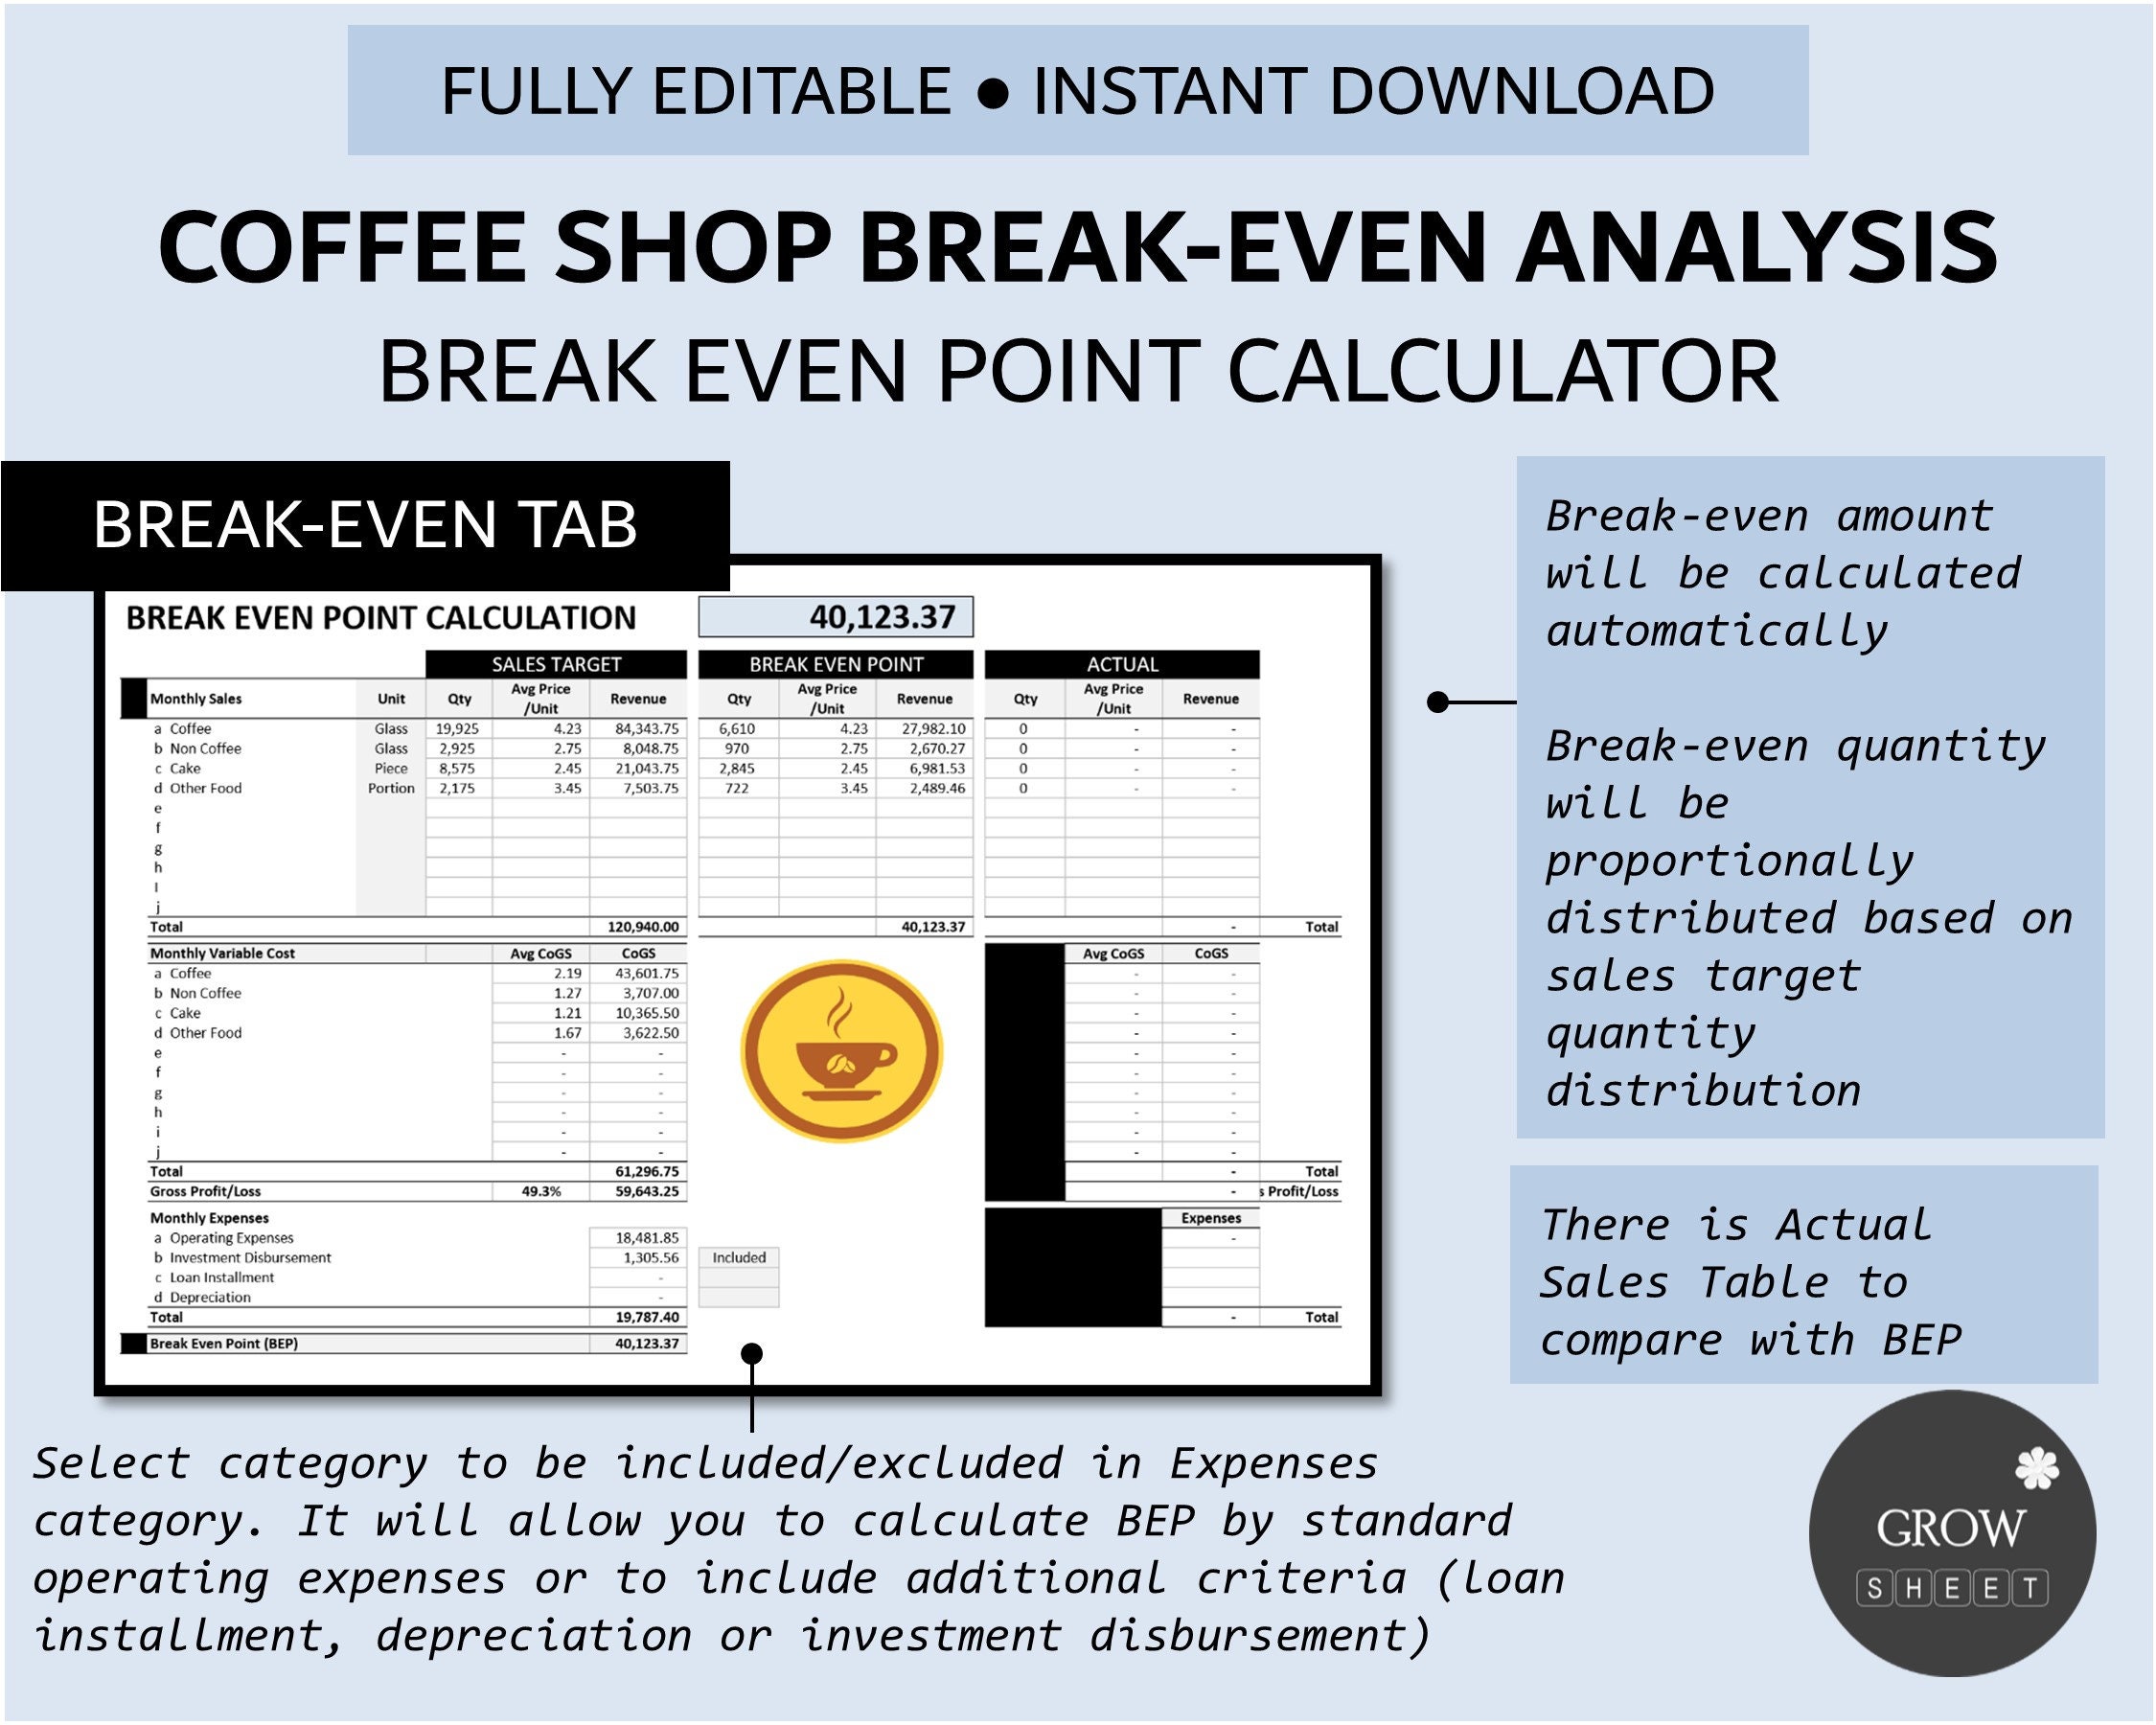
The biggest limitation most people ignore is that break even analysis assumes a constant contribution margin. That means your selling price and your variable cost per unit stay flat across all volume levels. In reality, both of those things change. You might get volume discounts on materials that drop your variable cost at higher quantities. Or you might have to discount your price to move product, which compresses your margin. The calculator cannot account for that without manual adjustments. Another issue is mixed costs. Not every cost is purely fixed or purely variable. Your phone bill has a base charge plus overage fees. Your utilities have a connection fee and a usage component. You can split these manually, but most standard calculators do not offer that feature. I ended up writing a small script that let me define cost behavior curves for individual line items instead of forcing them into binary categories. There is also the multi-product problem. If you sell more than one thing, the break even point depends entirely on your sales mix. A Break Even Point Calculator that handles only one product will give you a single number that means nothing if your customers buy a rotating assortment of products with different margins. I had to build a weighted average contribution margin based on our historical sales percentages and then calculate break even against that blended figure. It is a common workaround but most online tools do not support it natively.
Get the Full Details
Common Mistakes People Make
The most frequent error is treating sunk costs as relevant. Money already spent on equipment, R&D, or market research does not affect your break even point going forward. Only the costs you will actually incur from this decision onward matter. I see business owners include their initial startup costs in the fixed cost column and then wonder why their break even seems impossibly high. It is not impossible, it is just measuring the wrong thing. Another mistake is confusing break even with profitability. Reaching break even does not mean you are doing well. It means you are not doing badly. If your break even point is 5,000 units and you can only realistically sell 5,200, you are running a fragile business with almost no margin for error. A bad month, a supply chain hiccup, a competitor dropping prices—anything pushes you back into the red. The break even number tells you the floor, not the ceiling. People also overlook tax implications. Break even analysis typically uses pre-tax figures. Once you factor in corporate or self-employment taxes on your actual profit, your effective break even point shifts upward because you need more revenue to cover the tax burden on what was previously considered pure profit. For most small operations this is a rounding error, but for businesses operating on thin margins it can meaningfully change the picture.
When Break Even Analysis Is Not the Right Tool
If your business model is heavily subscription-based or relies on recurring revenue with low variable costs, break even analysis becomes less useful. Think about a SaaS company with high upfront development costs but near-zero marginal cost per additional customer. The concept still applies, but the unit economics look very different and the timeline to break even stretches across years rather than months. In those cases, you are better off looking at customer lifetime value and churn-adjusted metrics instead of a simple break even point. Service businesses face the same issue. A consulting firm with mostly labor costs and minimal fixed overhead does not benefit much from a Break Even Point Calculator because the variables are too fluid. Billable hours fluctuate, project costs vary wildly, and personnel expenses are often semi-fixed. Contribution margin analysis gets messy when your primary cost driver is human time billed at different rates. For businesses with long production cycles and significant capital investment, break even analysis gives you a snapshot but misses the time dimension. The real question is not just how many units you need to sell, but how fast you need to sell them. Two businesses might have identical break even points, but one achieves it in three months while the other takes eighteen. The speed matters more than the endpoint.
The bottom line is that a Break Even Point Calculator is a starting point, not an answer. It gives you a reference number to test assumptions against. Use it to challenge your pricing, your cost structure, and your sales targets. Then build on it with scenario analysis for different volume levels, pricing tiers, and cost scenarios. The tool does exactly what it promises. It just does not do anything beyond that.