What a Bridge Financing Calculator Actually Does
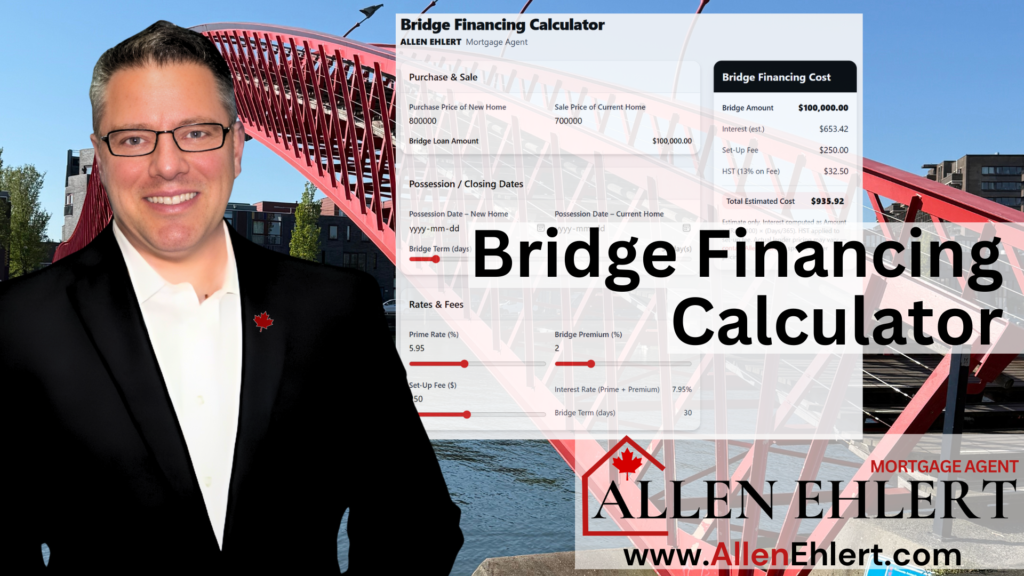
A Bridge Financing Calculator is a tool that estimates the monthly payments, total interest, and payoff timeline for a short-term bridge loan. These loans typically run anywhere from a few weeks to a couple years and carry higher rates than conventional financing. The calculator takes your loan amount, interest rate, and term and runs the standard amortization math. Simple enough on paper. In practice, most free online calculators are built for standard installment loans and don't handle the quirks that show up with bridge financing. They ignore interest-only periods, balloon payments, and the fact that many bridge loans are structured as lines of credit with draws. I spent three years underwriting real estate bridge loans before moving to a more analytical role. The first time I tried to model a typical deal with a basic calculator, it gave me numbers that were off by nearly 40 percent because the loan had a six-month interest-only period and then switched to full amortization.
Using a Bridge Financing Calculator
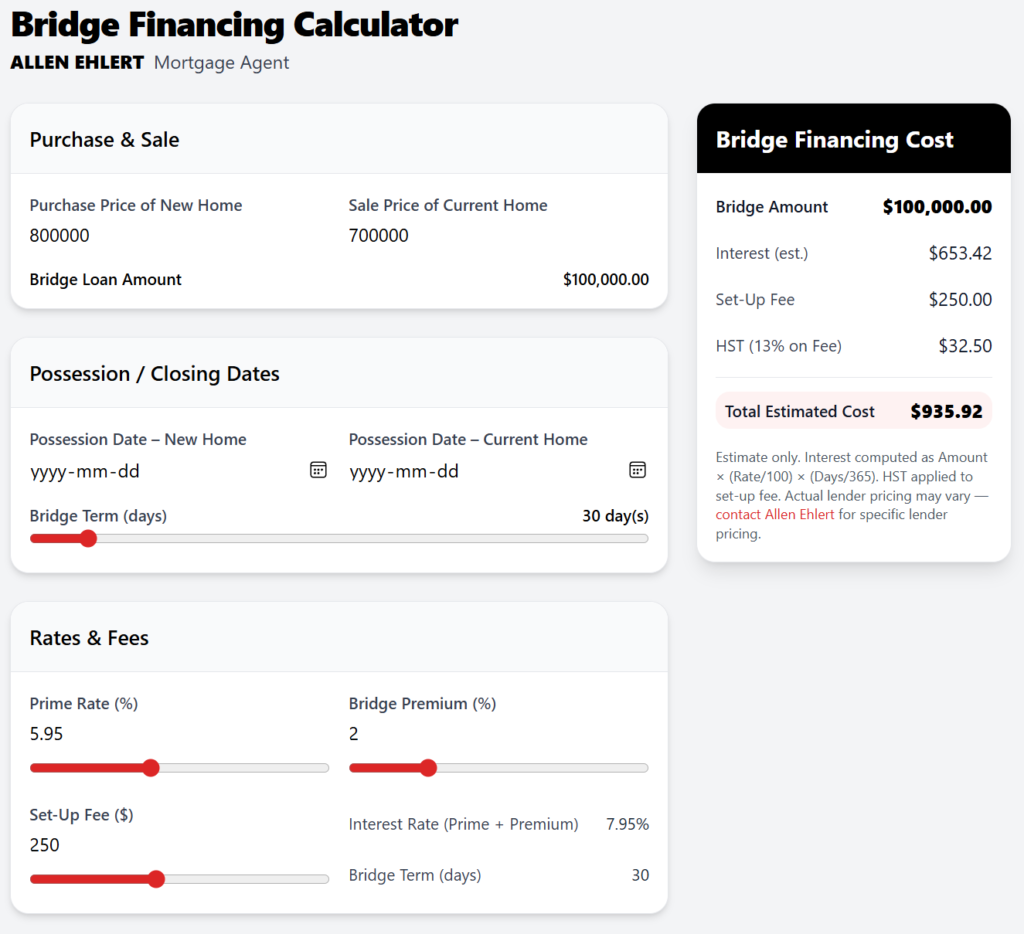
Most calculators work the same way. You input the principal amount, the annual interest rate, the loan term, and sometimes the payment frequency. The tool then calculates your periodic payment and total cost. That's the baseline version. More advanced versions let you account for monthly compounding, interest-only periods, and upfront fees rolled into the loan balance. Here's what actually matters when you're running the numbers: Input the effective rate, not just the stated rate. Bridge lenders often quote a lower nominal rate but charge points and origination fees that get rolled into the balance. A $500,000 loan at 9 percent with 2 points means you're actually borrowing $510,000 and paying interest on that higher amount. Enter the funded amount, not the face value, and adjust the rate to reflect the true cost. Most decent calculators let you do this if you know how.
Account for the draw schedule. If your bridge loan funds in tranches, the calculator needs to reflect that each draw increases the principal balance at different points in time. A single lump-sum calculation will understate your interest cost. I set up a spreadsheet that layered in each draw date and recalculated the balance forward before feeding the final numbers into the calculator. It took about ten minutes once I had the template ready. Watch out for the balloon. Bridge loans frequently come due as a lump sum at the end. Standard amortization calculators will spread payments across the full term, which makes the deal look cheaper than it actually is. Look for a calculator that supports balloon payment options or just model the interest-only phase separately and add the principal repayment at the end on your own.
Get the Full Details
Edge Cases That Break Most Calculators
I ran into a specific problem recently that every calculator I found handled incorrectly. The loan in question was a 18-month bridge facility at 11 percent, with 1.5 points, an interest-only period for months one through twelve, and then a thirty-day grace period before the full principal was due. The calculator I was using simply divided the annual rate by twelve, multiplied it by the principal, and spit out a flat monthly payment. It didn't account for the interest-only structure at all. The actual monthly obligation was roughly two-thirds of what the calculator showed during the IO period, and then the borrower owed the entire principal plus one month's interest in month fifteen. My workaround was to split the calculation into three segments. First, I calculated the IO payments using the formula Principal × (Rate ÷ 12) for each of the twelve months. Second, I computed the single grace-period payment the same way. Third, I added the principal balloon to the final month. The total interest came out to about $72,600 instead of the $108,000 the calculator initially suggested. That's a significant difference when you're presenting terms to a borrower or underwriting the deal.
When a Bridge Financing Calculator Falls Short
Not every situation fits neatly into a calculator. If your loan has variable rate adjustments tied to an index like prime or SOFR, most static tools won't model the rate changes over time. You'd need a spreadsheet with month-by-month rate projections. If the lender charges deferred origination fees that accrue rather than being taken upfront, the calculator also misrepresents the true cost. Same thing if the loan includes a prepayment penalty that scales down over time. Those elements require manual adjustment outside the tool. Another common failure mode is when the lender uses a 360-day year for interest calculations instead of 365. This is standard in commercial lending and can shift your monthly payment by a dollar or two. Over the life of the loan it adds up. Some calculators let you select the day-count convention. If yours doesn't, factor it in manually by multiplying your daily rate by the actual days in each period. If you're working with a particularly complex structure, a dedicated loan modeling tool or even a well-built Excel model with amortization schedules will serve you better than a generic online calculator. The time investment is worth it. A basic model takes maybe twenty minutes to set up, but it pays for itself the first time you encounter a non-standard deal.