Getting Through Business Associations Exams Without Losing Your Mind
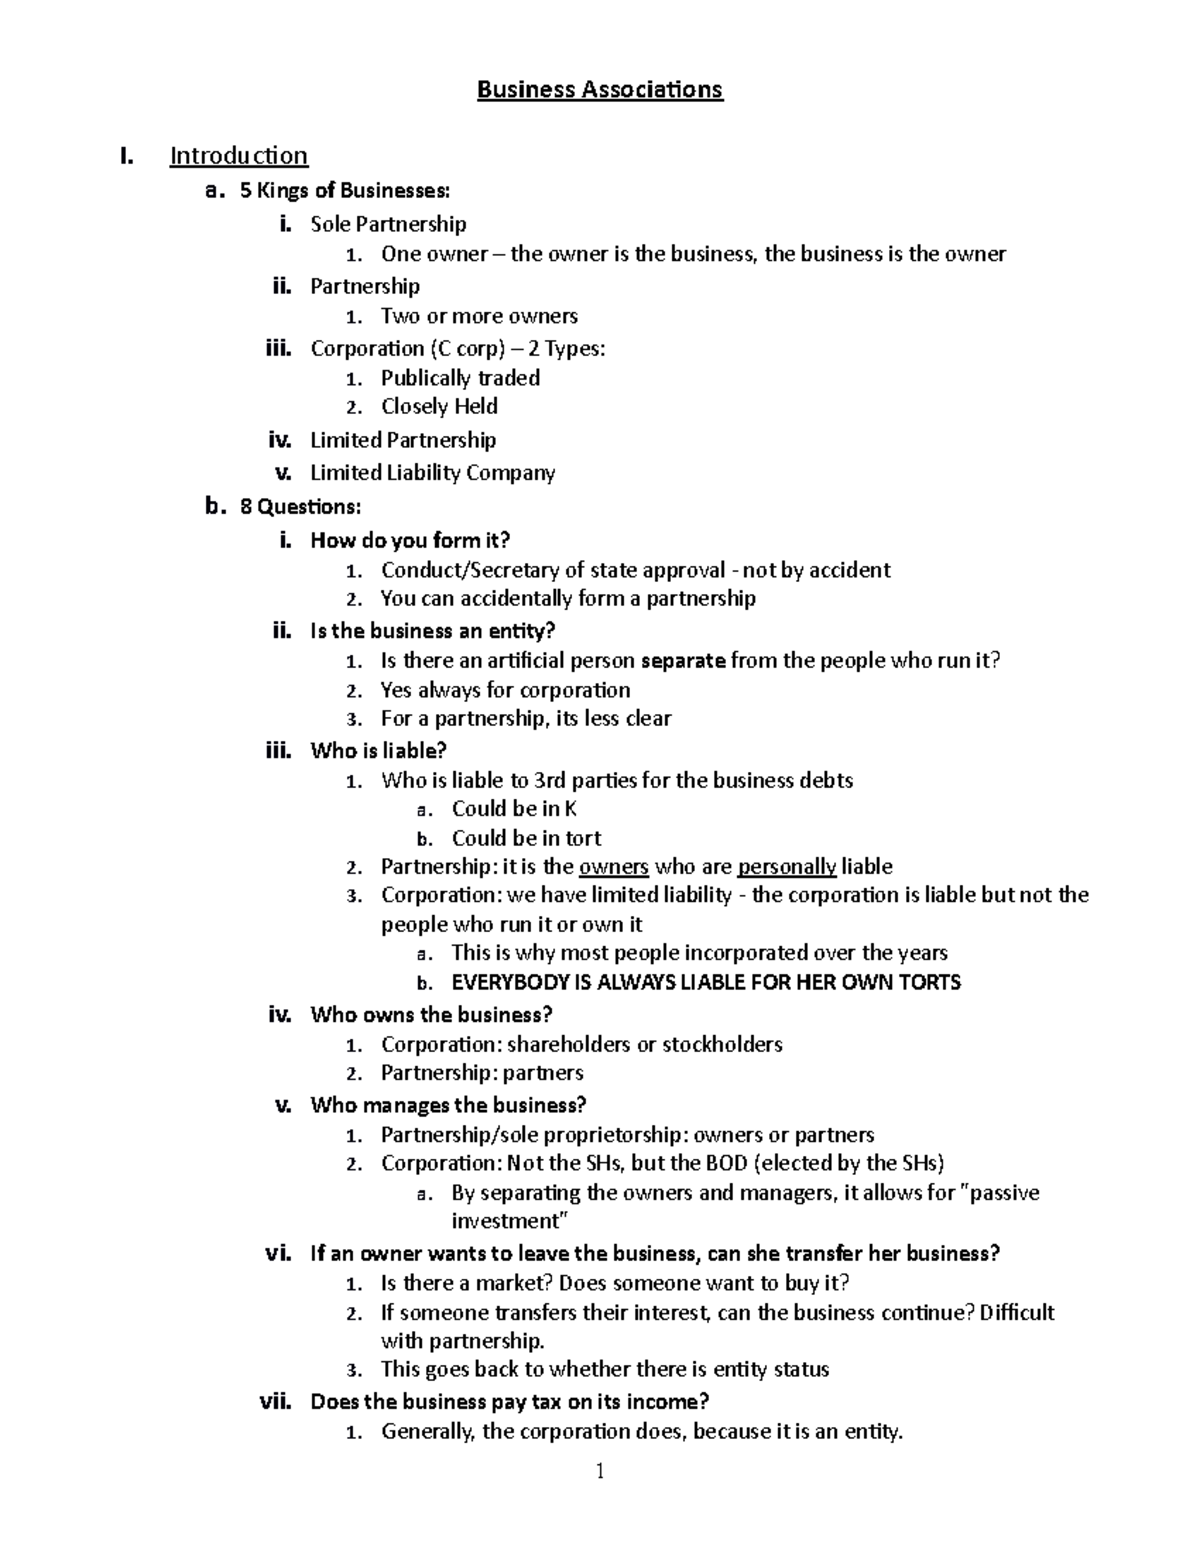
Most students treat business associations like it's just another subject to memorize. It isn't. The exam is really testing whether you can walk into a room full of stakeholders with competing interests and figure out who gets what, when, and why. If you study the wrong way, you'll know every rule but fail to apply them. I've seen it happen repeatedly over the years. Here's the practical approach that actually works. Start with the entity types. Not their definitions from the textbook, but their decision-making mechanics. Who votes? Who controls? Who gets sued? Write that down for each one before you touch a single doctrine. LLCs, corporations, general partnerships, limited partnerships, LLPs — they each have different default rules under the URAA and RULLA, and the exam loves to test what happens when the parties deviate from defaults. The most common mistake I see is students trying to learn the rules in isolation. You don't study fiduciary duty by itself. You study it alongside the duty of loyalty, the business judgment rule, and then immediately ask: what happens when a director sits on both sides of a transaction? That's where the real exam question lives. The rule is straightforward — the interested director needs disclosure and either disinterested board approval or shareholder approval. But the exam will throw in a twist like the director also controlling the shareholder vote, which shifts the standard of review entirely.
I remember working through a practice problem once where the facts described a close corporation where one shareholder was also a manager. The question asked about a self-dealing transaction at fair market value. Most students would immediately say "business judgment rule applies." It doesn't. Once you remove the protection of a public market price, the entire fairness standard kicks in regardless of what the price looks like on paper. I caught that because I'd been burned on a similar hypothetical during my own bar prep. The workaround was to always check: is this a public company or a close one? That single fact changes the entire analytical framework. For the MBE-style questions, the trick is recognizing the issue before you read the answer choices. Every business associations question is really asking one of four things: who controls, who benefits, who is liable, and what procedure must be followed. When you see a fact pattern, identify those four things immediately. Don't get distracted by narrative details. If the question describes a heated board meeting in detail but never mentions whether a quorum was present, the procedural defect is the issue, not the drama. State corporate law matters more than you think. The Model Business Corporation Act is the baseline, but many exams test variations. Delaware General Corporation Law has different rules on director liability, indemnification, and advance of expenses. If the question cites a specific state, pay attention. The DGCL section on Section 141(j) allows full exculpation of directors for money damages except in cases of intentional conduct or knowing violation of law. That's a frequent trap because students conflate the standard of care with the standard of loyalty.
Partnership law questions tend to be shorter but sharper. The default rule under the Uniform Partnership Act is that partners share profits and losses equally, regardless of capital contribution. That alone accounts for several questions every exam. Add in the concept of apparent authority — a partner can bind the partnership to contracts with third parties who reasonably believe the partner has authority, even if the partner acted outside their actual authority. The partnership pays first, then seeks contribution from the rogue partner. The third party doesn't care about your internal agreements. When it comes to studying, doing old exams is non-negotiable. Read the actual questions, not just the answer explanations. The explanations tell you why the right answer is right. The questions teach you how the examiner thinks. I spent more time analyzing why three wrong answers were wrong than why the correct one was right. Each distractor is usually built around a common misconception. The "obviously correct" answer that turns out to be wrong is almost always missing a factual prerequisite that the question silently supplies. One specific area that catches people off guard is the distinction between a member-manager and a manager-managed LLC. The default under the Uniform LLC Act is member-managed, meaning every member has apparent authority to bind the company. But if the articles organize it as manager-managed, only the designated manager has that authority. The exam will give you a fact pattern where a member signs a contract and you have to determine whether the LLC is bound. Check the operating agreement classification first. Everything flows from that.
Get the Full Details
Derivative suits are another frequent topic. The key elements are demand futility, contemporaneous ownership, and proper party structure. If demand is required and not excused, the suit fails. Demand is excused only if the plaintiff can show with particularity that the board couldn't exercise independent business judgment. "Could not" not "would not." The standard is higher than most students expect. A mere conflict of interest isn't enough — you need to show the conflict actually compromised the board's ability to deliberate objectively. For the essay portion, IRAC is useful but incomplete. The real differentiator is recognizing hybrid issues where two doctrines interact. A question might start as a veil-piercing inquiry but then introduce a fiduciary duty claim against a controlling shareholder. The analysis needs to address both sequentially. Piercing the corporate veil is the easier path — show control plus fraud or injustice. But if veil piercing fails, you still need to analyze whether the controlling shareholder breached a fiduciary duty as a result of that control. Skipping that second analysis costs points even when the first part is correct. There's no shortcut for understanding the policy behind the rules. Why do we have fiduciary duties in close corporations but not typically in public ones? Because there's no market discipline. Why do we allow exculpation of directors under DGCL Section 102(b)(7)? To encourage qualified people to serve without fear of endless litigation. When you understand the why, the rule becomes easier to apply to novel fact patterns, which is exactly what the harder questions test.
The last thing I'll say about preparation: time management during the exam itself. Business associations questions can be deceptively long. A 45-second read can hide a 2-minute analysis. Don't let a complicated fact pattern slow you down on the multiple-choice section. Mark it, move on, come back. The essay questions are where depth matters, not speed. Spend the extra time there constructing a complete analysis rather than rushing through three essays superficially.