Setting Up Trade Credit Lines Without Getting Burned by Suppliers
I spent three years watching small business owners pile up credit card debt trying to build business credit the old way — submitting applications on bad faith, getting declined because Dun & Bradstreet showed a blank file, then spiraling into predatory subprime lenders who charged 24% APR. The whole process is less mysterious than people think once you strip away the guru marketing. The core mechanic is simple: suppliers extend net-30 terms to your company, you pay on time, they report to the commercial bureaus, your business credit profile strengthens, and eventually you qualify for larger lines of credit. That's it. The trick is doing it without triggering every red flag that makes a lender assume you're running a shell company. The first thing I learned the hard way is that not every net-30 vendor matters equally. There's a hierarchy here. Some report to all three major commercial credit bureaus — Dun & Bradstreet, Equifax Business, and Experian Business. Others report to only one, or none at all. If you're signing up with a vendor that doesn't report to D&B, you're basically doing the world a favor. I used to batch together twenty-seven net-30 accounts across random vendors, thinking volume was the strategy. It wasn't. Volume with non-reporting vendors just creates administrative noise and confuses your own cash flow tracking. The real move is picking a smaller number of high-quality reporters and going deep on them.
Business Credit Building Services
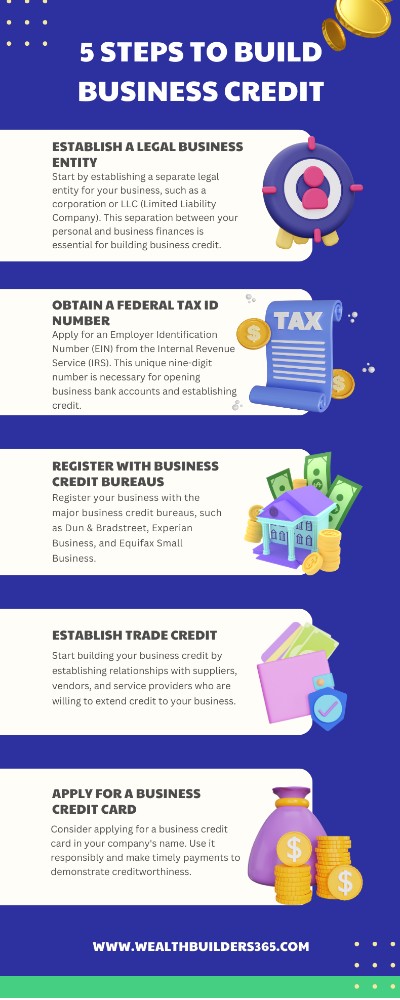
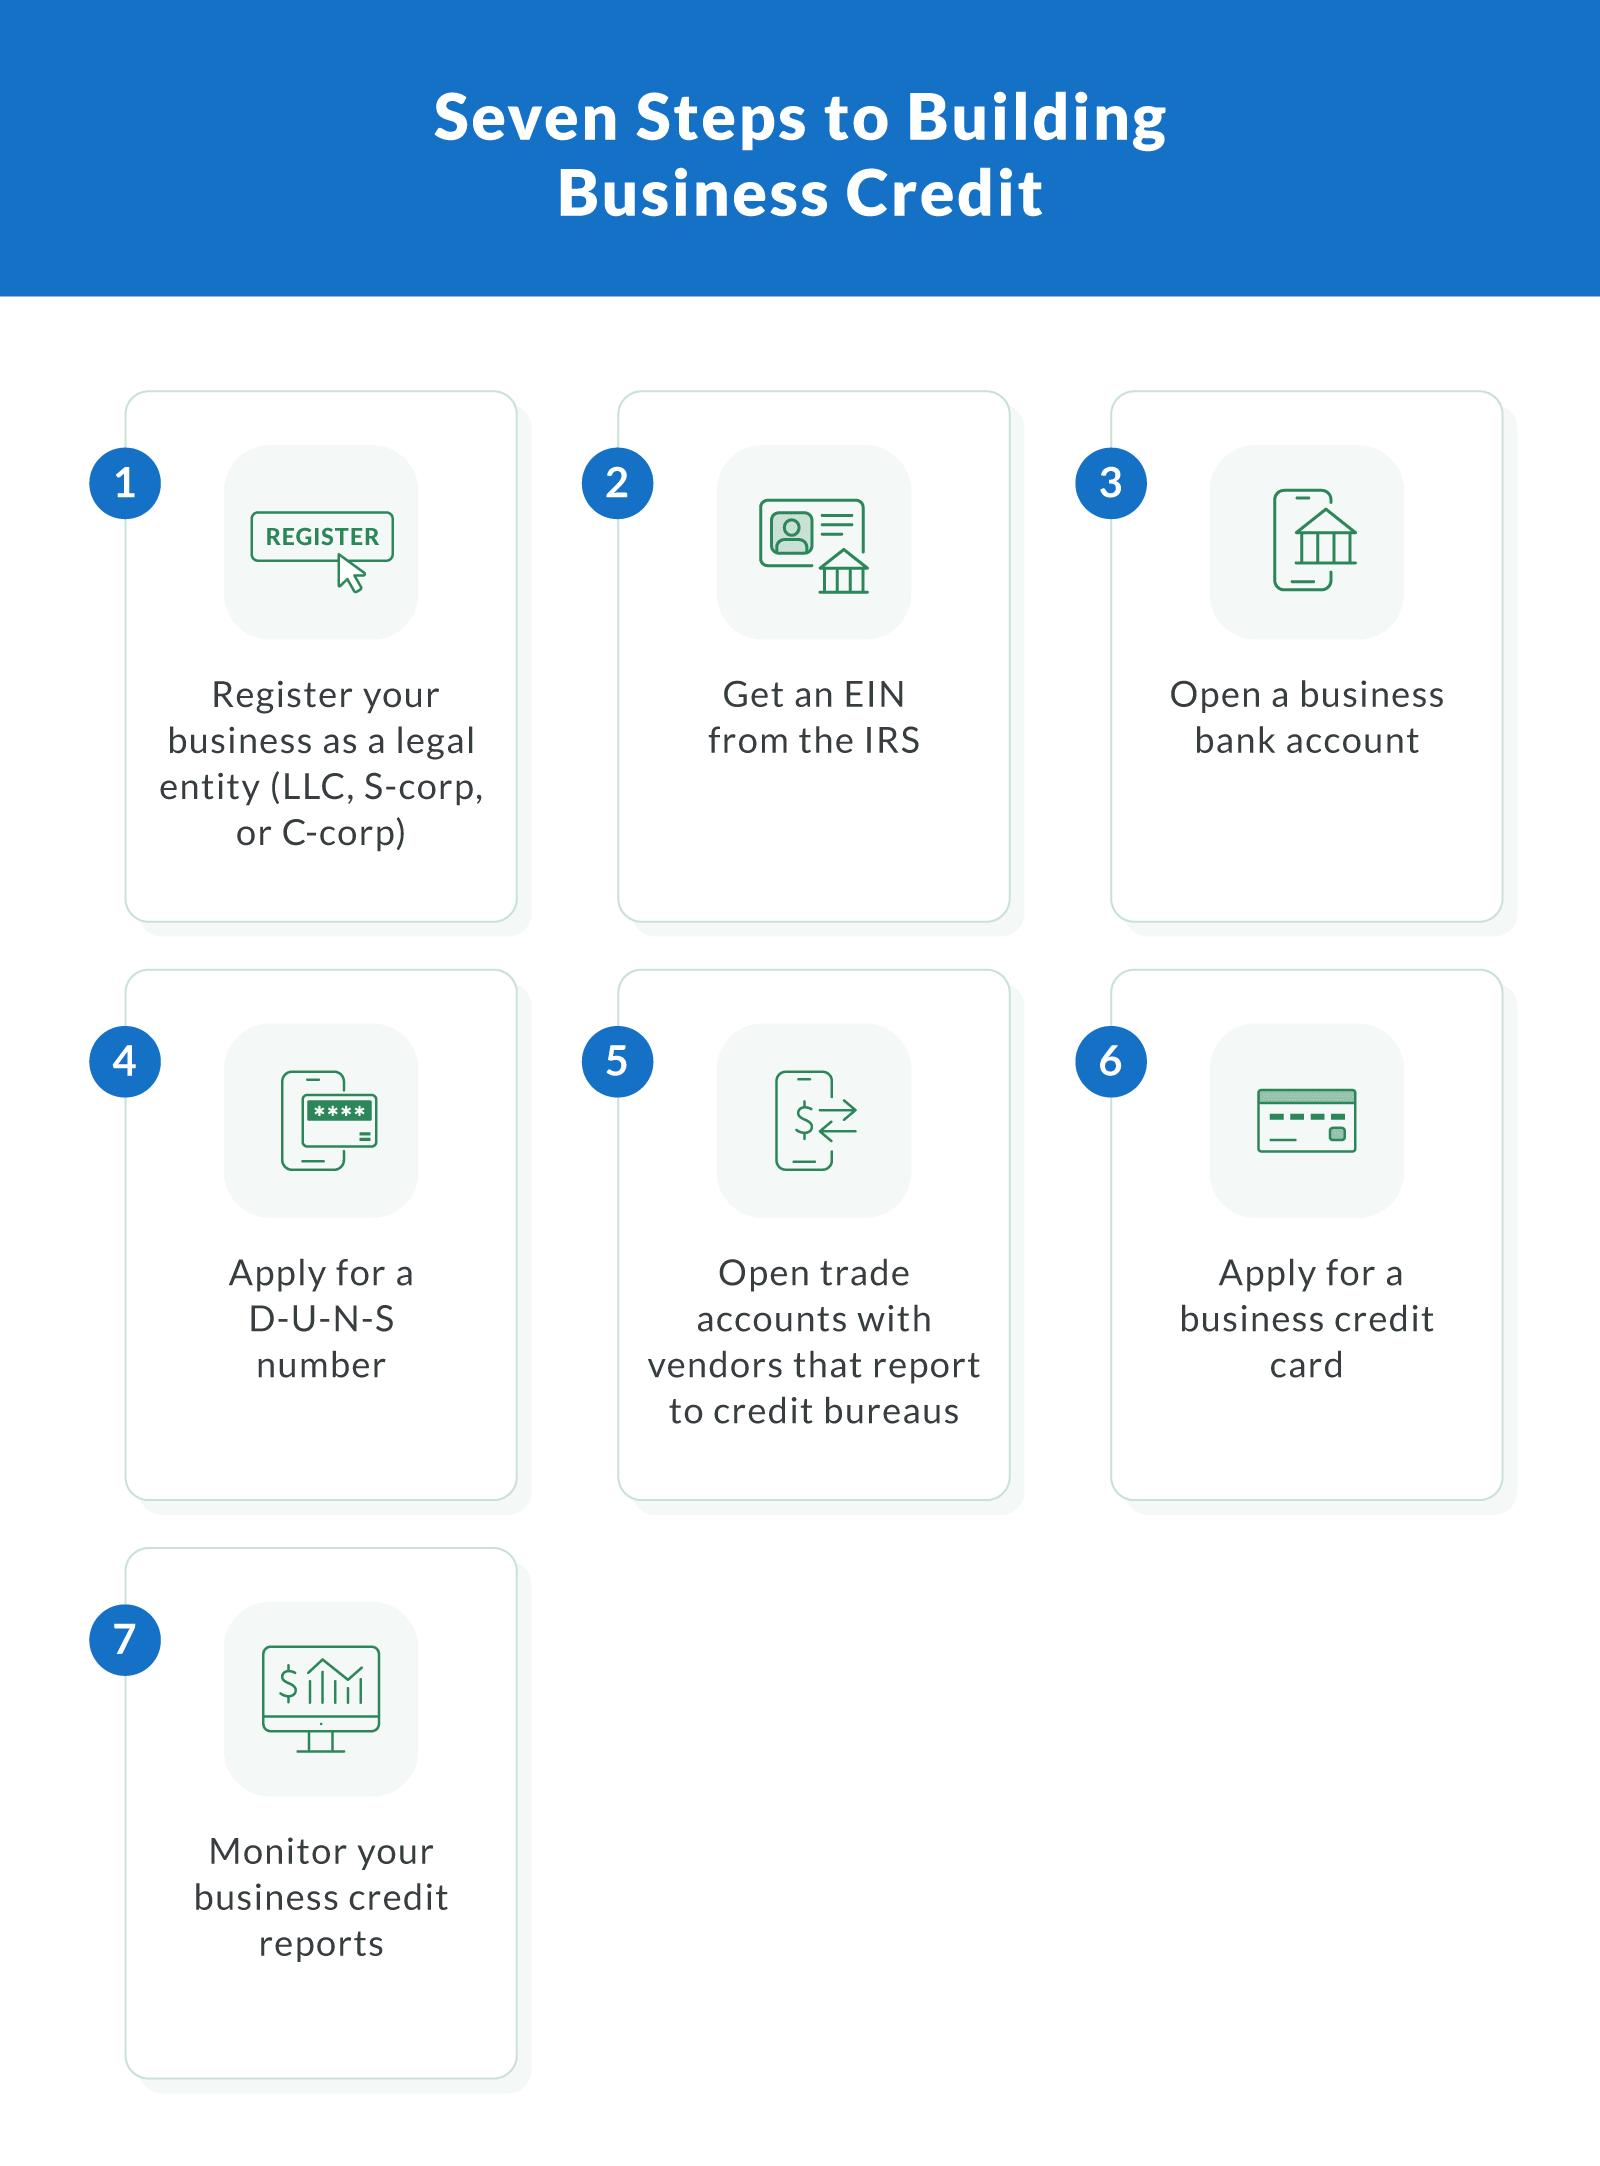
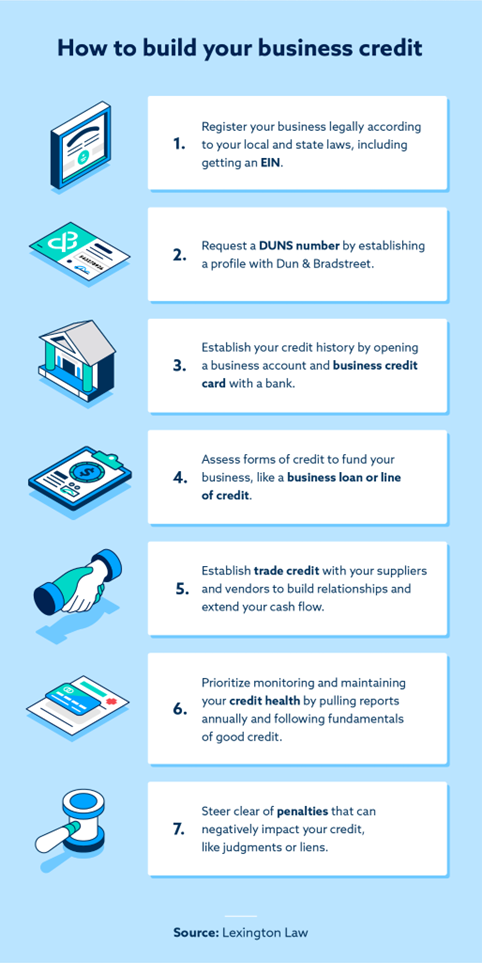
When people search for Business Credit Building Services, they usually stumble into two categories: do-it-yourself frameworks that teach you the sequence of applications, and managed services that open accounts on your behalf for a monthly fee. Neither approach is wrong, but they serve different people. The DIY route works if you have time, patience, and a reasonable understanding of how the credit ecosystem operates. The managed service route works if you're a busy business owner who wants someone else to handle the grind. The problem is that the managed service market is almost entirely unregulated. There's no licensing requirement, no standardized disclosure, and plenty of companies charging $200 to $500 a month for something you could start doing yourself in an afternoon after reading a few actual guides instead of watching a YouTube video. Here's what a legitimate service should actually do for you: obtain your Employer Identification Number from the IRS if you don't have one, register your business with the state, set up a dedicated business banking relationship, establish a physical business address that isn't a residential mailbox, create listings in the commercial directory services that the bureaus pull from — Navis, Better Business Bureau, Yellow Pages — and then systematically open net-30 accounts with vendors who report to the major commercial bureaus. If a service can't articulate each of those steps, walk away. I ran into a specific edge case that made me question a lot of the standard advice. A client of mine had excellent personal credit, ran a legitimate landscaping business, and wanted net-30 terms with a supply house. The supply house required a D-U-N-S number, which she didn't have. She applied through D&B, waited five business days, got the number, then went back to the supplier. Three weeks later, the supplier reported her account to D&B, but she saw zero impact on her credit score for six months. The reason turned out to be that the bureau requires a certain minimum age of trade line history before it factors net-30 accounts into scoring models. She had been paying on time, but the data was just sitting there, aging out, invisible to the scoring algorithm. This is the kind of thing nobody warns you about upfront. The workaround was to continue paying on time and let it mature, then layer in two or three more reporting trade lines from different bureaus to create enough signal volume for the models to pick up on.
Another counter-intuitive insight that most people miss: having too many hard inquiries on your personal credit can tank your business credit applications, even though business credit is supposed to be separate. When you apply for net-30 accounts, especially with newer or smaller vendors, they often pull a soft or hard inquiry on your personal credit as part of the application process. If you've already submitted twelve applications in thirty days, the vendor's underwriting system flags you as credit-hungry, and they decline you regardless of whether you actually deserve credit. Space out your applications. Two to three per month maximum during the first six months of building. This is one of those things that sounds obvious but almost no one follows because the gurus tell you to move fast and open everything at once. There's also a structural limitation to business credit building that nobody wants to discuss openly. Once you've built a solid commercial credit profile with net-30 accounts and maybe a small business credit card, you'll hit a ceiling. Lenders won't give you a $50,000 line of credit based purely on your trade credit history. They want to see revenue, time in business, and often collateral. Business credit is a stepping stone, not a destination. It gets you from zero credit to acceptable credit, which unlocks some credit cards and small vendor lines. But if you need actual capital for growth, equipment, or payroll, you're going to need to supplement with a bank relationship, an SBA loan, or revenue-based financing. Don't confuse a good D&B paydex score with access to meaningful working capital. If you're considering a managed service, demand transparency about which bureaus their vendor partners report to before you sign anything. Ask for a list of the net-30 accounts they open on your behalf. If they can't provide that, they're either incompetent or running a scheme where they're opening accounts with non-reporting vendors and keeping your money. Check the Better Business Bureau for complaints against the specific service. Search the company name plus "scam" or "review" on Google. Most legitimate services have a track record you can verify. The ones that don't are the ones you want to avoid.
Get the Full Details
The DIY path saves you thousands of dollars over six to twelve months. It requires about fifteen minutes of work per week once you've established your routine. You'll need an EIN, a business bank account, a registered business address, and a spreadsheet tracking every account you open, which vendor reports to which bureau, and the payment due date for each. Start with vendors like Uline, Grainger, Quill, or Summa — these are well-known net-30 suppliers with straightforward application processes. Apply to two or three per month. Pay every invoice before the due date. Do not carry a balance. Do not miss a payment. After about six months, your commercial credit profile should show consistent positive payment history, and you can begin applying for larger credit products with actual lending institutions. The whole system is designed to look more complicated than it is. That's intentional — it keeps people confused and willing to pay for answers. The actual mechanics are procedural, not mystical. You establish a business entity. You get tax identification. You open banking. You build trade references. You maintain perfect payment discipline. The bureaus compile the data. The scores adjust. You access credit. Anything presented as more dramatic than that is usually selling you something.