Getting a Business Credit Line Without Pledging Your House
Most people reach this point after their third bank loan officer asks them to co-sign on their own credit line. It gets old fast. The good news is that unsecured business credit exists, it is not a myth, and a handful of lenders actually issue it. The bad news is that "no personal guarantee" means something very specific and most applicants misunderstand what they are qualified for. I have spent enough years watching people bounce between lenders on this topic to know where the process breaks down before it even starts. The biggest issue is that no personal guarantee does not mean no personal financial information. Lenders still run personal credit checks, often with a hard pull, and they still want to see clean tax returns and verifiable revenue. The personal guarantee is what you sign away when you default — the part that makes you personally on the hook — and avoiding that is the whole point. What you still provide is transparency about your business, which is a different conversation entirely.
How Business Credit Lines With No Personal Guarantee Actually Work
The mechanism is straightforward once you stop thinking about it like a loan application. You are applying for a revolving line of credit extended to your business entity. The underwriting model shifts from personal creditworthiness to business creditworthiness, which means D&B score, payment history with vendors, years in operation, and revenue consistency matter more than your FICO number. That said, personal credit is still a factor at most mid-tier lenders. The top-tier unsecured lines from institutions like Amex, Brex, or Divvy typically require excellent personal credit as a qualifying gate even when they do not require a PG. I ran into a specific edge case last year with a client who had a D&B PAYDEX score of 82, two years of consistent revenue, and perfect vendor payment history, but her personal credit had a collection account from four years ago that she had since paid. Every automated underwriter rejected her on sight. The workaround was getting a referenced trade line first through a Net-30 vendor report that specifically reports to D&B, then letting that payment history build for sixty days, then reapplying. The lender's manual review desk saw the trajectory rather than the snapshot and approved a 25,000 dollar line. That sixty-day delay was the only thing that changed the outcome. The counter-intuitive part that nobody warns beginners about is that getting a business credit line without a personal guarantee is often harder for newer businesses than for established ones. A corporation or LLC that is three years old with documented trade references will get approved more easily than a six-month-old startup, regardless of how clean the personal credit is. Lenders price risk against time in business because there is simply less data to go on with newer entities. If your business is under two years old, your realistic options narrow significantly and you should expect higher rates or lower limits.
Here is the step-by-step of what the process looks like on my end when I prepare a client for this type of application.
Get the Full Details
- Confirm your business has a D-U-N-S number and a D&B PAYDEX score above 75. This is non-negotiable for most no-PG lenders.
- Gather three to five trade references that report to at least one major business bureau. Ideally these are vendors where you have been paying on time for at least ninety days.
- Have your last two years of business tax returns ready. Even unsecured lenders want to see filed returns. If you are a pass-through entity, bring Schedule K-1s as well.
- Prepare a sixty-day bank statement showing consistent cash flow. Lenders will look for revenue patterns and will flag any months with less than half your average deposit volume.
- Submit applications to two or three lenders simultaneously within a fourteen-day window so credit inquiries group together and do not compound the damage to your personal score.
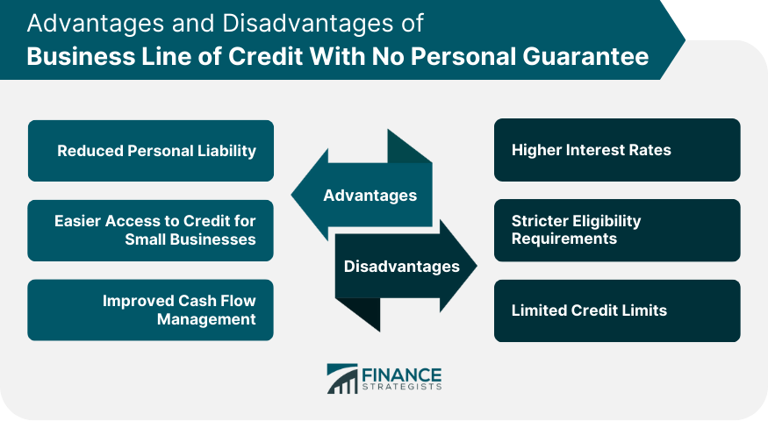
The approval timeline varies by lender but most respond within five to fifteen business days for manual reviews. Automated underwriting can deliver decisions in under an hour, but those are typically limited offers with conservative terms. A larger credit line almost always goes through manual underwriting, which means a human being reads your file and looks for things automated systems miss. That is where the edge cases get resolved and where the sixty-day trade reference workaround matters. Interest rates on unsecured business lines typically run between nine and eighteen percent, depending on your credit profile and the lender. Brex and similar fintech lenders often sit on the lower end for well-qualified applicants but require strong personal credit and solid revenue. Traditional banks like Synovus or Regions offer unsecured lines in the middle range but their approval thresholds are stricter on the business side. Online lenders like OnDeck or Fundbox are easier to qualify for but charge substantially more and have shorter draw periods that can create cash flow friction. There are honest limitations to this approach that I need to call out directly. The biggest one is that unsecured business credit lines rarely exceed fifty thousand dollars for businesses under five years old. If you need a hundred thousand or more, you are going to run into a wall unless you can offer collateral or provide a partial personal guarantee on a portion of the line. Some lenders will split it — fifty thousand unsecured and fifty thousand secured — but that reintroduces the personal risk element you were trying to avoid in the first place.
Another limitation that catches people off guard is that some lenders report your credit line activity to personal credit bureaus even when they do not require a personal guarantee. A missed payment on a no-PG business line can show up on your personal report under certain lenders' policies. Before you sign anything, ask specifically whether they report to personal credit. A few major lenders do and you will not find out until it is too late. The one area where this approach genuinely fails is for service-based businesses with irregular revenue cycles. Consulting firms, agencies, and seasonal operations often cannot demonstrate the consistent cash flow that unsecured lenders require. In those cases, a secured line using accounts receivable as collateral is the better path. It is not as clean as a pure unsecured line but it delivers higher limits, longer terms, and the personal guarantee stays off the table because the collateral backs the obligation instead. If you are actively looking to apply, the main lenders that consistently issue no-PG business lines right now are Brex, Divvy, Amex Green Blue and Platinum Business lines for qualifying members, and a small group of regional banks that have dedicated small business unsecured products. Each has its own threshold and I would recommend checking your eligibility on their sites before submitting a full application. Most do a soft pull for prequalification that gives you a term estimate without affecting your credit score, which saves you inquiry points on guesses.
The process takes roughly forty-five minutes of document gathering and about two weeks from application to funded line once you have all your materials organized. If you are missing trade references or your D&B file is thin, budget an additional two to three months to build the necessary history. There is no shortcut around that part and anyone telling you otherwise is selling you something.